Samolet and Sber: what will be left for bondholders
Samolet bondholders stand in line behind the banks, and a deal with Sber can only lengthen that line. The bonds are issued by the parent PAO, which had RUB 0.17bn in cash on its accounts at 30 June and pays with the money that moves up to it from the project subsidiaries. If Sber enters the capital of those subsidiaries, it could change the cash flow that reaches the holding. A soft option (a deferral and lower rates on the bank's loans), by contrast, is good for the bonds. The terms are not yet defined, so over four days the market has priced in the worst case.
Update of 21 September. We spoke with the company. Samolet is not yet making an official statement and does not confirm the Kommersant story. According to IR, negotiations with the banks are constructive. Since 17 September there have been no public documents about a deal, no issuer disclosures, no statements from Sber or regulators, and no rating actions. In the meantime the market has kept selling the bonds. From the 18 September close, the long issues lost another 3-7 pp and trade at 63-70% of par, and P11, with an offer in February, fell to 78%. The share is down 20% since 14 September and 30% since the start of the month. The issues maturing on 28 September and 30 October still trade at par. The prices, the probability calculation and the section on our position below are updated for trading on 21 September.
Update of 25 September. The company sent comments on the review. We added to the chronology the redemptions at the BO-P13 and BO-P15 offers, quoted the Ministry of Finance statement on state support, set out the company's position on the accounting of the loan for the purchase of MIC, and clarified several wordings. The figures, prices and calculations have not changed and remain as of 21 September.
On 17 September Kommersant, citing three sources, wrote that Sberbank may receive under management part of the business of GK Samolet as part of a loan restructuring. Two options are being discussed. In the first, the loans are restructured against the pledge of the beneficiaries' personal assets unrelated to development. In the second, the bank enters the capital of the subsidiaries that build residential complexes on its project financing. At the end of 2025 Sber was the group's largest creditor: RUB 274.2bn, or 30.6% of all debt. Samolet and the bank declined to comment.
The negotiations themselves are not news. In its 1H IFRS statements published on 28 August, the company directly writes that it "is negotiating with key creditor banks to restructure the existing loan portfolio and reduce the current debt burden". What is new is only that the form of a possible deal has reached the press.
- The real corporate debt burden is twice what the company shows. Loans for the purchase of MIC and land of RUB 104bn are accounted as project loans, although escrow does not cover them.
- The business does not earn enough to cover interest. Half of adjusted EBITDA is an accounting effect from escrow, and accrued interest for the year is almost twice the cash part of EBITDA.
- The bond issuer carries guarantees of RUB 1.44trn against equity of RUB 11bn. Banks are protected by pledges of land and stakes in subsidiaries; bondholders are protected by nothing.
- The main risk window is January-February 2027. From September to February holders are owed about RUB 26bn, of which RUB 15.7bn is the redemption of P13 and the P11 offer.
- The market puts the chance of timely payment on the January issue at roughly 63-74%, and on the February P11 offer at 48-62%. The two nearest issues (September and October) trade at par.
What is happening: revenue fell by a third, a loss of RUB 22bn, and the company has been looking for money since February
According to the unified register of developers (ERZ) cited by ACRA, at the start of 2026 Samolet had the largest volume of construction in progress among Russian developers. It ended the first half of 2026 with revenue of RUB 117.4bn (-31% y/y), adjusted EBITDA of RUB 41.8bn (-27%) and a net loss of RUB 22.3bn. On the 28 August analyst call, CFO Nina Golubnichaya said that sales in the first half fell about 15 pp more than the market. The explanation, in her words: customers were scared off by the February letter on state support. In February the company asked the state for a concessional loan of RUB 50bn. No direct support was provided; indirect measures were discussed instead (Interfax, 19.02.2026). On 24 February the Ministry of Finance said that, after reviewing the documents and results of operations, it saw no preconditions for financial instability risks at the group (RIA Novosti).
Events then unfolded as follows:
- December 2025 – ACRA downgraded the rating to A-(RU), outlook stable;
- 3 February 2026 – on the BO-P13 offer the company redeemed RUB 15.2bn of the RUB 24.5bn issue;
- 5 May 2026 – technical default on coupons of three issues. The money reached the depositary overnight, a few hours late, and was paid within the grace period;
- 7 August – on the BO-P15 offer RUB 3.1bn of the RUB 5bn issue was redeemed;
- 10 August – the fund of the heirs of co-founder Mikhail Kenin sold 18% of the shares to Kazakhstan's Fonte Capital for about RUB 4.2bn;
- 28 August – half-year statements, mentioning restructuring negotiations and a covenant breach on one loan of RUB 3.0bn;
- 11 September – according to ABN, the Federal Tax Service filed a bankruptcy petition against one of the group's project developers, OOO SZ Paveletskaya (Stremyanny 2 residential complex). We did not check the amount of claims or the further course of the case;
- 15-21 September – the bonds lose 10-30 pp. The selling began two days before the Kommersant publication and continued after it.
The company's market capitalization on 21 September is about RUB 15bn against debt of RUB 773bn.
Corporate debt is not RUB 113bn but RUB 217bn
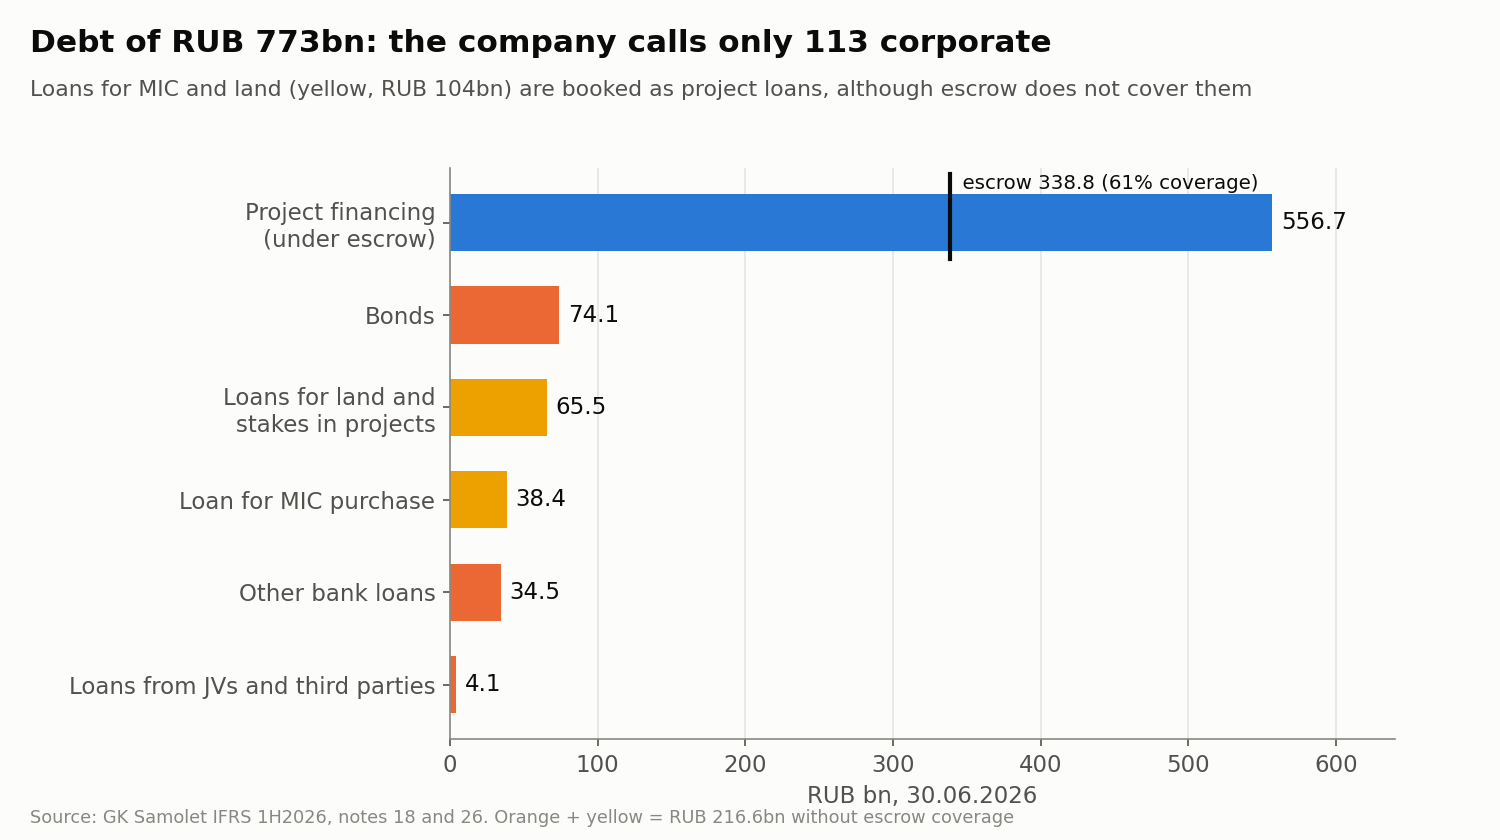
The company divides debt into two parts. It treats project financing (RUB 660.6bn) as secured by buyers' money in escrow accounts, and calls everything else corporate debt (RUB 112.7bn). Its corporate debt to EBITDA is 0.94x.
In note 18, within project financing there are two lines that have nothing to do with escrow. The 2023 loan for the purchase of the MIC group is RUB 38.4bn. The loans for the purchase of stakes in project companies and land plots are RUB 65.5bn, of which RUB 45.6bn must be repaid within a year. Buyers deposited nothing for this money, and it will have to be repaid from project margins or land sales.
The company explains this accounting by established market practice: the MIC group is essentially a land bank and project documentation, that is, the loan went to expand the core asset and not a side business. We agree with the economic sense of the purchase. But for assessing the burden something else matters: escrow does not cover these loans, and they will have to be repaid from project margins or land sales.
Authors' estimate. With these loans, corporate debt is RUB 216.6bn, and net of RUB 9.9bn of cash it is RUB 206.8bn. Against 12-month adjusted EBITDA (RUB 109.4bn) this gives 1.9x instead of 0.94x. If we take only the cash part of EBITDA (see the next section), it is 3.7x.
Construction is covered by escrow at 61% against 69% half a year earlier: RUB 338.8bn in accounts against RUB 556.7bn of project loans. The uncovered part carries the base rate, so the average rate on the portfolio (11.8%) does not fall following the key rate. The company expects project debt to continue growing until the end of the year. It is not stopping construction, there are no new launches, and there will be no apartment fire sales.
Short-term obligations are large. Of RUB 325.3bn of short-term loans, about RUB 113bn is not project financing under escrow: bonds (22.9), land loans (45.6), the MIC loan (12.3), bank loans (29.0) and other borrowings (3.3). Undrawn limits of RUB 519bn look large, but they are mostly project lines for specific construction sites, and bonds cannot be repaid with them. In July-August the company signed RUB 11.5bn of new non-project loans.
A developer's EBITDA: half of it is the escrow effect
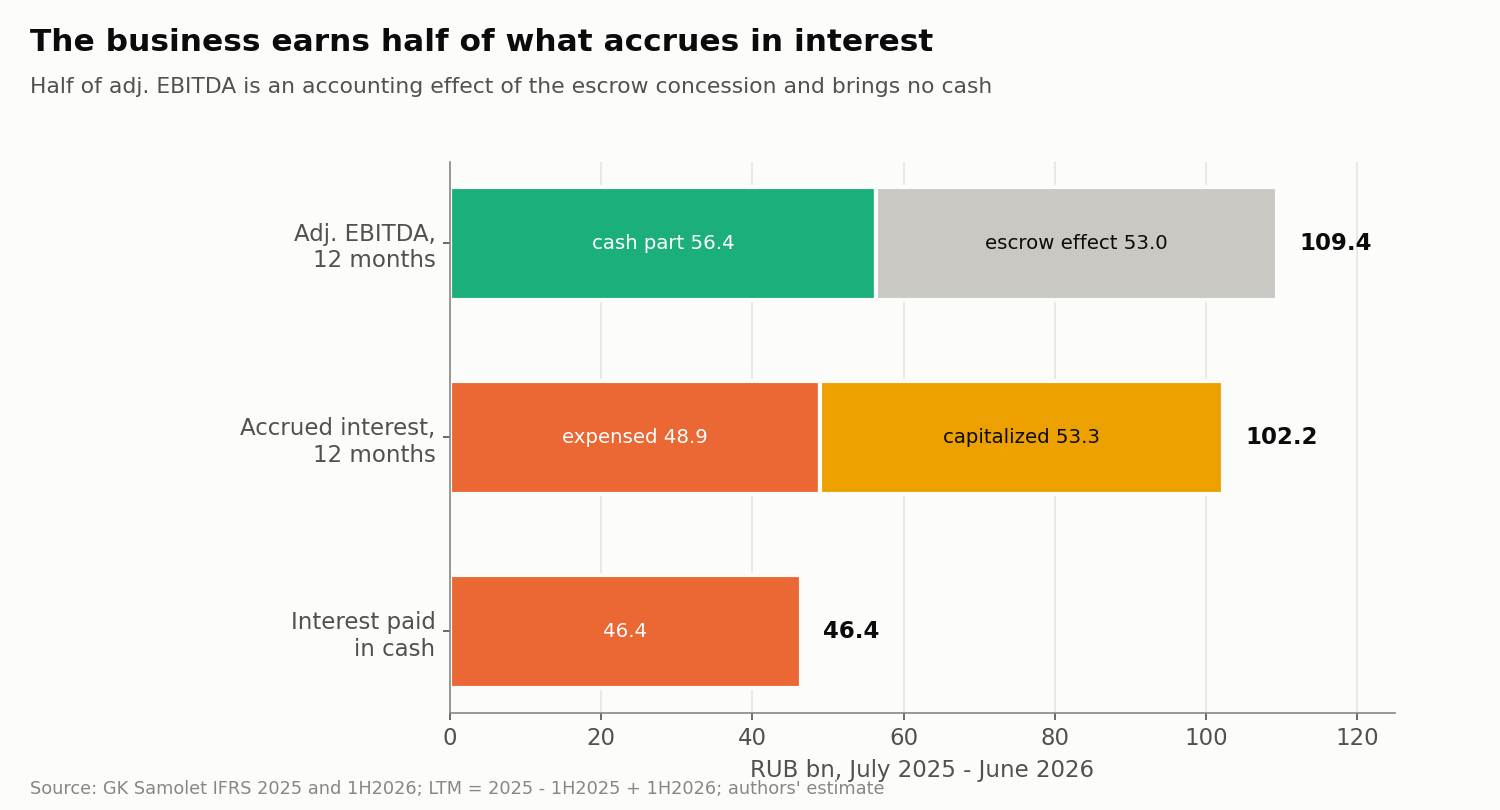
Under IFRS a developer recognizes in revenue the so-called escrow saving, the difference between the market and the concessional rate on a project loan. It brings in no actual cash. Over 12 months the effect was RUB 53.0bn out of RUB 109.4bn of adjusted EBITDA.
Accrued interest over the same period was RUB 102.2bn: RUB 48.9bn went through expenses and RUB 53.3bn was capitalized into the cost of assets under construction and land. Cash interest paid for the year was RUB 46.4bn, and the rest accumulates in the body of project loans and will be repaid when escrow is released.
Authors' estimate. Cash EBITDA (RUB 56.4bn) covers accrued interest 0.55x. The company itself explains why the loss does not alarm it. The gap between profit and cash in development averages 3 years, and what matters is that the future price of the apartments on the balance sheet is higher than the accumulated loss. The logic is right for a company that can survive those three years. For a creditor it means that the business can now service its debt only with new borrowing or asset sales.
There is almost no capital buffer. The group's equity at 30 June was RUB 23.0bn against assets of RUB 1,031bn (2.2%), of which RUB 8.3bn belongs to PAO shareholders. Over the half-year equity halved. Another RUB 35.5bn of assets is deferred tax assets, which turn into cash only when the company returns to profit.
The bonds are issued by a holding that guaranteed its subsidiaries' loans of RUB 1.44trn
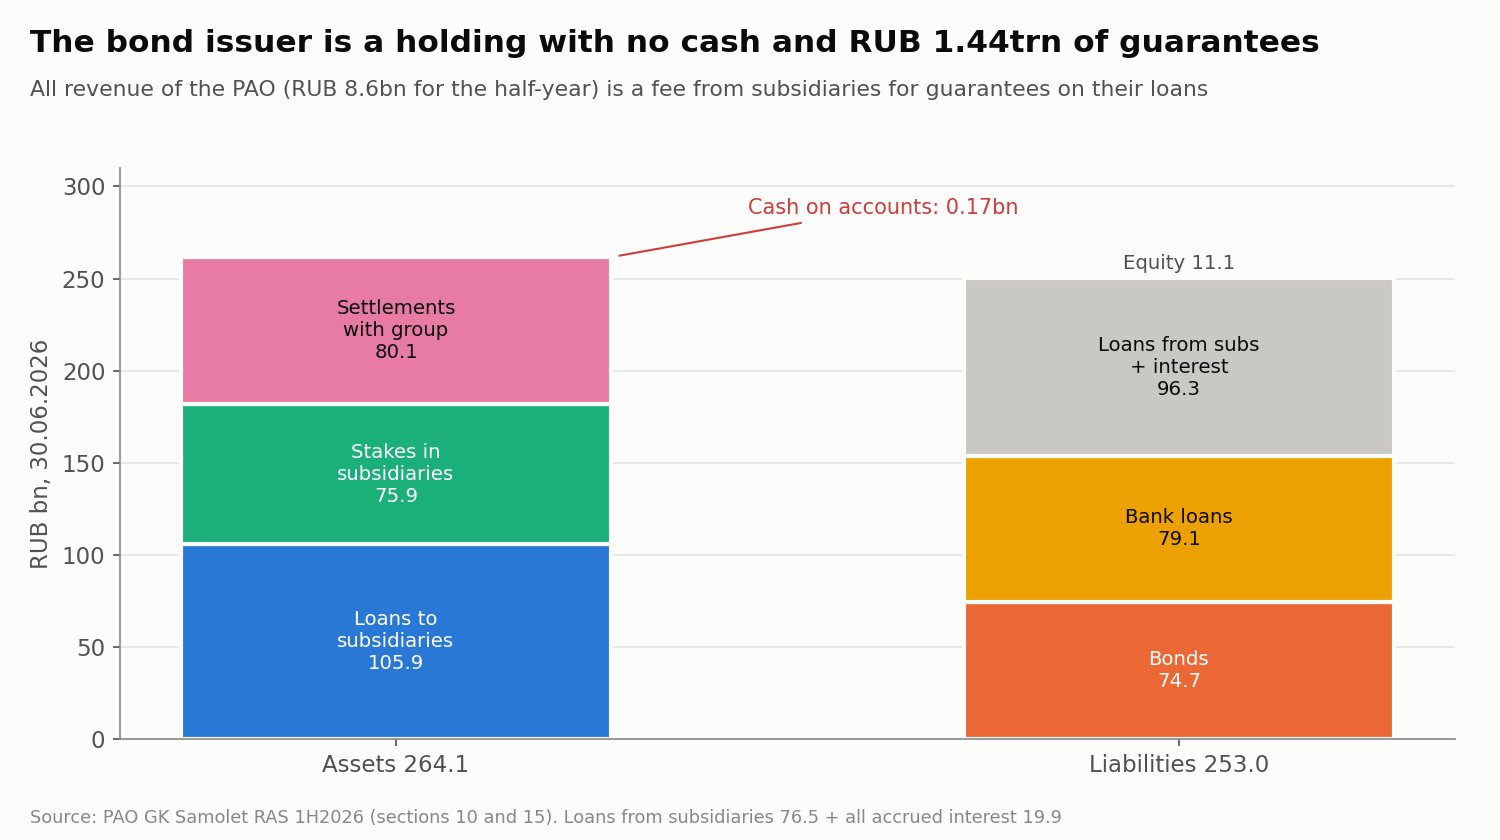
Besides the consolidated picture, it is useful for a bondholder to look at the RAS statements of PAO GK Samolet: this is the company that owes on the bonds. According to them, at 30 June:
- cash on accounts of RUB 0.17bn;
- debts of RUB 253.0bn: bonds RUB 74.7bn, bank loans RUB 79.1bn, loans from its own subsidiaries RUB 76.5bn and accrued interest RUB 19.9bn;
- assets are mostly intra-group: loans to subsidiaries RUB 105.9bn, stakes in subsidiaries RUB 75.9bn, settlements with group companies about RUB 80bn;
- equity of RUB 11.1bn;
- all revenue for the half-year (RUB 8.6bn) is the fee from subsidiaries for guarantees;
- security issued on loans and guarantees of RUB 1,443bn.
This shows how the risk is structured. The PAO guaranteed its subsidiaries' loans, so if there are problems the banks will bring claims against both the project company and the holding. Unlike bondholders, banks have collateral. Under IFRS, banks hold as pledge rights to land and buildings under construction of RUB 268.5bn, stakes in subsidiaries with net assets of RUB 49.9bn and claims on loans of RUB 12.2bn. The bonds are unsecured.
One more detail from the RAS statements. Interest on the loans the PAO received from its own subsidiaries is not paid but accumulates: long-term debt on them rose from RUB 7.9bn to RUB 15.0bn over six months. The holding saves cash on intra-group settlements in order to pay external creditors.
What remains with Samolet depends on whether Sber releases the guarantees
Which projects are being discussed for transfer to the bank has not been disclosed. We can analyze how different forms of deal change the position of bondholders.
Restructuring of loans against the pledge of the beneficiaries' assets is the best option for the bonds. The bank gets additional security, rates and maturities on the loans are eased, and the group's cash flow stays within the group. The holding gets time and free cash for the 2027 redemptions. Artem Perminov (BCS World of Investments), in a comment to RIA Novosti, also calls a significant improvement in loan terms a positive scenario.
Sber entering the capital of the project subsidiaries is a neutral or negative option, depending on the details. Projects financed by Sber (about RUB 274bn of debt) cease to be fully owned by the group. The margin of these projects, which would earlier have moved up to the holding after repayment of the project loan, partly goes to the bank. In return, the holding may be relieved of guarantees on these loans and of the risks of these construction sites. For bondholders the deal is beneficial if the released guarantees are worth more than the margin given up. The bonds remain a debt of the reduced group.
A restructuring that touches the bonds is the worst option. There are no signs of this in the disclosures. Bonds are about 10% of the group's debt (74bn out of 773), so servicing them in full costs the banks little and keeps the company's access to the market. Without that money the company cannot refinance. Worse, with weak sales the banks dictate the terms, and bondholders have neither collateral nor a seat at the negotiating table.
After either deal the group will keep projects financed by other banks (about 70% of debt), the land bank and service businesses. Land on the balance sheet is worth RUB 372.6bn, of which RUB 243.0bn is plots that do not yet have construction permits. Capitalized interest is included in this value. Land is expensive in the statements but sells slowly: there are almost no new launches on the market, and in the half-year Samolet sold plots for RUB 4.9bn. Most of the land is also pledged.
By the end of February holders must be paid about RUB 26bn
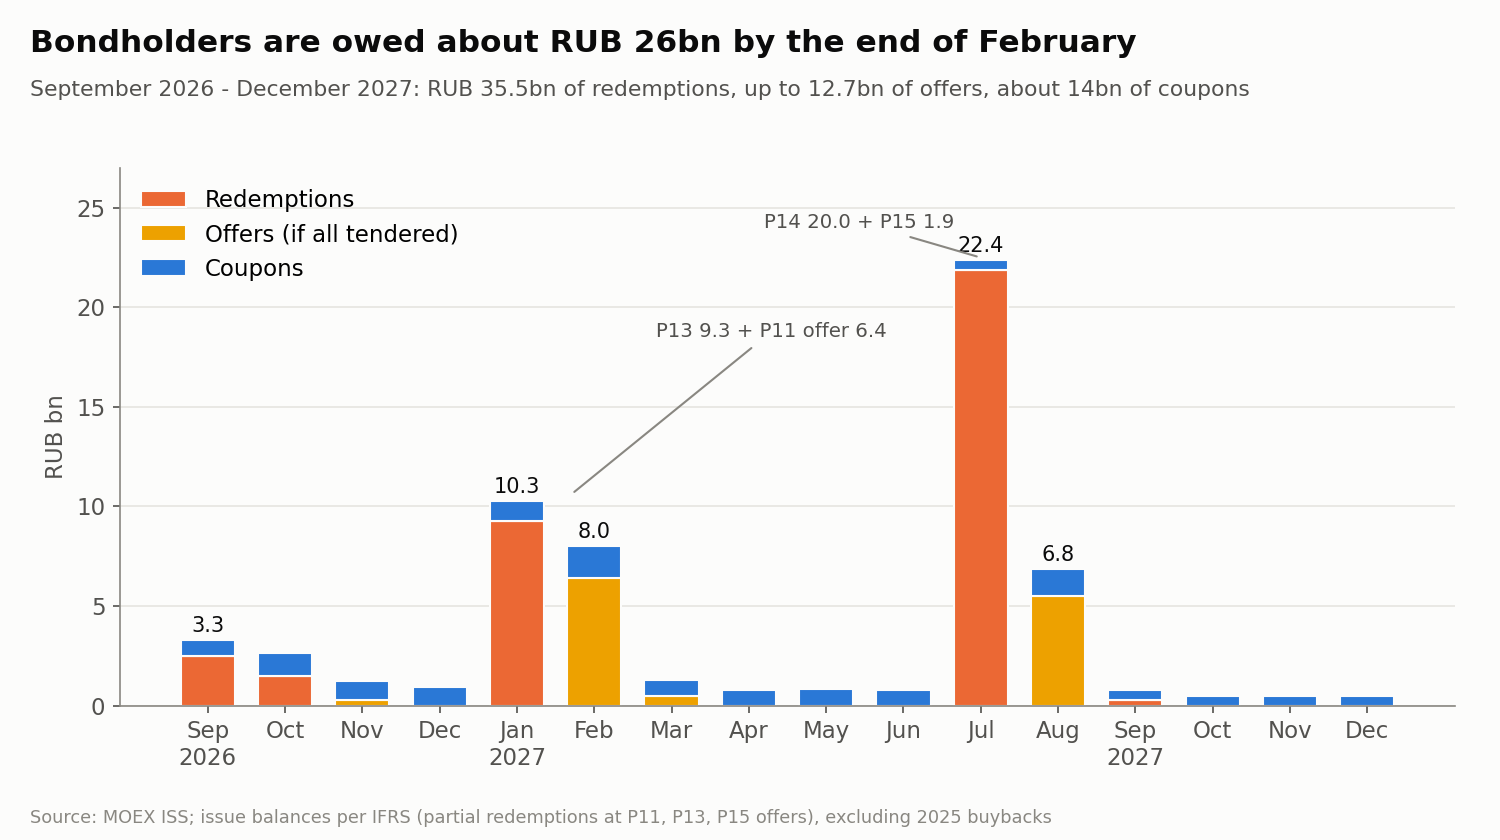
The nearest payments:
- 28 September 2026 – redemption of BO-P20, RUB 2.5bn;
- 30 October – redemption of issue 01, RUB 1.5bn;
- 24 January 2027 – redemption of BO-P13, RUB 9.3bn (the balance after the February 2026 offer, at which RUB 15.2bn of RUB 24.5bn was redeemed);
- 12 February – offer on BO-P11, up to RUB 6.4bn;
- 22 July – redemption of BO-P14, RUB 20.0bn;
- 30 July – redemption of BO-P15, RUB 1.9bn.
Plus coupons of about RUB 1bn a month. In total, about RUB 74bn of bonds are outstanding.
On the 28 August call, asked about the January-February redemptions, the CFO answered that the plan "exists and existed a year ago", that the 2026 offers went well and the redemptions will go the same way. Now the fulfillment of this promise depends on the banks' decision.
The market already prices the January issue as a security with noticeable risk
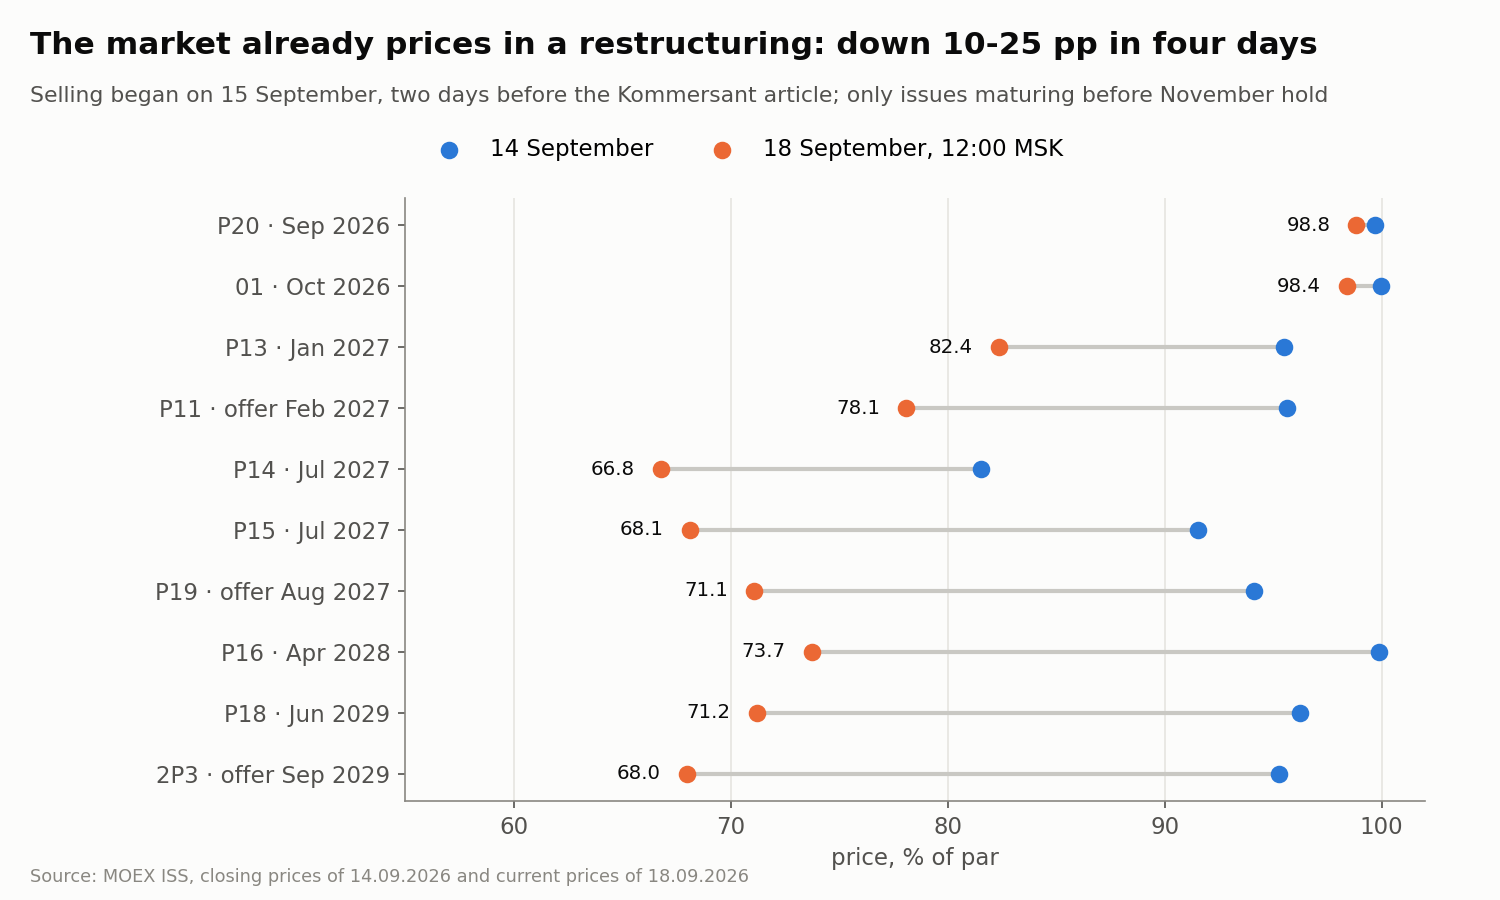
Prices on the Moscow Exchange on 21 September (last trades of the day, checked against Smart-Lab):
- BO-P20, maturing 28 September – 99.0% (99.5% on 16 September);
- issue 01, maturing 30 October – 98.5% (99.5%);
- BO-P13, maturing 24 January – 85.3% (92.4%);
- BO-P11, offer on 12 February – 78.2% (92.5%);
- BO-P14, maturing 22 July 2027 – 65.3% (79.1%);
- BO-P18, maturing 2029 – 67.6% (90.0%).
BO-P13, maturing in four months, costs 85.3% of par. If the issue is repaid on time, the holder gets 100% of par plus five monthly coupons (about 8.6%). Yield to maturity per the exchange is about 100% a year.
Authors' estimate: the probability of timely payment that the prices imply (taking account of accrued coupon and discounting at 14% a year):
- P13: with 40% of par recovered if there are problems – 74%, with 50% recovery – 69%, with 60% recovery – 63%;
- P11 (February offer): 62%, 56% and 48% respectively.
Since 18 September the January issue has even gained slightly, while the February P11 offer lost 4 pp. The market separates these two payments more than it did a week ago.
The recovery figures are taken as assumptions. What it will be in practice cannot be predicted until the structure of the deal is known.
The long issues trade at 63-70% of par. For BO-P18 (24% coupon to 2029), the current yield at a price of 67.6% is about 35%, and yield to maturity per the exchange is 55%.
The bond strategy of Enhanced Investments on the portal includes two Samolet issues: BO-P11 and BO-P18. We hold them because in the base scenario it is more beneficial for the banks that the group finishes the houses and keeps servicing public debt. What is at stake for them is their own project loans and the buyers' unfinished houses, while the bonds are only a tenth of the debt. The tests of this scenario will be the payments on 28 September and 30 October and the first official terms of the deal with Sber. The conversation with the company rather confirms this logic, but there is no official document yet, so we are not adding new money to these bonds until the terms are disclosed. As of 21 September both issues remain in the strategy with unchanged weights.
Questions that need official answers
We sent these questions to the company's IR on 18 September. A conversation took place, but the company promises to disclose official figures on them later, so the list remains open.
- Which project companies are being discussed for transfer to Sber: how many square meters, how much project debt and escrow balances do they hold?
- Are the PAO's guarantees on the loans of these projects released as part of this? How much of the RUB 1.44trn of security issued will remain on the holding?
- Does the restructuring extend to the bonds? Does the company confirm the redemption of BO-P20 on 28 September, issue 01 on 30 October, BO-P13 on 24 January and the execution of the BO-P11 offer on 12 February in full?
- From what money will the January-February redemptions be paid: how many non-project credit lines have been signed and with which banks?
- Who holds the loans for the purchase of MIC (RUB 38.4bn) and land (RUB 65.5bn), and what will happen to them in a restructuring? Which RUB 3.0bn loan breached a covenant, and has a bank letter been received?
- Do the loan agreements contain cross-default with the bonds?
- Is the new shareholder Fonte Capital ready to contribute capital, and when is the shareholders' meeting?
- How much land is planned for sale in the second half, and do the pledgee banks agree?
- To whom were the related-party loans of RUB 13.5bn issued, for which a provision of RUB 2.8bn was created over the half-year?
Main risks
- A deal with Sber will lock the best projects to the bank, and the margin that would have gone to bondholders will go to the bank.
- Sales will not recover: the company, in the CFO's words, sees the guidance of 700-800 thousand sq. m as "very bad", and from 1 October, as analysts reminded on the call, differentiated rates on family mortgages are introduced.
- Covenants: long-term loans of RUB 396bn are under restrictive conditions, and one breach already exists.
- Late delivery of houses: the moratorium on penalties for developers was lifted from 1 January 2026.
- Panic among bondholders itself worsens the position: without new placements the company has nothing to refinance even small issues.
Conclusion: the fate of the bonds is decided in negotiations where holders have no seat
Samolet is still paying, and the market prices the two nearest issues at par. But according to the statements, the holding that issues the bonds depends on banks. It has no cash, corporate debt is twice the declared level, and cash EBITDA does not cover even half of accrued interest. The key question: will a deal with Sber be a relief for the whole group, or a way for the bank to take the best projects ahead of other creditors? The answer will come with the terms of the deal. The company speaks of constructive negotiations, the market over the week has priced in ever more risk, and only an official document can settle between them. Until then we are not putting new money into the company's bonds.
An extended card of Samolet with statements and multiples is available on our portal Frontier.
Sources
- IFRS of PAO GK Samolet for 6 months of 2026 and for 2025; PAO's RAS statements for 1H2026 (e-disclosure).
- Recording of the company's analyst call on 1H2026 results, 28.08.2026; conversation with the company's IR on 18.09.2026; company comments on the text of the review, 22-24.09.2026.
- MOEX ISS: issue parameters, coupon and offer schedules, prices.
- [Kommersant, 17.09.2026](https://www.kommersant.ru/doc/8956629); [Kommersant, bonds](https://www.kommersant.ru/doc/8957240); [Vedomosti](https://www.vedomosti.ru/investments/news/2026/09/17/1229698-obligatsii-samoleta); [RIA Real Estate](https://realty.ria.ru/20260917/samolet-2118306204.html); [Interfax on 1H2026 results](https://www.interfax.ru/business/1111802); [Interfax on state support](https://interfax.com/newsroom/top-stories/116237/); [Kommersant on the Fonte Capital deal](https://www.kommersant.ru/doc/8876403); [ACRA](https://www.acra-ratings.ru/press-releases/6448/); [Kommersant on the technical default](https://www.kommersant.ru/doc/8636934); [ABN on the Federal Tax Service petition, 15.09.2026](https://abn.agency/2026/09/15/fns-podala-zayavlenie-o-bankrotstve-zastrojshhika-vhodyashhego-v-strukturu-samoleta/).; [RIA Novosti on the Ministry of Finance position, 24.02.2026](https://realty.ria.ru/20260224/minfin-2076478593.html)
See also: market overview · valuation map · stock screeners