Segezha: lumber fell 8.7% in ruble terms, revenue held on volumes, but EBITDA stayed symbolic
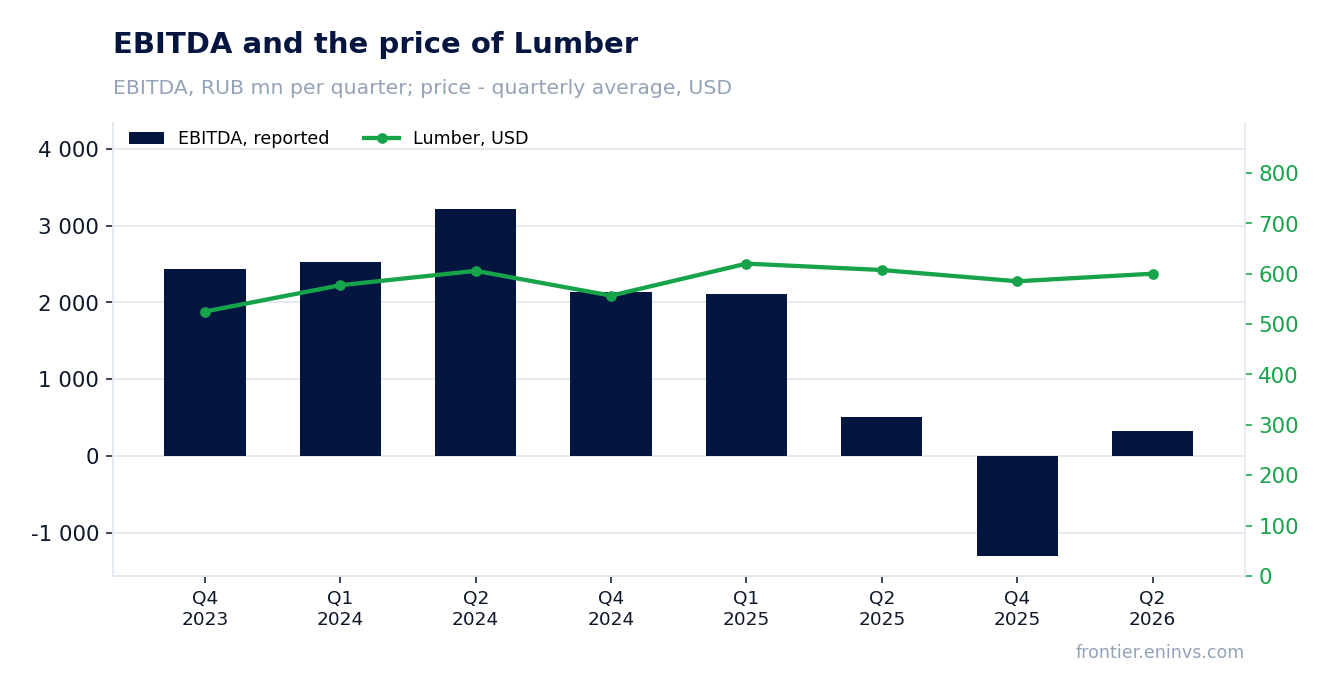
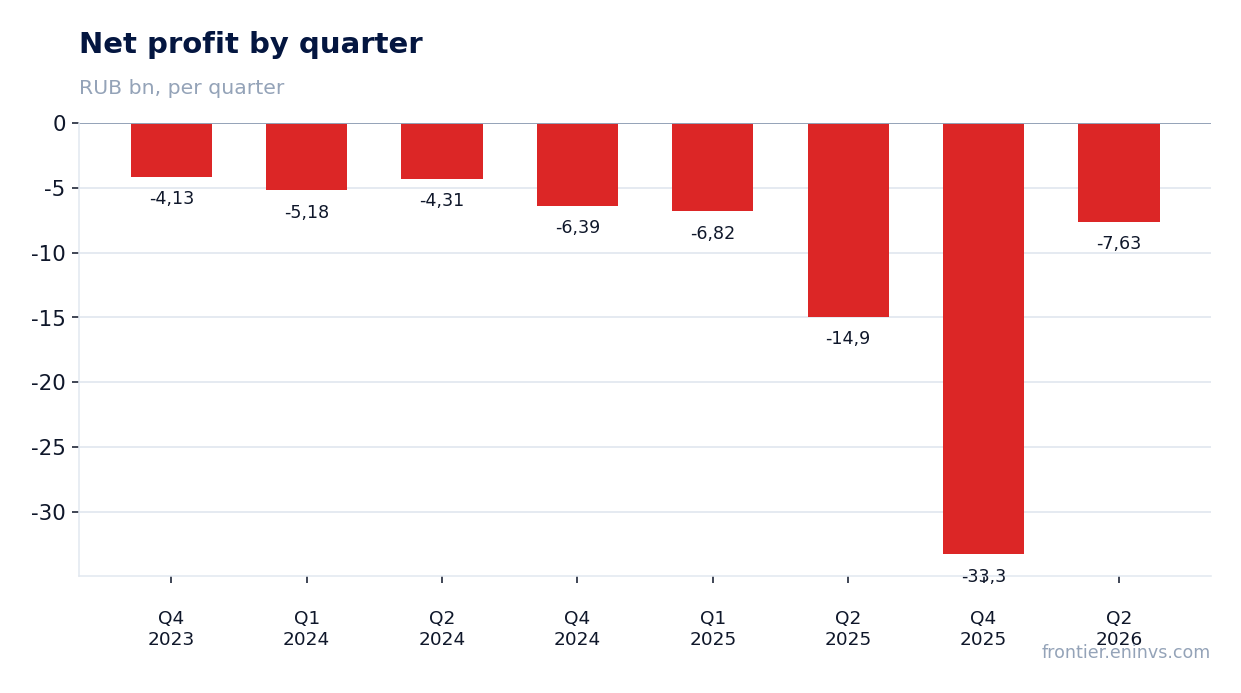
On 27 August Segezha reported Q2 2026 results: revenue RUB 20,547 mn (+1.4% YoY), EBITDA RUB 328.5 mn (–35.1%), net loss RUB 7,631.5 mn. The average lumber price was USD 600.1 versus USD 607.4 a year earlier, and at RUB 74.6/USD versus RUB 80.8/USD that is –8.7% in rubles. At year-ago volumes and costs, our calculation shows the price move would have produced EBITDA of minus RUB 576.4 mn; the company earned RUB 328.5 mn, a gap of RUB 904.9 mn explained by volumes and lower unit costs. With net debt of RUB 89.6 bn and negative operating cash flow of RUB 4,278.5 mn for the quarter, the share looks unattractive.
Key takeaways
— Lumber fell 8.7% in rubles and containerboard 5.6%, capping revenue
— At year-ago prices our calculation gives EBITDA of minus RUB 576.4 mn; the company earned RUB 328.5 mn on volumes and costs
— Revenue held at RUB 20,547 mn only because volumes grew while the dollar price slipped just 1.2%
— EBITDA of RUB 328.5 mn at a 1.6% margin does not cover interest, and operating cash flow for the quarter was negative at RUB 4,278.5 mn
— The RUB 7,631.5 mn net loss is almost entirely interest and revaluation, not operations
— Net debt rose from RUB 78.8 bn at end-2025 to RUB 89.6 bn on 30 June 2026, and there is no cash to service it
— No dividends were paid over the last 12 months, and with losses and negative free cash flow none should be expected
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
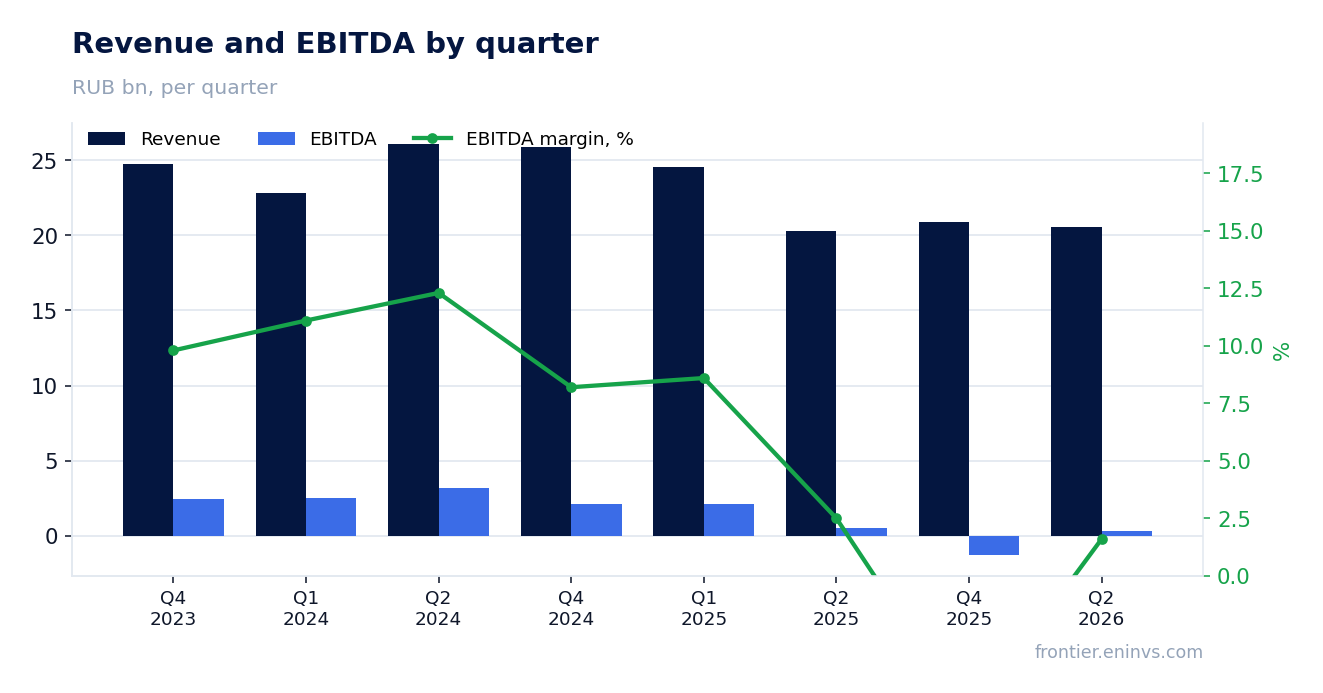
| Revenue | 20.3 | 20.5 | +1.4% |
| EBITDA | 0.51 | 0.33 | -35.1% |
| Operating profit | -3.23 | -2.66 | — |
| Net profit | -14.9 | -7.63 | — |
| Operating cash flow | -15.1 | -4.28 | — |
| Capex | 1.58 | — | — |
| EBITDA margin | 2.5% | 1.6% | -0.9 pp |
| Net margin | -73.7% | -37.1% | +36.6 pp |
Lumber fell 8.7% in rubles and containerboard 5.6%, capping revenue
The average lumber price in the reported period was USD 600.1 versus USD 607.4 a year earlier, down 1.2%. But the ruble strengthened from RUB 80.8 to RUB 74.6 per dollar, so in the reporting currency the price fell 8.7%. For a company that sells lumber for foreign currency and bears costs in rubles, this is a double blow: dollar revenue converts at a lower rate.
Containerboard (fluting B1) fell from RUB 58,754 to RUB 55,443 per tonne, down 5.6%. Quarter on quarter the price was flat at RUB 55,434, suggesting a bottom for this product, but it is still far below last year's level.
Spot is lower now: lumber stands at USD 516.5 on 5 November 2026, 13.9% below the reported-period average. Containerboard holds at RUB 55,466, essentially at the reported-period level. This means next quarter's dollar lumber revenue will be weaker still if the exchange rate does not change.
Commodity prices: period average and now
| Benchmark | Year ago | Q2 2026 | YoY | Spot 2026-11-05 |
|---|---|---|---|---|
| Lumber, USD | 607,4 | 600,1 | -1,2% | 516,5 |
| Containerboards. Fluting cellulose B1, RUB | 58 754 | 55 443 | -5,6% | 55 466 |
At year-ago prices our calculation gives EBITDA of minus RUB 576.4 mn; the company earned RUB 328.5 mn on volumes and costs
Taking Q2 2025 volumes and non-commodity costs and substituting only current lumber and containerboard prices, revenue would have been RUB 19,185.6 mn and EBITDA minus RUB 576.4 mn. In fact the company reported revenue of RUB 20,547 mn and EBITDA of RUB 328.5 mn, better than the calculation by RUB 1,361.4 mn and RUB 904.9 mn respectively.
The gap has two causes. First, volumes: revenue is 7.1% above the calculation even though ruble prices fell, meaning the company sold more product. Second, lower costs: cost of goods sold for the half-year fell from RUB 36,629 to RUB 31,825 mn, and selling and administrative expenses from RUB 14,545 to RUB 11,574 mn. This kept EBITDA positive even as prices fell.
The report does not disclose production and sales volumes in physical terms, so we cannot break the gap down more precisely. But the fact that the company earned more than prices allowed suggests operating efficiency improved, or that last year's costs were inflated.
What the prices implied and what the company earned
| Base (Q2 2025) | Implied at period prices | Reported | Reported vs implied | |
|---|---|---|---|---|
| Revenue, RUB mn | 20 268 | 19 186 | 20 547 | +7,1% |
| EBITDA, RUB mn | 506,0 | -576,4 | 328,5 | — |
Revenue held at RUB 20,547 mn only because volumes grew while the dollar price slipped just 1.2%
Q2 2026 revenue was RUB 20,547 mn, up 1.4% year on year. That is modest growth, but against a fall in ruble prices of 8.7% for lumber and 5.6% for containerboard it looks better than it could have. Volumes supported it: the company sold more product than a year earlier.
Segment reporting for the half-year shows Paper and packaging revenue fell from RUB 17,424 to RUB 14,518 mn, Wood working from RUB 18,820 to RUB 15,895 mn, and Plywood, boards and laminated products from RUB 6,465 to RUB 6,196 mn. All three segments declined, and the second-quarter revenue growth does not offset the overall half-year fall.
The ruble worked against the company: strengthening from RUB 80.8 to RUB 74.6 per dollar reduced ruble revenue from exports. Had the rate stayed at last year's level, revenue would have been higher. But the company does not disclose the export share, so we cannot quantify the effect.
EBITDA of RUB 328.5 mn at a 1.6% margin does not cover interest, and operating cash flow for the quarter was negative at RUB 4,278.5 mn
Q2 2026 EBITDA was RUB 328.5 mn versus RUB 506 mn a year earlier, down 35.1%. The margin compressed from 2.5% to 1.6%. That means for every ruble of revenue the company earns one and a half kopecks of operating profit before depreciation, an amount that does not even cover interest expense.
Interest expense for the half-year was RUB 10,761 mn, including RUB 6,329 mn on loans and borrowings and RUB 2,950 mn on option agreement liabilities. That is several times the entire quarterly EBITDA. Operating profit is negative at minus RUB 2,657 mn, and adding back depreciation of RUB 2,985.5 mn brings EBITDA to a small positive.
Operating cash flow for the quarter was negative at minus RUB 4,278.5 mn. For the half-year it was minus RUB 8,557 mn. The company spends cash servicing debt and replenishing working capital, and even positive EBITDA does not turn into cash.
The RUB 7,631.5 mn net loss is almost entirely interest and revaluation, not operations
Q2 2026 net loss was RUB 7,631.5 mn versus RUB 14,946 mn a year earlier. The near-halving of the loss is not due to better operations but to lower interest expense after the debt restructuring and the additional share issue in 2025.
For the half-year, loss before tax was RUB 16,715 mn, including interest expense of RUB 10,761 mn and negative foreign exchange differences of RUB 384 mn. The tax effect returned RUB 1,452 mn, leaving a net loss of RUB 15,263 mn. The operating part of the loss was RUB 5,314 mn; the rest is financial items.
The H1 2025 report contained one-off charges of RUB 5,574 mn: impairment of non-current and current assets on the reorganisation of the Wood working segment. There were no such charges in 2026, which also flatters the comparison. But even without one-offs the loss remains significant.
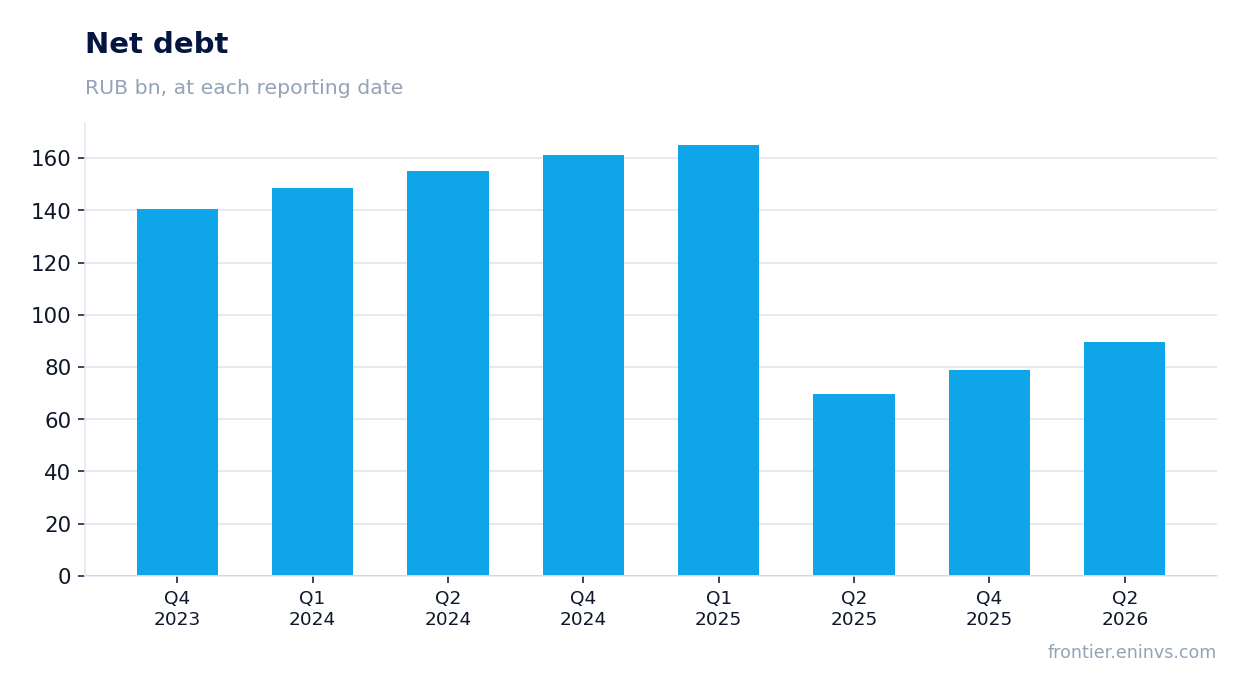
Net debt rose from RUB 78.8 bn at end-2025 to RUB 89.6 bn on 30 June 2026, and there is no cash to service it
Net debt on 30 June 2026 was RUB 89.6 bn versus RUB 78.8 bn at end-2025, an increase of RUB 10.8 bn over six months. A year earlier, on 30 June 2025, debt was RUB 69.8 bn, so over 12 months it rose by RUB 19.8 bn. Rising debt with negative operating cash flow means the company is funding current operations and interest with new borrowings.
In the debt structure on 30 June 2026, short-term loans and borrowings are RUB 51,212 mn and long-term RUB 27,240 mn. Most of the debt is short-term and must be refinanced or repaid in the coming months. Cash on hand is only RUB 1,415 mn.
The company also has liabilities under option agreements of RUB 32,089 mn, recognised within current liabilities. Covenants on these have been breached, but investors have not yet demanded execution. If they do, the debt burden will grow further.
No dividends were paid over the last 12 months, and with losses and negative free cash flow none should be expected
Over the last 12 months the company paid no dividends. The last payment was in 2022: RUB 1.06 per share at an ex-date price of RUB 8.8, a yield of 12%. Since then the company has been loss-making and has made no payments.
Our estimate for the current year's dividend is RUB 0 per share. This follows from the portal's canonical model: the profit base is negative (minus RUB 81,876 mn), free cash flow is also negative, and the payout is capped at zero. The model uses a payout ratio of 1.0 of profit, but with a loss it does not apply.
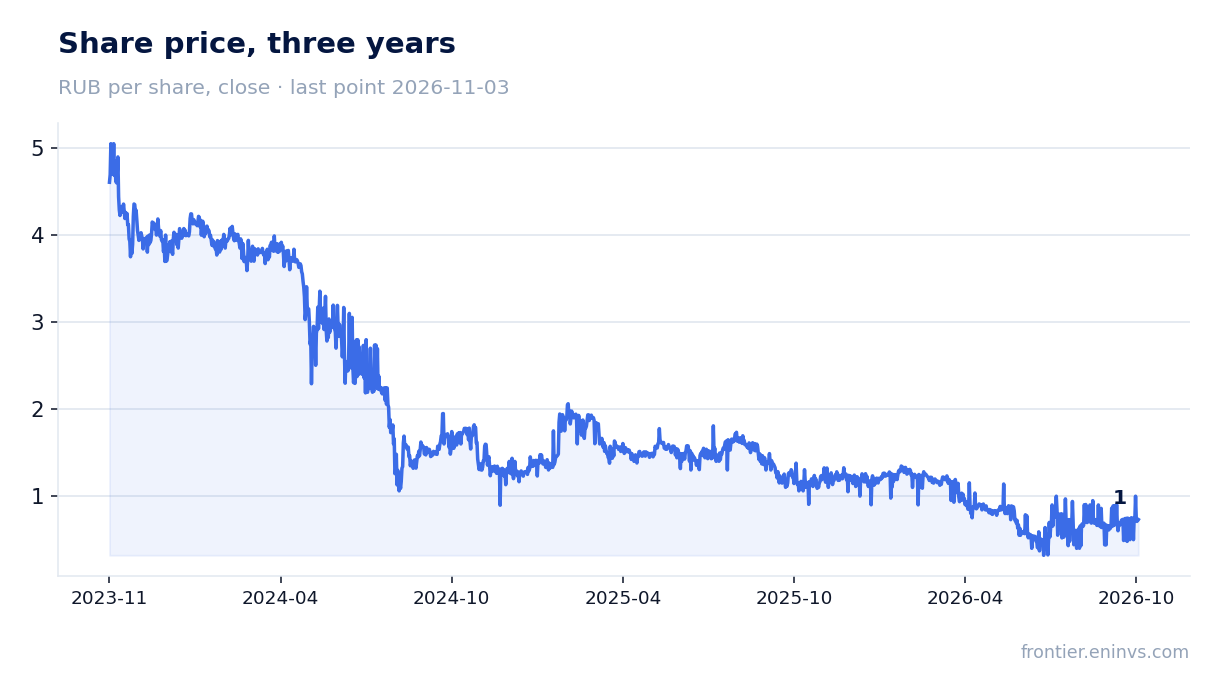
The yield at the current price of RUB 0.77 is zero. For comparison, the central bank key rate is 14%, and the yield we consider fair for this name is 12%. So the share offers neither dividend income nor growth that would compensate for the absence of payouts. Until the company turns profitable and starts generating free cash flow, there will be no dividends.
On the portal's model the share is 90% below fair value, but that is a floor, not a target
Our spot model re-prices EBITDA at current commodity prices and the target EV/EBITDA multiple. At current prices annual EBITDA is minus RUB 42,461 mn versus LTM EBITDA of minus RUB 32,512 mn, meaning at today's prices the company generates even less operating profit than the trailing twelve-month average.
The model shows upside to fair value of minus 90%, but this value sits on the model's clamp, so it should be read as a floor, not an estimate. In other words, even at current prices the share looks overvalued relative to what the company earns.
We cannot compare the multiple with its three-year history: the FACTS contain neither the current EV/EBITDA nor a three-year average. But with negative EBITDA the multiple loses meaning – the company does not earn, and cannot be valued on profit.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 60.4 bn ₽ |
| Operating cash flow (LTM) | -16.0 bn |
| ROE | 203.4% |
Bottom line
The strong point of the report is that the company earned EBITDA of RUB 328.5 mn where prices allowed minus RUB 576.4 mn, thanks to volumes and lower costs. But that EBITDA at a 1.6% margin does not cover interest expense, and operating cash flow is negative. Debt has risen to RUB 89.6 bn, there are no dividends, and at current lumber prices the company will generate even less. The question for a holder now is not when prices will recover, but whether the company has enough liquidity to survive until they do. Verdict: unattractive.
Open the company's financial profile SGZH →
See also: market overview · valuation map · stock screeners