Tatneft, 1H2026: dividend of RUB 32.88 (5.9%) - exactly 50% of RAS profit, although IFRS gives RUB 35.51
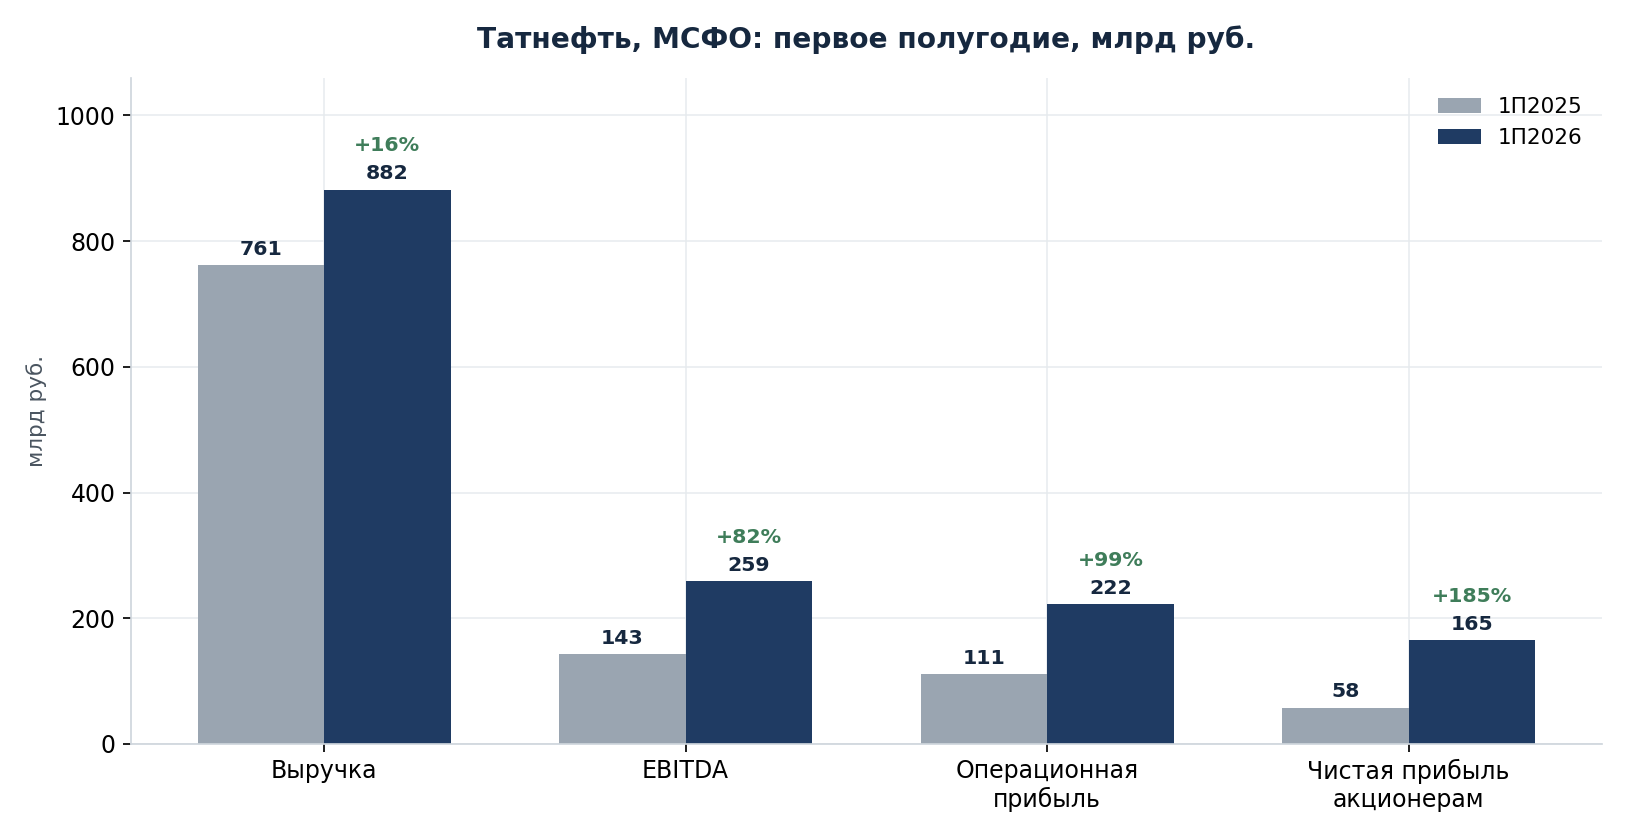
On 26 August Tatneft published its consolidated condensed interim IFRS statements for the six months of 2026. Revenue was RUB 881.6 bn (plus 15.8%), EBITDA RUB 259.2 bn (plus 82%), and net income attributable to shareholders RUB 165.2 bn - growth of 2.8 times. The next day the ordinary share gained 5.0% against a plus of 1.1% in the MOEX index.
The half-year is strong in both segments, but the main story is not profit. The board of directors recommended RUB 32.88 per share - exactly 50% of the parent company's RAS net profit and 5.9% of the ordinary share price for a single half-year - whereas the same formula on IFRS would have given RUB 35.51, or 6.4%.
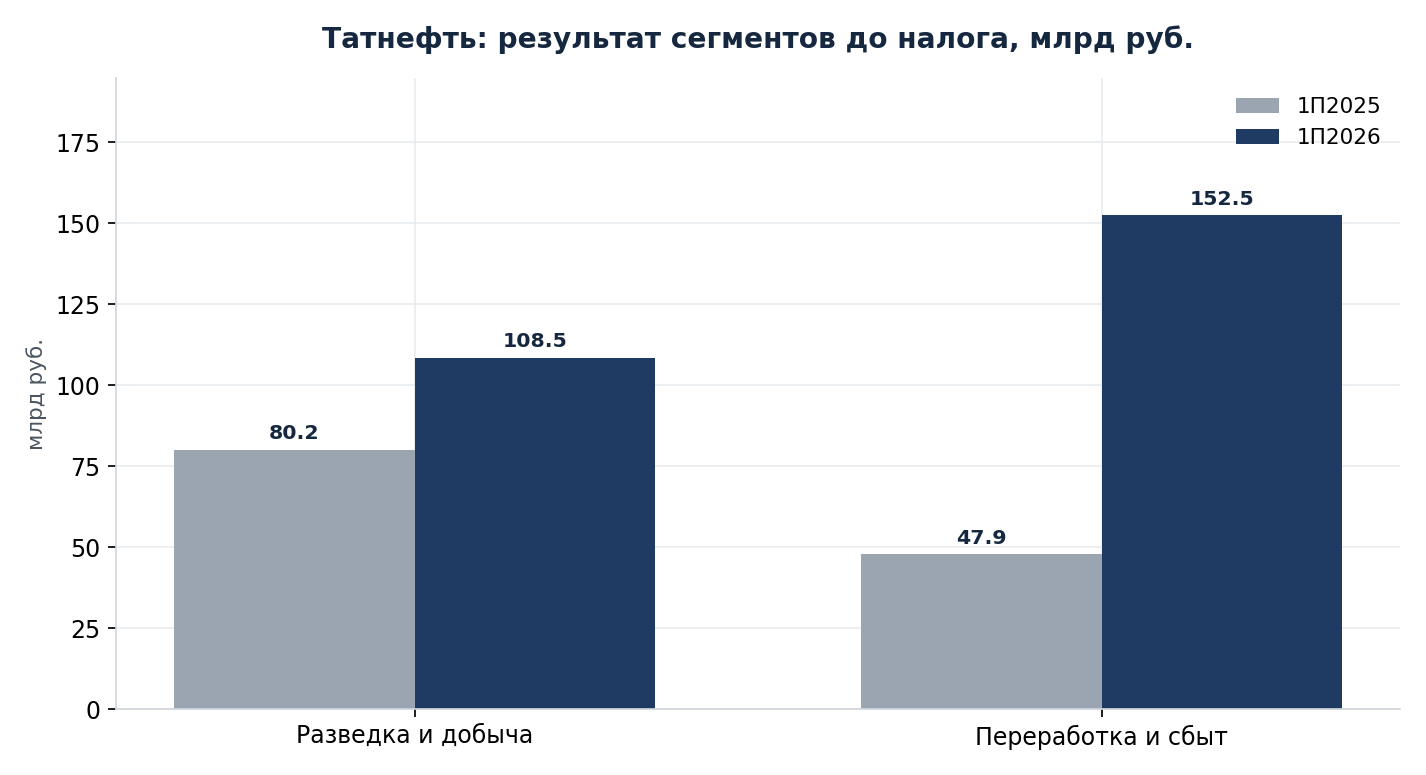
- Refining grew threefold and became the group's main profit centre. Segment result of RUB 152.5 bn against RUB 47.9 bn a year ago.
- Cost of sales under RAS rose 0.2% while revenue rose 21%. The entire difference went into gross profit, which doubled.
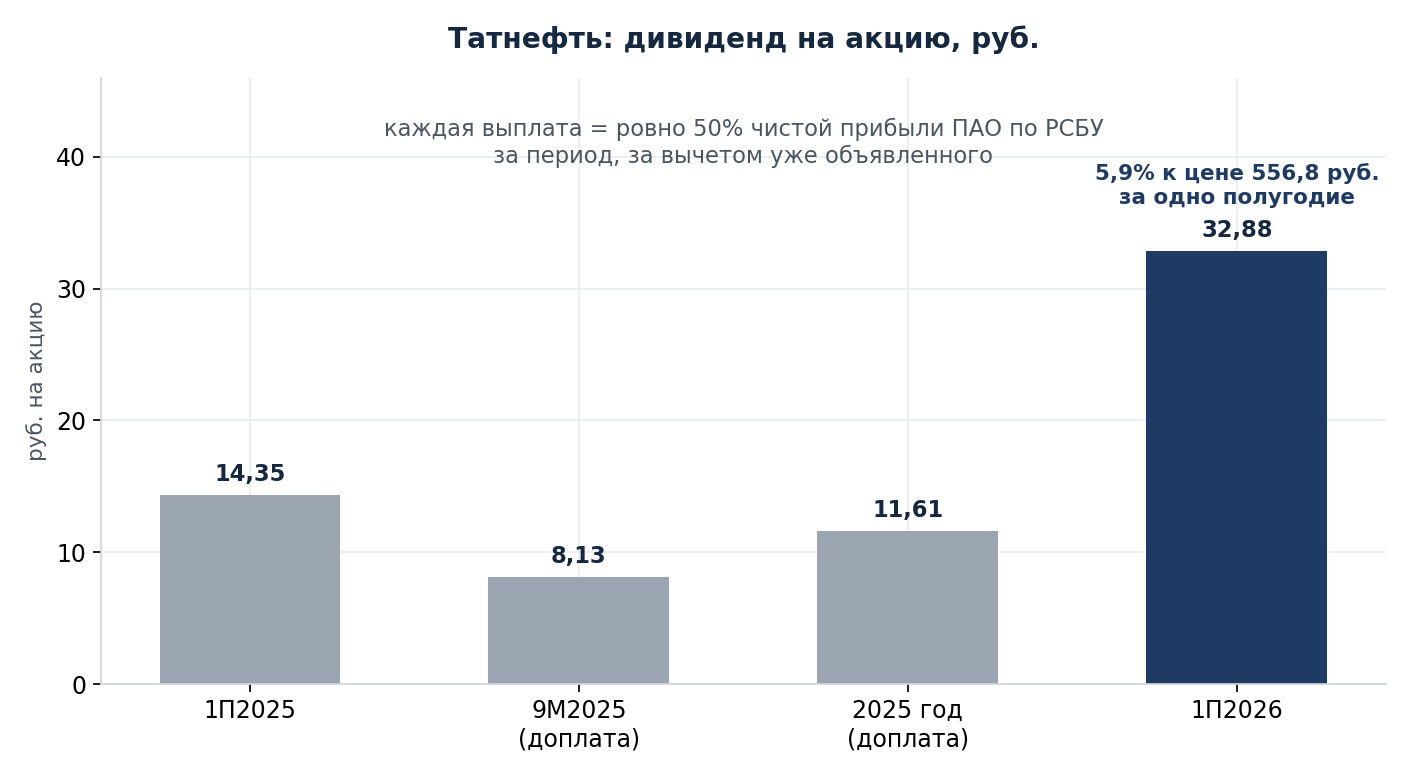
- The dividend of RUB 32.88 is exactly 50% of the parent's RAS net profit and 5.9% of the price. The rule has held for four payments in a row, to the kopeck.
- On IFRS the same half would have given RUB 35.51, or 6.4%. The board met on 19 August, a week before the IFRS statements were signed.
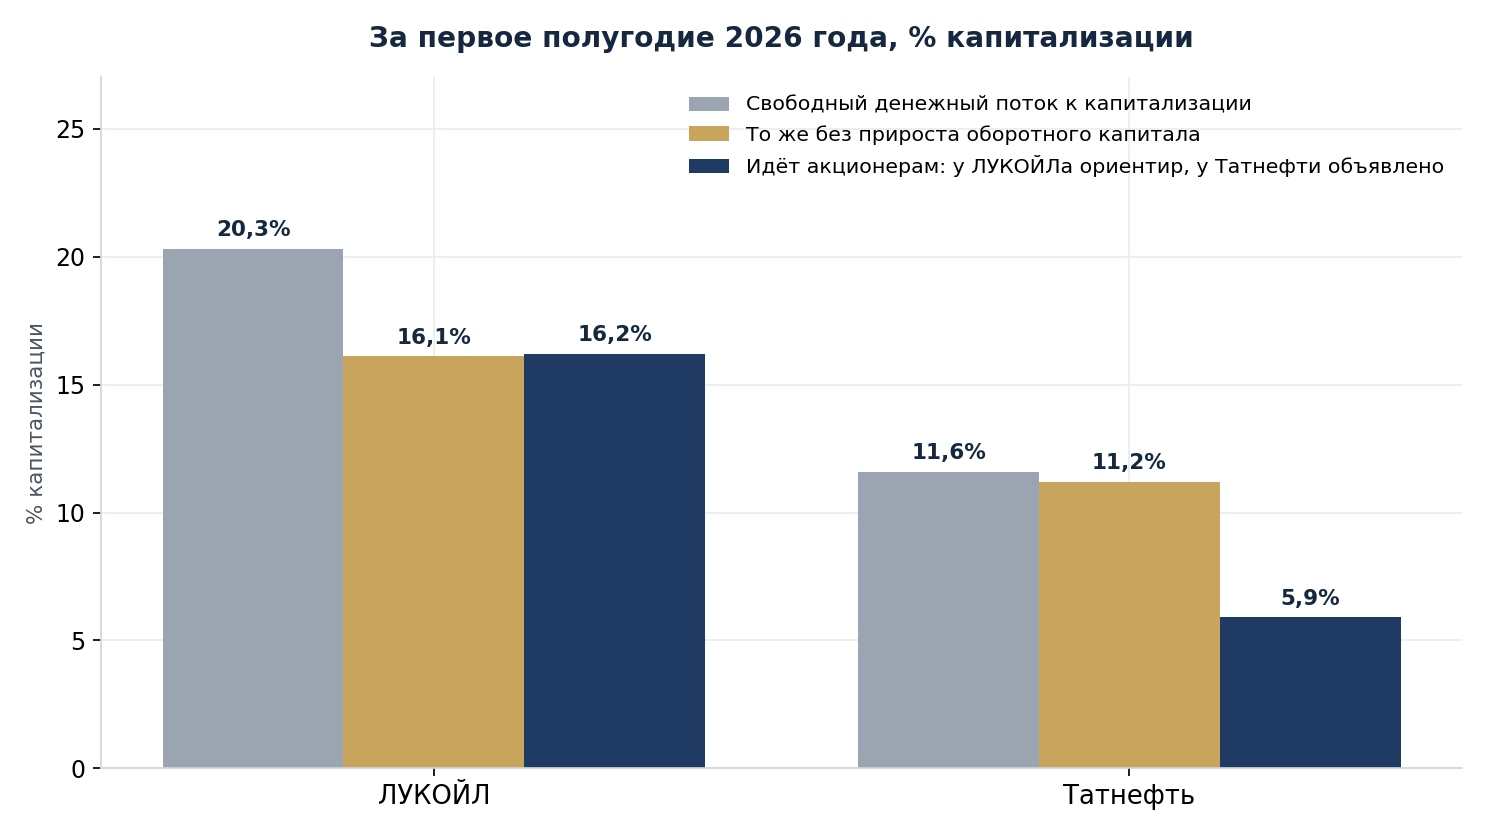
- Free cash flow is twice the payout: 11.6% of capitalisation against a 5.9% dividend. The other half stays in the company - cash and deposits rose from RUB 88 bn to RUB 276 bn.
- The 23 September meeting cannot raise the amount. The Joint-Stock Companies Law prohibits approving a dividend larger than the one recommended by the board.
- RUB 51.5 bn quietly left equity. The tyre business was sold to a Tatarstan-controlled entity for RUB 27.9 bn against a net asset carrying value of RUB 93.1 bn, and the loss was recorded directly in equity, bypassing the income statement.
- The company has practically no debt: RUB 144.2 bn of cash against RUB 14.5 bn of loans, borrowings and leases.
- Record date is 13 October, the last day to buy is 12 October. The yield is 5.9% on the ordinary share and 6.1% on the preferred share.
Revenue plus 16%, EBITDA plus 82%: refining grew threefold
Sales revenue excluding financial services was RUB 881.6 bn against RUB 761.2 bn. Operating profit excluding financial services was RUB 222.0 bn against RUB 111.3 bn. EBITDA, i.e. operating profit plus depreciation, depletion and amortisation, was RUB 259.2 bn against RUB 142.6 bn; the margin was 29.4% against 18.7%.
Segment result before tax: exploration and production RUB 108.5 bn against RUB 80.2 bn (plus 35%); refining and marketing of oil and petroleum products RUB 152.5 bn against RUB 47.9 bn - growth of 3.2 times. Financial services turned positive: RUB 0.7 bn against minus RUB 0.2 bn.
Revenue from petroleum products was RUB 504.0 bn against RUB 450.7 bn, from own crude oil RUB 310.0 bn against RUB 257.6 bn. Exports of crude oil and petroleum products to near and far abroad were RUB 338.2 bn against RUB 256.7 bn, plus 32%. And this despite the fact that the Bank of Russia's average dollar rate for the half-year was RUB 76.29 against RUB 86.58 a year earlier: the rouble strengthened by 12%.
Cost of sales under RAS did not grow at all: the entire revenue gain became gross profit
The parent company's RAS statements, on which the dividend is calculated, show the mechanics even more clearly. Revenue was RUB 814.1 bn against RUB 674.1 bn, plus 20.8%. Cost of sales was RUB 532.9 bn against RUB 531.9 bn, plus 0.2%. Gross profit doubled: RUB 281.2 bn against RUB 142.2 bn. Profit from sales was RUB 230.6 bn against RUB 86.0 bn.
It is important that the gain was not created by subsidiaries' dividends: income from participation in other organisations, on the contrary, fell from RUB 33.3 bn to RUB 21.3 bn. The parent's net profit was RUB 152.98 bn against RUB 66.76 bn, growth of 2.3 times.
The tax burden fell: additional income tax down 17%, reverse excise up 12%
Taxes other than income tax were RUB 249.2 bn against RUB 263.6 bn, minus 5.5% while revenue rose. Mineral extraction tax rose from RUB 226.7 bn to RUB 238.0 bn, while additional income tax on hydrocarbon extraction fell from RUB 74.6 bn to RUB 62.0 bn. Excise as a whole is negative: minus RUB 62.0 bn against minus RUB 47.0 bn, including reverse excise of minus RUB 117.6 bn against minus RUB 105.2 bn.
So the damper component added about RUB 12.5 bn and, together with the decline in additional income tax, produced RUB 25 bn of tax savings - while mineral extraction tax rose by RUB 11.3 bn.
The dividend of RUB 32.88 is exactly 50% of RAS net profit, and the rule holds to the kopeck
The board of directors recommended that the extraordinary general meeting set the dividend for the six months of 2026 at 32 roubles 88 kopecks per ordinary and per preferred share (minutes of the absentee meeting of 19 August, disclosed on 20 August).
The arithmetic matches exactly. The parent's RAS net profit for the half-year is RUB 152,978 mn, half of which is RUB 76,489 mn. Total shares are 2,178,690,700 ordinary and 147,508,500 preferred, together 2,326,199,200. Dividing gives RUB 32.88. Treasury shares are not excluded from the base. For 2025 the company itself discloses an accrual of RUB 74,271 mn on ordinary and RUB 5,029 mn on preferred shares, which corresponds exactly to RUB 34.09 on the whole issue.
The same check on the three previous payments:
- for 1H2025: RAS profit RUB 66,760 mn, half on all shares - RUB 14.35. That is what was paid, record date 13 October 2025.
- for 9M2025: profit RUB 104,596 mn, half - RUB 22.48 cumulatively; the top-up to the RUB 14.35 already declared is RUB 8.13. That is what was paid, record date 8 January 2026.
- for 2025, a total of RUB 34.09 was declared, i.e. the parent's annual RAS profit was about RUB 158.6 bn; the final top-up is RUB 11.61, record date 14 July 2026.
On IFRS the same formula would have given RUB 35.51, and this is not nitpicking
Tatneft's dividend policy is worded as follows: the board of directors bases its decision on net profit under RAS or IFRS depending on the availability of published statements for the period, and targets at least 50% of net profit under RAS or IFRS - whichever is greater.
In 1H2026 IFRS turned out to be greater: profit attributable to shareholders was RUB 165,231 mn against RUB 152,978 mn under RAS. Half of the IFRS figure on all shares is RUB 35.51, 8% above the recommendation. In yield terms the difference is 6.4% against 5.9% on the ordinary share and 6.6% against 6.1% on the preferred share.
The explanation follows directly from the policy wording: on 19 August, when the board made its decision, there were no IFRS statements yet - the auditor signed the review conclusion on 26 August. The board used the only statements published at that moment.
The practical conclusion. Article 42, paragraph 3 of the Joint-Stock Companies Law does not allow the meeting to approve a dividend larger than the one recommended by the board, so RUB 32.88 is the ceiling for this payment. The difference of about RUB 2.6 per share, or RUB 6 bn on the whole issue, can be made up in subsequent payments, where the nine-month and full-year base is calculated cumulatively less what has already been declared.
The sale of the tyre business cost shareholders RUB 51.5 bn outside the income statement
In 1Q2026 the group sold all shares and interests in subsidiaries of the tyre segment and in a number of other companies - mainly to an entity controlled by the Republic of Tatarstan. The fair value of the consideration, determined from the discounted cash flows of the sale contracts, is RUB 27,944 mn. The carrying value of the net assets disposed of is RUB 93,086 mn.
The total loss on disposal is RUB 47,481 mn. It is split as follows: RUB 3,997 mn passed through the income statement as profit from discontinued operations (thanks to a recognised income tax benefit of RUB 11,153 mn and the recycling of accumulated other comprehensive income of RUB 6,508 mn), and RUB 51,478 mn was recorded directly in the statement of changes in equity, in a line for the effect of disposal of subsidiaries in a transaction with a shareholder.
In other words, in the income statement the deal looks like a small gain, but in fact it reduced shareholders' equity by RUB 51.5 bn - about RUB 22 per share. This loss did not affect the dividend base under either RAS or IFRS.
A debt-free balance sheet: RUB 144 bn of cash against RUB 14.5 bn of liabilities
Cash rose from RUB 66.9 bn to RUB 144.2 bn. Short-term loans and borrowings including the current portion are RUB 10.1 bn, long-term ones RUB 0.7 bn, and lease liabilities net of the current portion RUB 3.7 bn. In total RUB 14.5 bn, with a net cash position of RUB 130 bn. In addition, the non-reportable segments hold RUB 131.5 bn of bank deposits against RUB 21.3 bn at the end of 2025. Customer funds of the banking subsidiary (RUB 200.6 bn) are not corporate debt and are not counted.
Operating cash flow doubled: RUB 207.9 bn against RUB 104.7 bn. Capital expenditure (property, plant and equipment plus intangible assets) fell from RUB 67.8 bn to RUB 62.5 bn. Free cash flow was RUB 145.5 bn against RUB 36.9 bn. Shareholders' equity is RUB 1,401.7 bn.
Dividends paid in the half-year totalled only RUB 26.3 bn against RUB 132.3 bn a year earlier, but this is a matter of the calendar, not of policy: the final payment for 2025 passed its record date on 14 July 2026 and fell into the third quarter.
Calendar: record list on 30 August, meeting on 23 September, record date 13 October
The date for determining persons entitled to take part in the extraordinary absentee vote is 30 August 2026. The vote itself is on 23 September, with a repeat on 30 September if there is no quorum. The date for determining persons entitled to receive dividends is 13 October 2026, a Tuesday. Under T+1 settlement the last day to buy with the dividend is 12 October, a Monday.
The same meeting will consider new versions of the charter and of the regulations on the board of directors, the management board, the general director and the audit commission.
Valuation: 2.2x EV/EBITDA and 3.8x P/E; if the pace holds, the year gives RUB 66-71 of dividends, or 11.8-12.8%
At prices of RUB 556.8 for the ordinary and RUB 539.6 for the preferred share (29 August, 16:00 MSK), and taking into account 75.6 mn treasury ordinary shares held by subsidiaries, capitalisation of shares outstanding is RUB 1,251 bn. Including the net cash position, enterprise value is RUB 1,121 bn.
Doubled half-year EBITDA is RUB 518 bn, giving EV/EBITDA of 2.2x. Earnings per share for the half-year are RUB 73.42, RUB 146.8 annualised, giving a P/E on the ordinary share of 3.8x. The trailing dividend yield by record dates over the last twelve months is 6.1% (RUB 34.09).
The half-year dividend base in percent: the declared RUB 76.5 bn is 5.9% of capitalisation for six months. Half-year free cash flow of RUB 145.5 bn is 11.6% of capitalisation (11.2% excluding working-capital growth), i.e. the payout is covered almost twice by cash flow, and the other half stays in the company: cash rose from RUB 66.9 bn to RUB 144.2 bn, and bank deposits from RUB 21.3 bn to RUB 131.5 bn.
For comparison, at LUKOIL free cash flow for the same half-year is 20.3% of capitalisation (16.1% excluding working-capital growth), and practically all of it is distributed. Hence the yield gap of almost three times against a cash flow gap of less than one and a half times: it is about dividend policy, not about the quality of the business.
A mechanical scenario for the year. If 2H repeats 1H, the parent's RAS profit for 2026 will be about RUB 306 bn, and 50% would give about RUB 65.8 of dividends for the year - 11.8% on the ordinary and 12.2% on the preferred share. On IFRS it would be about RUB 71, i.e. 12.8% and 13.2%. This is extrapolation arithmetic, not a forecast, and should be treated accordingly: the refining result grew threefold year on year, such half-years do not repeat on schedule, and the company itself, in the note on the economic environment, writes about high volatility of oil and petroleum product prices in 2026. The actual yield over the last twelve months by record dates is 6.1%, and it is that, not 12%, that the price is currently discounting.
What to keep in mind
In December 2025 the United Kingdom imposed sanctions on PJSC Tatneft - the company itself states this in the note on the economic environment. The Government of the Republic of Tatarstan controls about 36% of the voting shares and holds the golden share. The tyre business deal shows what the redistribution of assets within this perimeter looks like: the price is about a third of the net assets' carrying value, and the loss bypasses the income statement.
Conclusion
The report is strong. Refining grew threefold, cost of sales did not rise at all, the company has no debt and operating cash flow has doubled. The dividend of RUB 32.88 with a record date of 13 October gives 5.9% on the ordinary and 6.1% on the preferred share for a single half-year; if the half-year repeats, the year comes to 11.8-12.2%, and on an IFRS-based calculation to 12.8-13.2%. The formal shortfall against IFRS is about RUB 2.6 per share, or 0.5 percentage points of yield, and it can be made up in subsequent payments. The main question for the company now is not the reporting, but the prices at which assets pass to related parties.
Extended issuer cards and the history of financial indicators are on our portal: frontier.eninvs.com. Related review: LUKOIL.
See also: market overview · valuation map · stock screeners