BlackRock: profit up a quarter, but $564 million of costs came from share-price revaluation, not the business
Contents
On October 14, BlackRock reported third-quarter 2026 results. Revenue reached $7,752 million (+19.1% year-on-year), net income – $1,659 million (+25.4%), and GAAP operating margin held at 30.0%. Growth decelerated from the second quarter (+30.6%), while $564 million of costs came not from operations but from the revaluation of contingent consideration on the GIP and HPS deals. At the current price the share looks rather attractive: the business delivers steady organic growth, and one-off items distort the picture in both directions.
Key takeaways
— Revenue grew 19.1% but decelerated from 30.6% in the second quarter
— Operating margin held at 30.0%, while adjusted margin reached 47.8%
— Net income added 25.4%, but $564 million of costs came from contingent consideration revaluation
— Net inflows reached $205 billion, of which $135 billion went into iShares
— Aladdin technology revenue grew 14% and drives 12% ACV growth
— Return on equity of 13.4% with no dividend history in the facts
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 6.51 | 7.75 | +19.1% |
| EBITDA | 2.30 | — | — |
| Operating profit | 1.96 | 2.33 | +19.1% |
| Net profit | 1.32 | 1.66 | +25.4% |
| Operating cash flow | 1.41 | — | — |
| Capex | 0.08 | — | — |
| EBITDA margin | 35.4% | — | — |
| Net margin | 20.3% | 21.4% | +1.1 pp |
Revenue grew 19.1% but decelerated from 30.6% in the second quarter
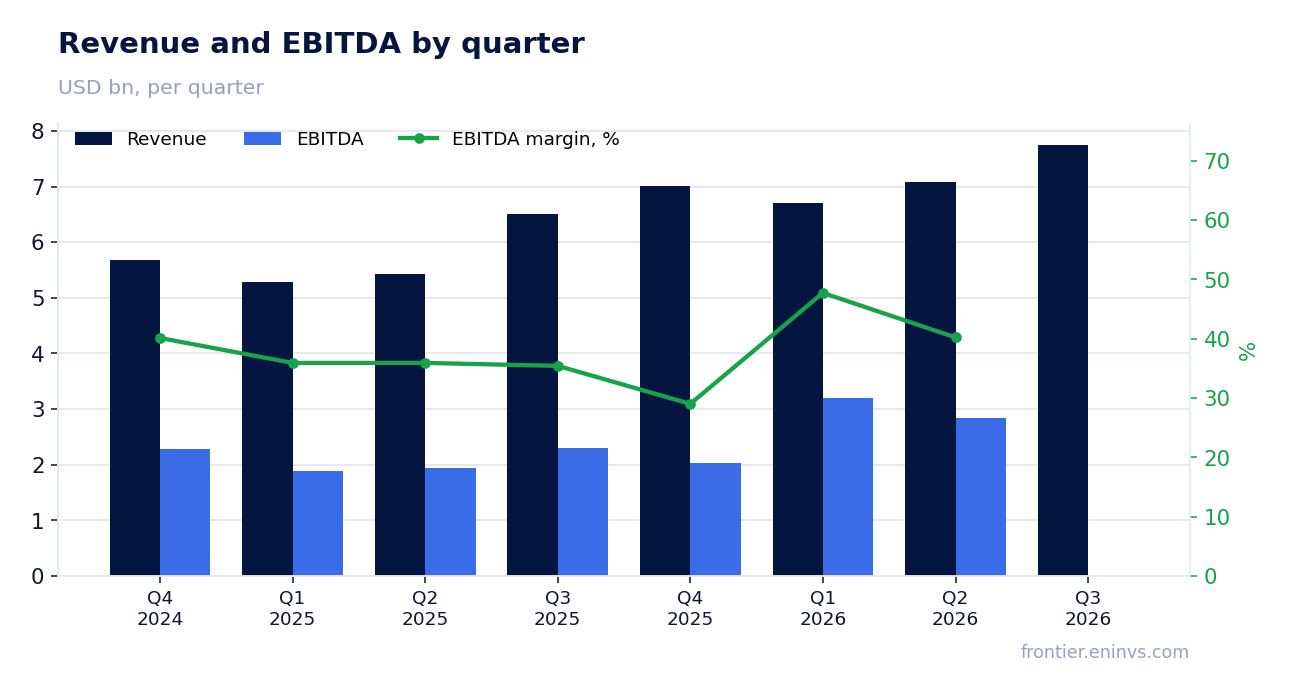
In the third quarter of 2026, BlackRock's revenue reached $7,752 million, up 19.1% year-on-year. That is noticeably slower than 30.6% in the second quarter and 27.0% in the first. The deceleration is primarily a base effect: a year earlier revenue had already jumped 25.2%, making the comparison tougher.
The main contribution came from investment advisory and administration fees – $5,783 million versus $4,843 million a year earlier. Securities lending revenue rose to $253 million from $203 million, which the company attributes to higher spreads and average balances of securities on loan. Technology services and subscription revenue added $73 million, to $588 million, on demand for Aladdin.
Structurally, revenue is becoming more diversified: the share of technology services and subscriptions is growing, while management fees remain the core. This matters because the technology segment is less volatile and not directly tied to market indices.
Operating margin held at 30.0%, while adjusted margin reached 47.8%
GAAP operating margin in the third quarter of 2026 was 30.0% – exactly the same as a year earlier. This means that 19.1% revenue growth was accompanied by proportional cost growth. Operating income rose 19%, to $2,328 million.
Adjusted operating margin, which the company considers more representative, reached 47.8% versus 44.6% a year earlier. The 320 basis point increase reflects operating leverage and growth in high-margin technology revenue. Adjusted operating income rose 27%, to $3,330 million.
The gap between GAAP and adjusted margin is explained by one-off items: contingent consideration revaluation ($564 million), amortisation of intangibles ($276 million) and compensation expenses. Without them, the business looks significantly more profitable than GAAP reporting shows.
Net income added 25.4%, but $564 million of costs came from contingent consideration revaluation
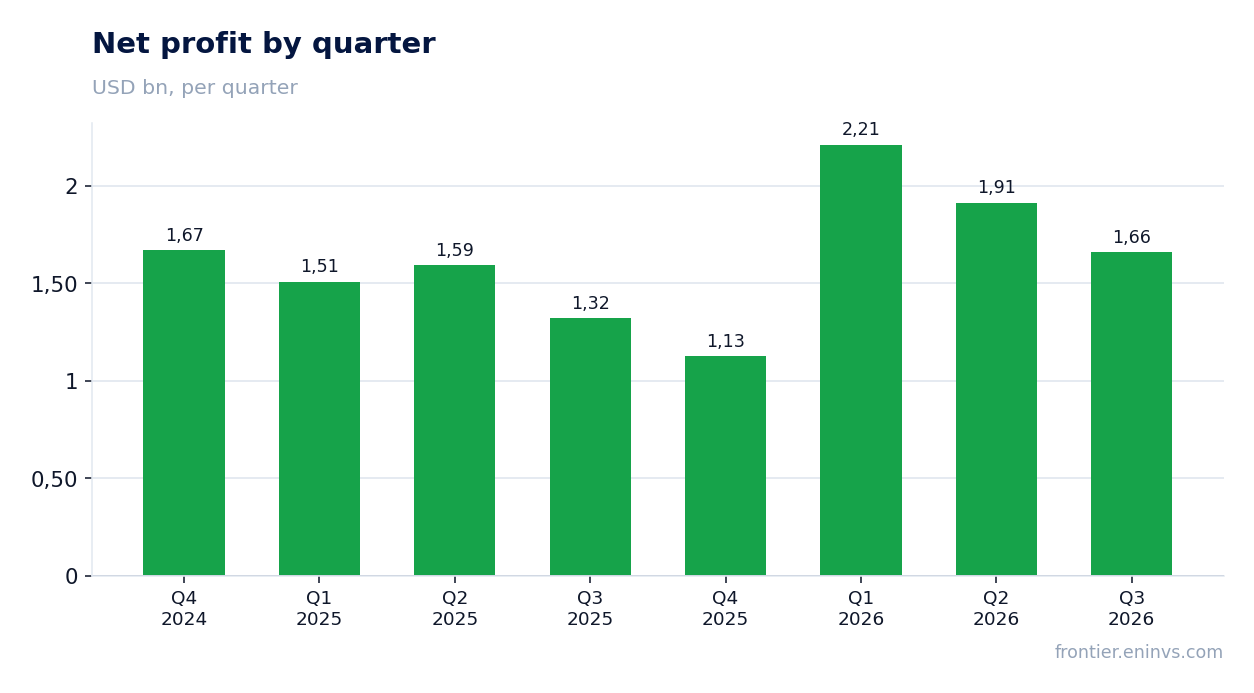
Net income attributable to BlackRock in the third quarter of 2026 was $1,659 million, up 25.4% year-on-year. Profit growth outpaces revenue growth thanks to a disproportionately strong increase in non-operating income and the revaluation effect.
However, $564 million of costs came from the change in fair value of contingent consideration on the GIP and HPS deals. This item is unrelated to operations and depends on BlackRock's share price at period end. Excluding it, adjusted net income would have been $2,621 million, and diluted earnings per share $15.93 versus $11.55 a year earlier.
Thus reported profit is understated by the non-cash revaluation, while adjusted profit is overstated relative to a sustainable base. The true operating result lies between these two figures.
Net inflows reached $205 billion, of which $135 billion went into iShares
Total net inflows in the third quarter of 2026 reached $205 billion, corresponding to 11% annualised organic base fee growth. This is broad-based strength across asset classes, client types and regions.
iShares generated $135 billion of inflows, active strategies $66 billion, of which $44 billion came into institutional active accounts. The retail segment added $23 billion. Cash management inflows were $31 billion.
Assets under management reached $15.5 trillion, up 15% year-on-year. Over the last twelve months the company attracted $869 billion, confirming the resilience of the franchise and its ability to generate organic growth even amid market volatility.
Aladdin technology revenue grew 14% and drives 12% ACV growth
Technology services and subscription revenue in the third quarter of 2026 was $588 million, up 14% year-on-year. This is one of BlackRock's fastest-growing and highest-margin segments.
Technology annual contract value (ACV) grew 12%. Demand for Aladdin and multi-product solutions remains strong, confirmed by revenue growth of $73 million year-on-year and $22 million quarter-on-quarter.
The technology segment still accounts for less than 8% of total revenue, but its contribution to margin and business diversification is growing. It is less dependent on market indices and provides more predictable cash flow.
Return on equity of 13.4% with no dividend history in the facts
BlackRock's return on equity is 13.4%. This is a moderate figure for a company of its market capitalisation, reflecting a significant amount of intangible assets and goodwill on the balance sheet after a series of acquisitions.
The company paid dividends of $5.73 per share in the third quarter of 2026 and $17.19 for the nine months. However, the provided facts contain no information on dividend policy or payment history, which prevents assessing dividend sustainability.
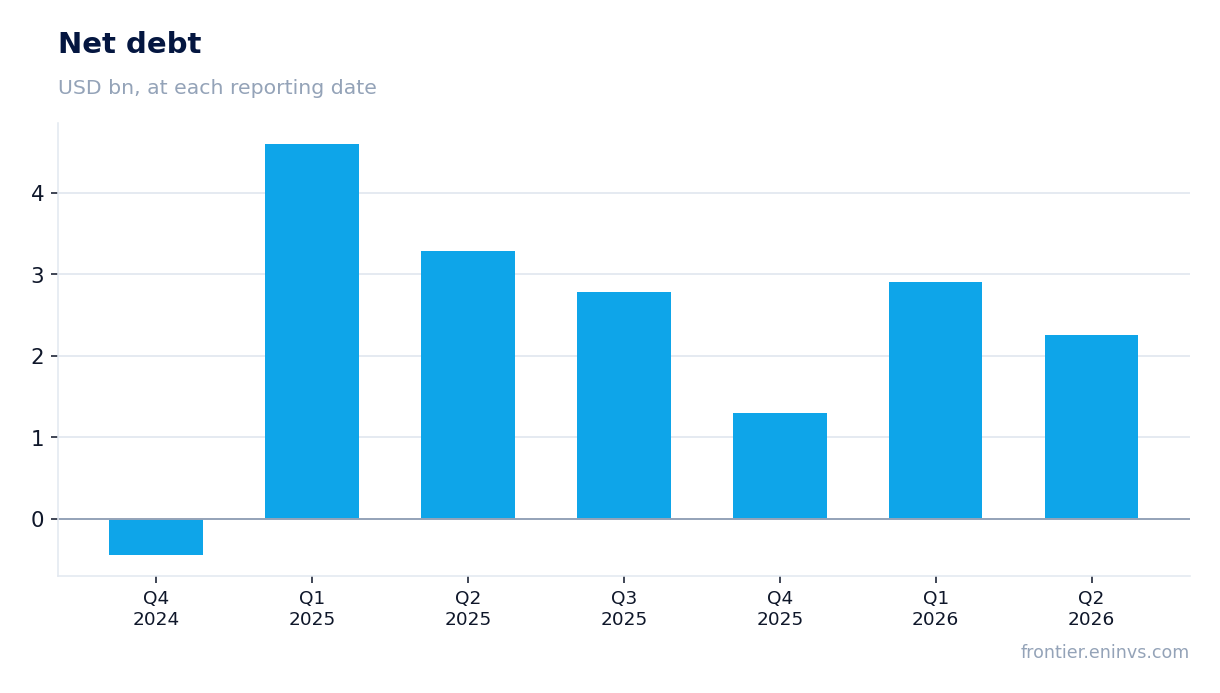
Net debt at the end of the latest annual balance sheet was $1,300 million. This is a moderate level for a company with such profit and cash flow. Operating cash flow for the nine months of 2026 and quarterly data on it are absent from the facts, which limits leverage analysis.
Bottom line
BlackRock delivered a strong quarter: revenue rose 19.1%, net income 25.4%, and net inflows reached $205 billion. However, growth decelerated from the second quarter, and $564 million of costs came from non-cash contingent consideration revaluation. Adjusted margin of 47.8% and 14% growth in technology revenue point to the resilience of the business model. At the current price the share looks rather attractive for investors willing to tolerate reported profit volatility from one-off items.