Crown Castle: revenue falls for a seventh straight quarter, yet margin rose to 67.6%
In its Q3 2026 report, Crown Castle posted revenue of $995.0 million, EBITDA of $673.0 million and net profit of $283.0 million. Revenue fell 7.2% year on year, a deeper decline than the 4.9% drop in Q2. Yet the EBITDA margin rose to 67.6% from 64.6% a year earlier. The share looks neutral: the revenue decline is offset by a strong margin, but leverage and negative return on equity leave little room for optimism.
Key takeaways
— Revenue fell 7.2% year on year, and the decline accelerated from 4.9% in Q2
— EBITDA fell only 2.7%, while the margin rose to 67.6% from 64.6%
— Net profit dropped 12.4% as the net margin narrowed to 28.4% from 30.1%
— Debt of $27.0 billion against quarterly EBITDA of $673.0 million remains the key risk
— Negative return on equity of -14.5% reflects weak profit against high leverage
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 1.07 | 0.99 | -7.2% |
| EBITDA | 0.69 | 0.67 | -2.7% |
| Operating profit | 0.53 | — | — |
| Net profit | 0.32 | 0.28 | -12.4% |
| Operating cash flow | 0.71 | — | — |
| Capex | 0.04 | — | — |
| EBITDA margin | 64.6% | 67.6% | +3.0 pp |
| Net margin | 30.1% | 28.4% | -1.7 pp |
Revenue fell 7.2% year on year, and the decline accelerated from 4.9% in Q2
Revenue in Q3 2026 was $995.0 million, down 7.2% from a year earlier. In Q2 the decline was 4.9%, so the rate of contraction accelerated. This is the seventh consecutive quarter of falling revenue.
The revenue decline reflects the overall business trend, but the report does not disclose the reasons. What can be stated is that the company is losing revenue faster than in the previous quarter. For an investor, this signals that pressure on the top line persists.
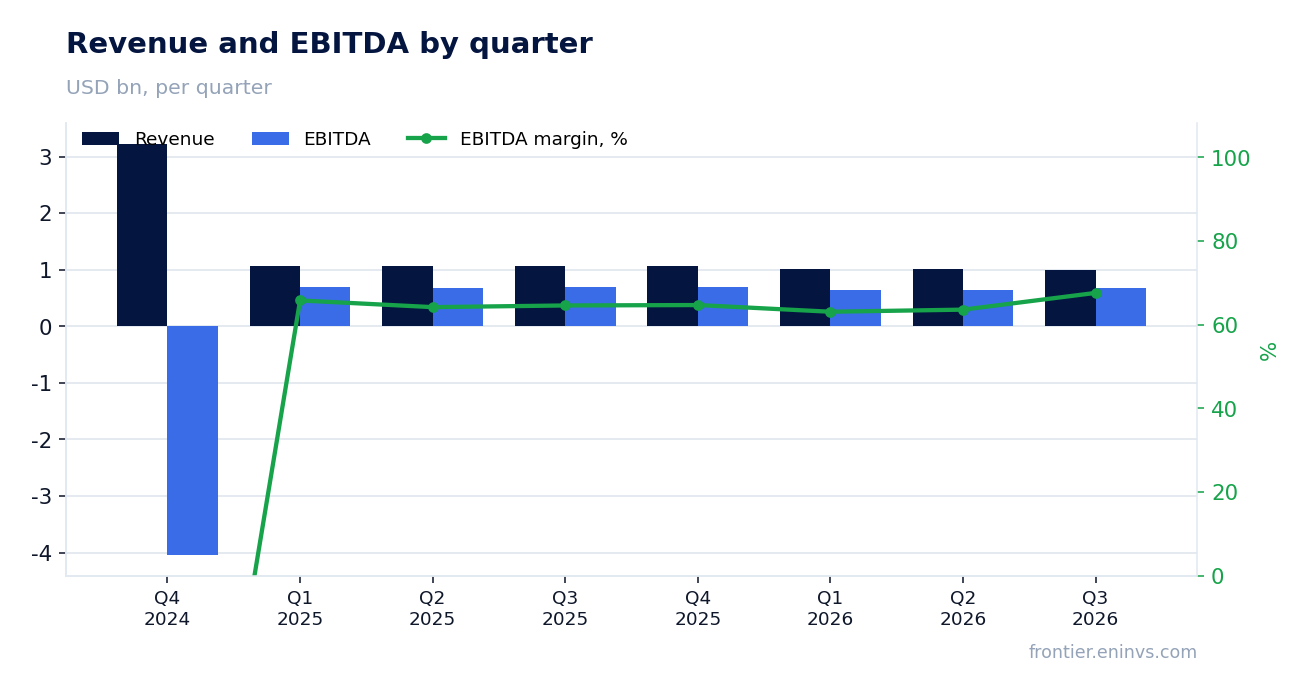
EBITDA fell only 2.7%, while the margin rose to 67.6% from 64.6%
EBITDA in Q3 2026 was $673.0 million, down 2.7% from a year earlier. At the same time, the EBITDA margin rose to 67.6% from 64.6%. This means the company cut costs or improved its cost structure, offsetting the revenue decline.
Margin expansion amid falling revenue is a positive signal for operating efficiency. However, the sustainability of this improvement is questionable, as it may stem from one-off factors or cost cuts that cannot continue indefinitely.
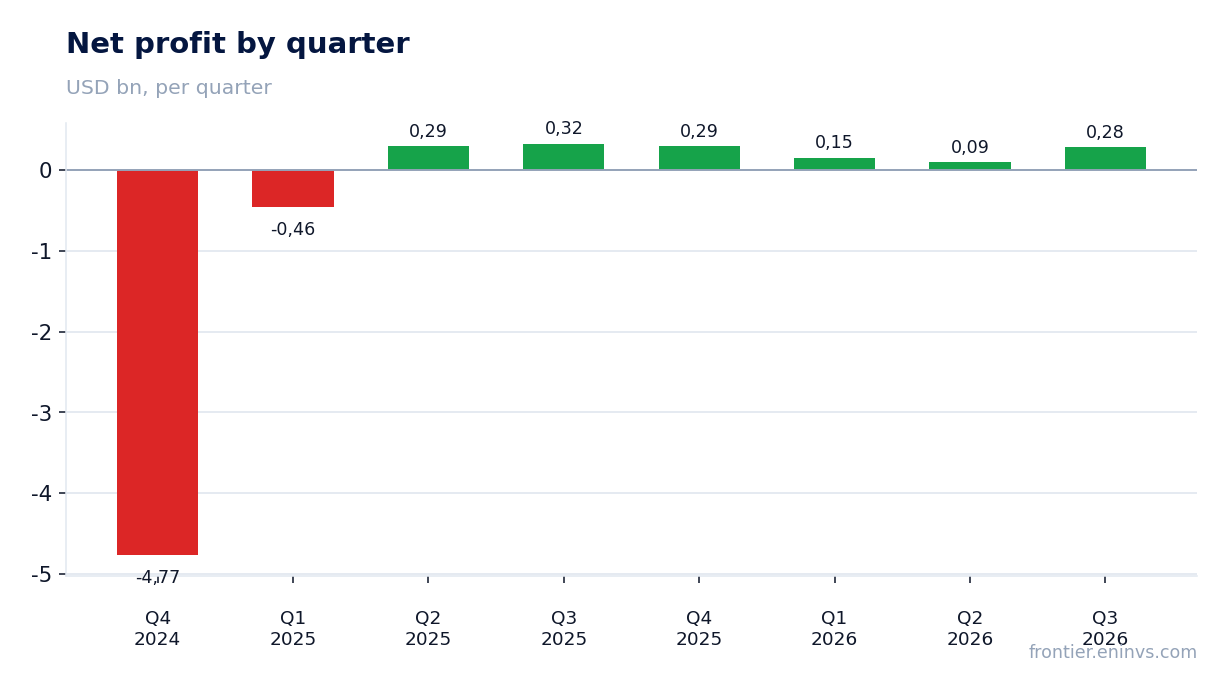
Net profit dropped 12.4% as the net margin narrowed to 28.4% from 30.1%
Net profit in Q3 2026 was $283.0 million, down 12.4% from a year earlier. The net margin narrowed to 28.4% from 30.1%. This decline is deeper than the EBITDA drop, pointing to higher expenses below the operating line – likely interest payments or taxes.
The decline in net profit with relatively stable EBITDA indicates that leverage and the cost of servicing debt are weighing on the bottom line. This limits the company's ability to grow profit even with improved operating efficiency.
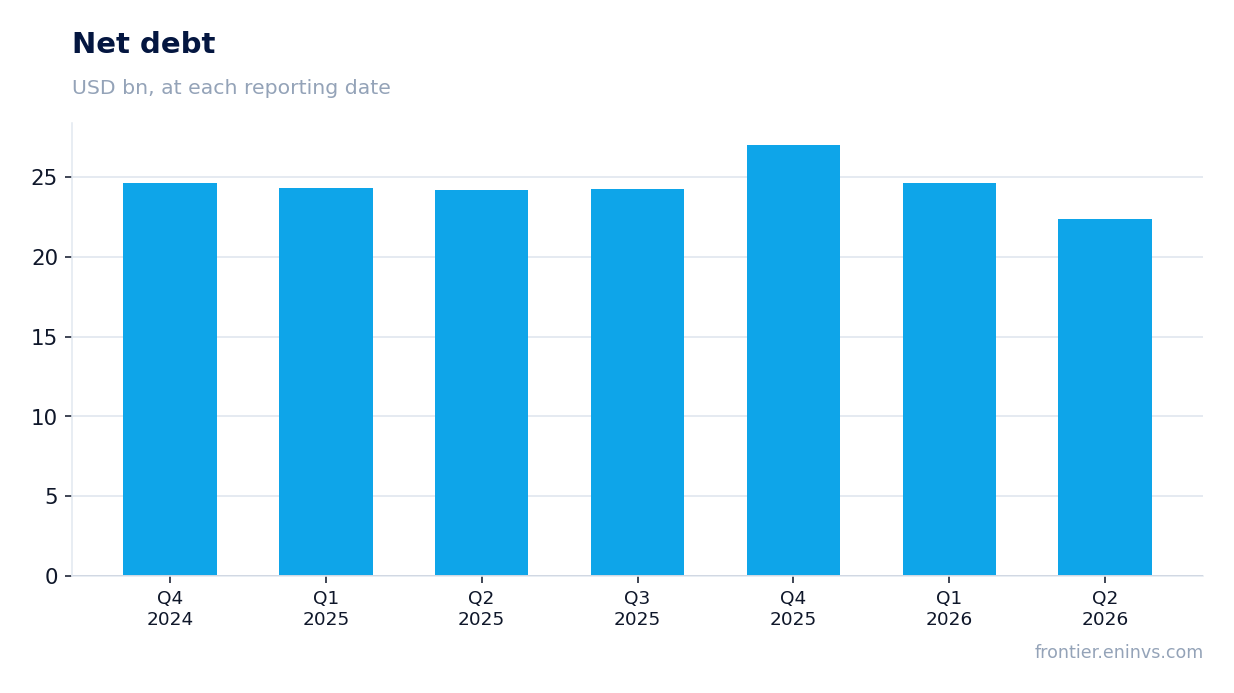
Debt of $27.0 billion against quarterly EBITDA of $673.0 million remains the key risk
Net debt at the latest reporting date is $27.0 billion. With quarterly EBITDA of $673.0 million, annual EBITDA is about $2.7 billion, giving a debt-to-EBITDA ratio of roughly 10x. This is a high level of leverage that limits financial flexibility.
High debt means significant interest expenses, which are already reflected in the decline in net profit. For an investor, this is a key risk: even with stable operations, the company may struggle to service its debt if rates rise or market conditions deteriorate.
Negative return on equity of -14.5% reflects weak profit against high leverage
Return on equity (ROE) is -14.5%. A negative value indicates that the company generates a loss on invested capital. This is due to both high leverage and pressure on net profit.
Negative ROE is an alarming signal for shareholders, as it means the company is not creating value on invested capital. Combined with high debt, this limits the investment appeal of the shares despite strong operating margins.
Bottom line
The report's strong point is the rise in EBITDA margin to 67.6% and the ability to keep profit at $283.0 million. However, revenue has fallen for seven consecutive quarters, and the rate of decline accelerated to 7.2%. High debt and negative ROE limit growth opportunities. The share looks neutral: operating efficiency is offset by financial risks, but a turnaround in revenue or a reduction in leverage is needed to improve the valuation.
Open the company's financial profile CCI →
See also: market overview · valuation map · stock screeners