Merck & Co., Inc.: revenue grows, but one-off charges drive a loss and make shares expensive
Contents
4 августа 2026 года Merck & Co., Inc. раскрыла результаты за второй квартал 2026 года. Выручка выросла на 5,1% год к году до 16 607 млн долларов, однако чистый убыток составил 1 335 млн долларов против прибыли 4 427 млн годом ранее из-за крупных списаний в R&D. При текущей цене акции выглядят скорее непривлекательно: мультипликаторы значительно выше исторических средних, а убыточность и высокий долг добавляют рисков.
Key takeaways
— Revenue grew 5.1% in Q2, driven by new drugs
— Net loss of $1,335 million due to one-off R&D charges
— Net margin fell from 28.0% to -8.0% on the loss
— Debt rose by $3.4 billion in the quarter to $46,765 million
— Shares rose 17.7% after the report, but valuation remains high
— Dividend yield of 2.26% looks moderate amid losses
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 15.8 | 16.6 | +5.1% |
| EBITDA | 5.52 | — | — |
| Operating profit | 5.00 | — | — |
| Net profit | 4.43 | -1.33 | -130.2% |
| Operating cash flow | 3.29 | 5.37 | +63.1% |
| Capex | 0.76 | 0.89 | +16.9% |
| EBITDA margin | 34.9% | — | — |
| Net margin | 28.0% | -8.0% | -36.0 pp |
Revenue grew 5.1% in Q2, driven by new drugs
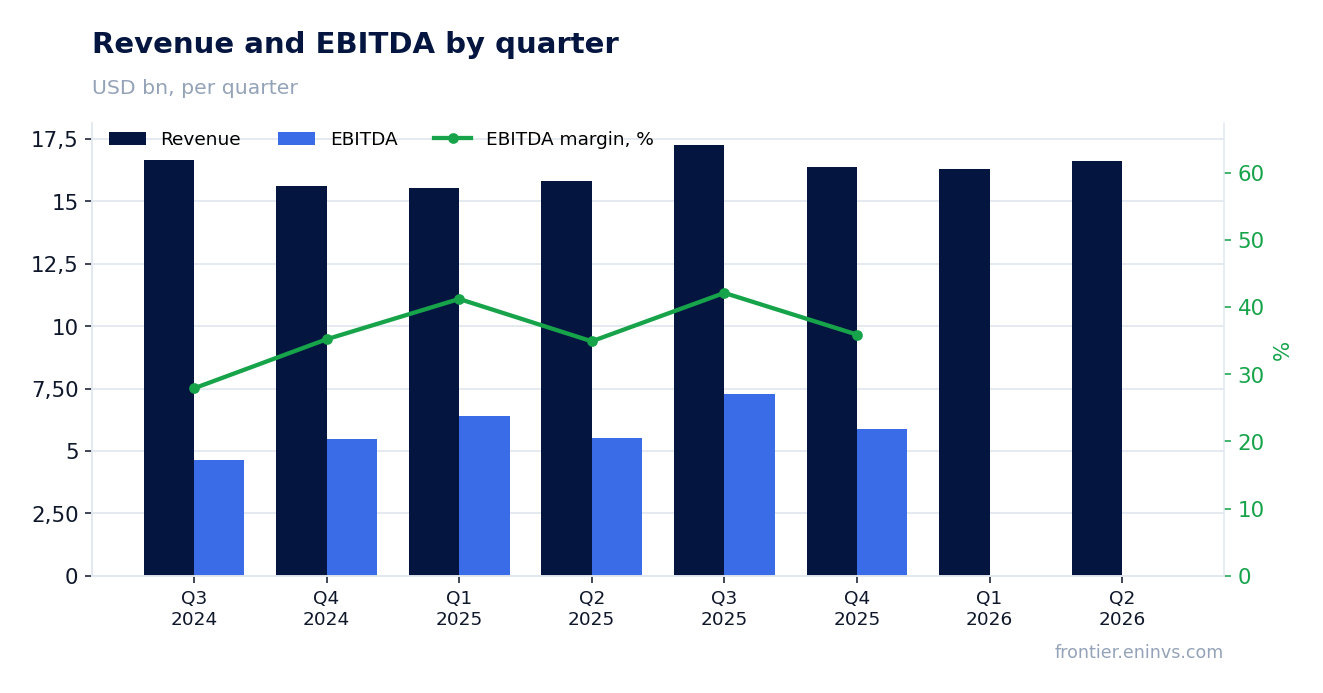
In Q2 2026, Merck & Co., Inc. sales reached $16,607 million, up 5.1% year-over-year. Key contributors were new drugs: Winrevair brought in $588 million (+75%), Ohtuvayre – $204 million (launched in 2025), Capvaxive – $184 million (+42%). The key drug Keytruda declined slightly by 1% to $7,904 million, but the pharmaceutical segment overall grew 5%.
Revenue growth accelerated compared to previous quarters: 4.9% in Q1 2026 and 5.1% in Q2. This confirms that the company is offsetting patent losses on older drugs with new products.
Net loss of $1,335 million due to one-off R&D charges
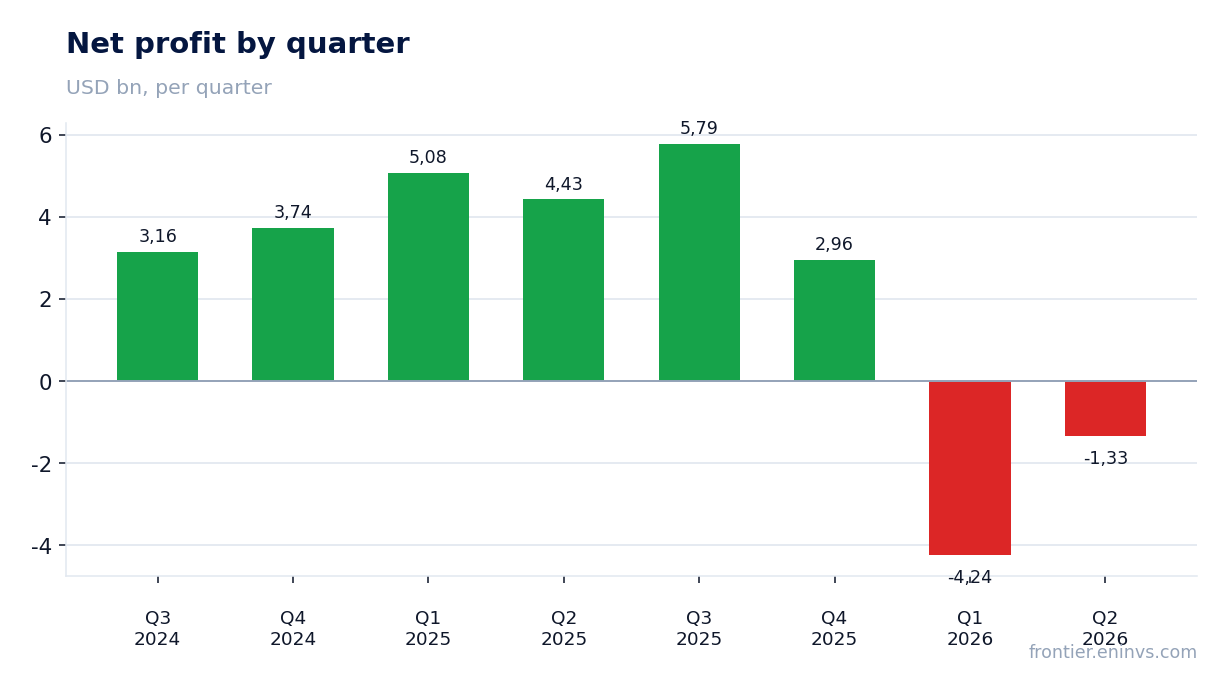
In Q2 2026, Merck & Co., Inc. reported a net loss of $1,335 million versus a profit of $4,427 million a year earlier. The cause is a sharp increase in R&D expenses: they reached $9,741 million versus $4,048 million in Q2 2025. The company notes in the report that this is due to one-off charges, including acquisitions and restructuring.
Excluding these items, adjusted profit would have been $5,366 million, above last year's $4,427 million. However, on a GAAP basis the company is loss-making, which affects balance sheet metrics.
Net margin fell from 28.0% to -8.0% on the loss
In Q2 2026, Merck & Co., Inc.'s net margin was -8.0% versus 28.0% a year earlier. This is a direct consequence of the loss: with revenue of $16,607 million, the net result is negative.
The margin decline is one-off, related to charges, but it shows how volatile the company's profit can be due to large R&D investments. Operating margin excluding charges remains high, but GAAP metrics deteriorated.
Debt rose by $3.4 billion in the quarter to $46,765 million
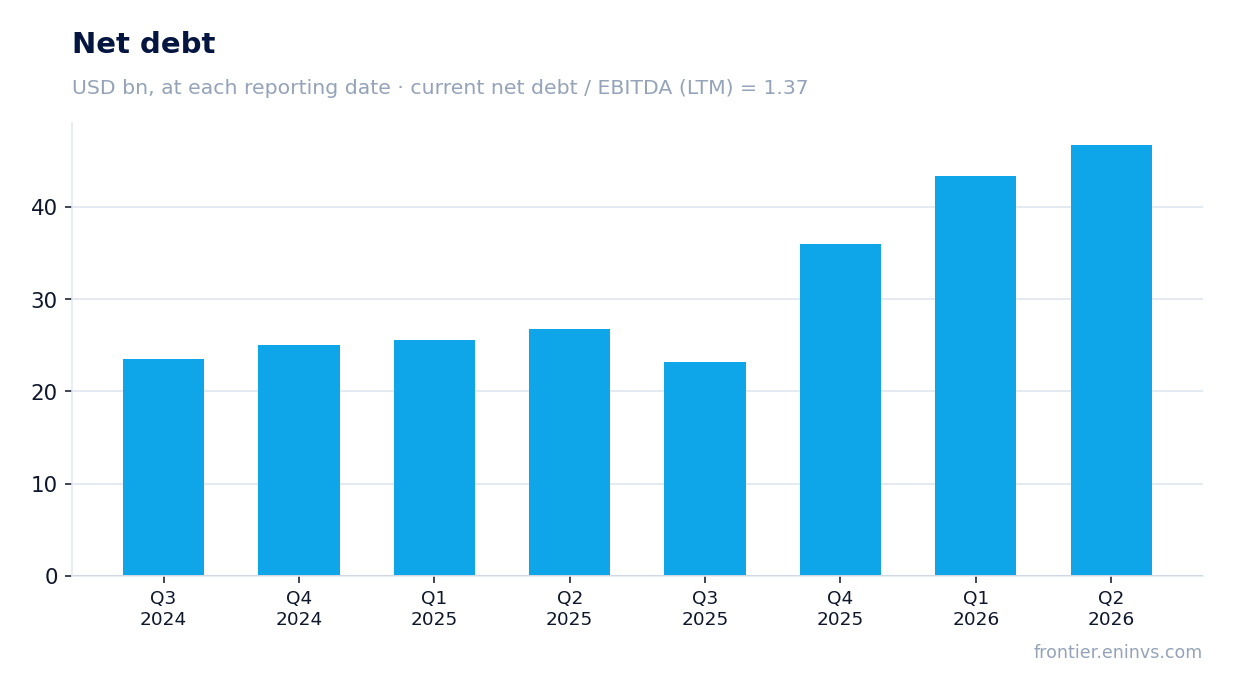
Net debt of Merck & Co., Inc. at the end of Q2 2026 stood at $46,765 million, up $3.4 billion from the previous reporting date. Over the past 12 months, debt increased by $20.0 billion – the company is actively financing R&D and acquisitions with borrowed funds.
Net debt to EBITDA for the trailing twelve months is 1.37 – a moderate level, but with losses and rising debt, financial flexibility is decreasing. The company continues to pay dividends, which also requires cash.
Shares rose 17.7% after the report, but valuation remains high
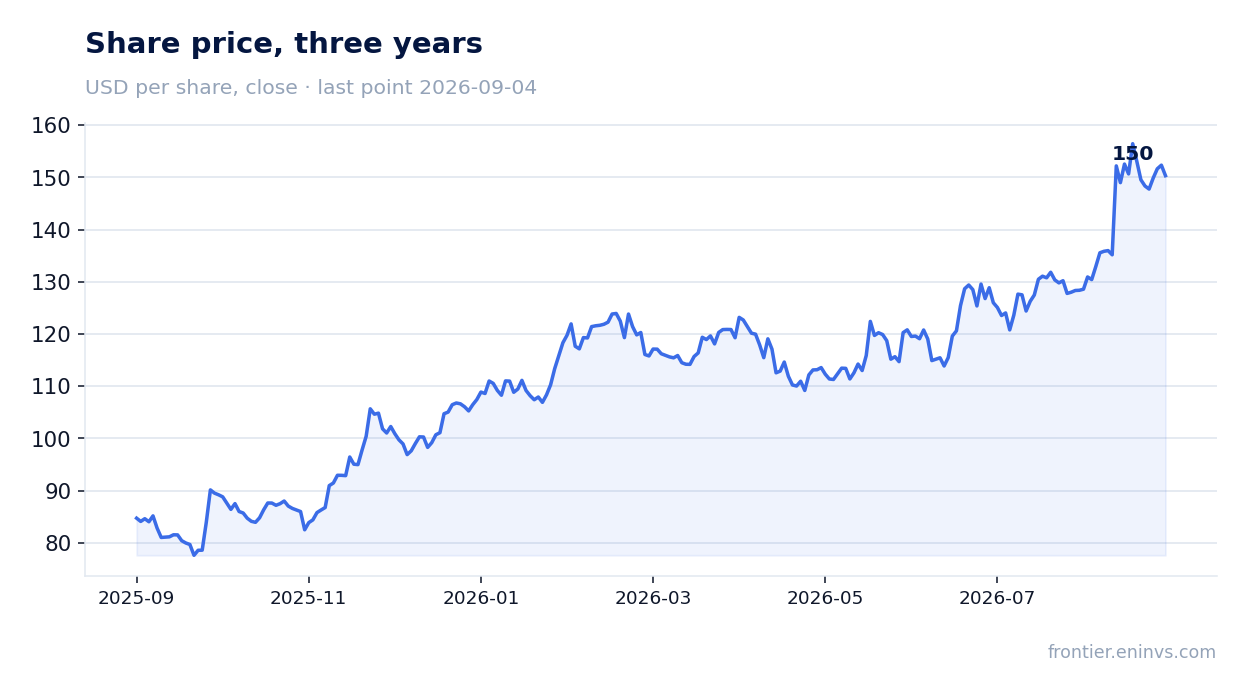
After the report on August 4, 2026, Merck & Co., Inc. shares rose 17.7% by September 4, with only 0.2% gain on the release day. Investors apparently viewed the prospects of new drugs positively despite the loss.
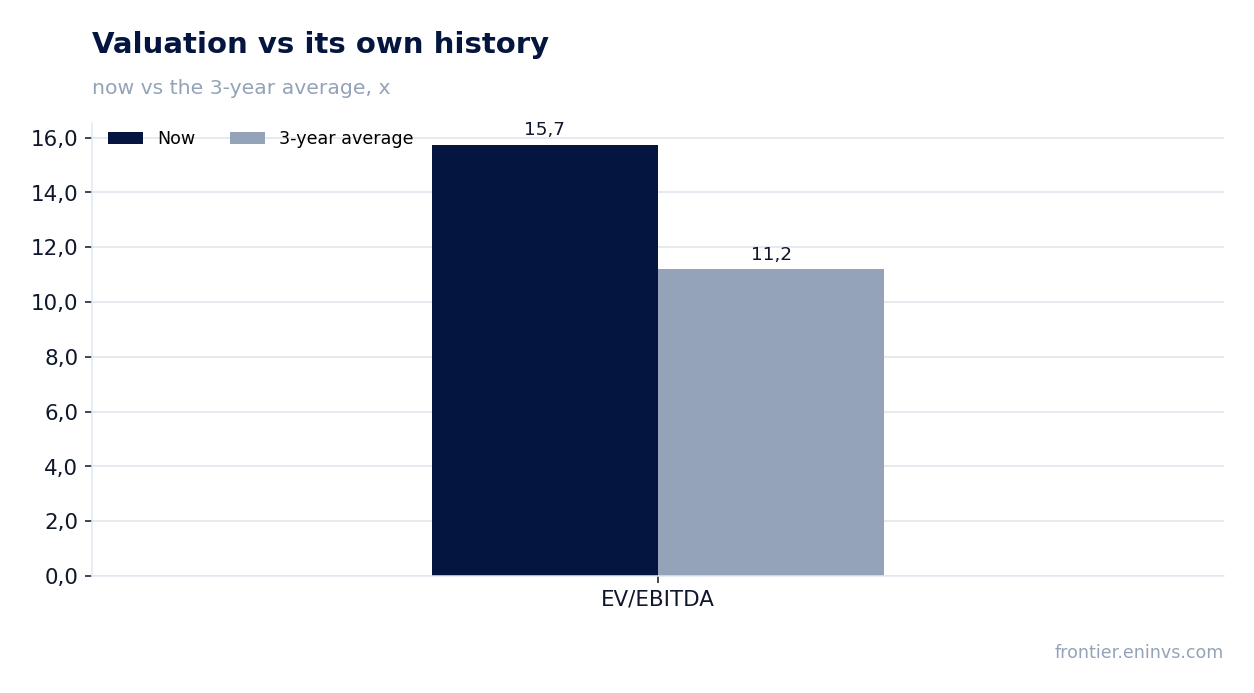
However, valuation remains high: P/E for the trailing twelve months is 118.8, and EV/EBITDA is 15.7 versus the three-year average of 11.2. The stock trades well above its own history, limiting upside potential.
Dividend yield of 2.26% looks moderate amid losses
Merck & Co., Inc.'s current dividend yield for the trailing twelve months is 2.26%. This is below the market average, but for a pharmaceutical company with losses and rising debt, such a level looks moderate.
The company continues to pay dividends, supporting shareholders, but with persistent losses and rising debt, this could become a burden on cash flow. Operating cash flow for the trailing twelve months was $16,500 million, covering dividends, but with capex and debt, the margin of safety is thin.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 377 bn USD |
| P/E (LTM) | 118.8 |
| EV/EBITDA (LTM) | 15.7 |
| P/B | 7.16 |
| Net debt / EBITDA (LTM) | 1.37 |
| Operating cash flow (LTM) | 16.5 bn |
| ROE | -12.2% |
| Dividend yield (12m) | 2.3% |
| EV/EBITDA, 3-year average | 11.2 |
Bottom line
In Q2 2026, Merck & Co., Inc. showed solid revenue growth of 5.1%, driven by new drugs, but net profit turned negative due to one-off charges of nearly $10 billion. Debt continues to rise, and the share valuation is well above historical averages. At the current price, shares look rather unattractive: investors are paying for future growth that has not yet materialized in profit. To change the assessment, the company needs to return to sustainable profitability and slow debt growth.