Simon Property: revenue up 13.3% but net income down 29% on non-cash revaluation
On November 5, Simon Property Group reported third-quarter 2026 results. Revenue reached $1.81 bn (+13.3% YoY), EBITDA – $1.32 bn (+14.2%), net income – $499.0 mn (-29.0%). The profit decline is explained by non-cash losses of $99.6 mn from revaluation of Klépierre exchangeable bonds and a publicly traded equity security. The share looks attractive: revenue growth decelerated from 19.5% to 13.3%, but operating metrics and dividend policy remain strong.
Key takeaways
— Revenue grew 13.3% YoY but decelerated from 19.5% a quarter earlier
— EBITDA added 14.2% and margin rose to 72.5% from 71.9%
— Net income fell 29.0% on non-cash losses of $99.6 mn
— Net debt rose to $28.6 bn from $27.7 bn at end-June
— Dividend raised 4.5% to $2.30 per quarter
— Real Estate FFO per share rose 4.7% to $3.37
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 1.60 | 1.81 | +13.3% |
| EBITDA | 1.15 | 1.32 | +14.2% |
| Operating profit | 0.81 | 0.80 | -1.0% |
| Net profit | 0.70 | 0.50 | -29.0% |
| Operating cash flow | 0.89 | — | — |
| Capex | 0.21 | — | — |
| EBITDA margin | 71.9% | 72.5% | +0.6 pp |
| Net margin | 43.9% | 27.5% | -16.4 pp |
Revenue grew 13.3% YoY but decelerated from 19.5% a quarter earlier
Third-quarter 2026 revenue reached $1.81 bn, up 13.3% from $1.60 bn a year earlier. This is a deceleration from the second quarter, when growth reached 19.5%. The slowdown reflects a higher base a year ago and a general normalisation of growth rates after a strong first half.
Lease income is the main contributor at $1.68 bn versus $1.45 bn a year earlier. Management fees and other revenues added $46.2 mn and $87.0 mn respectively. Rising base rents and occupancy at 96.5% support the dynamics.
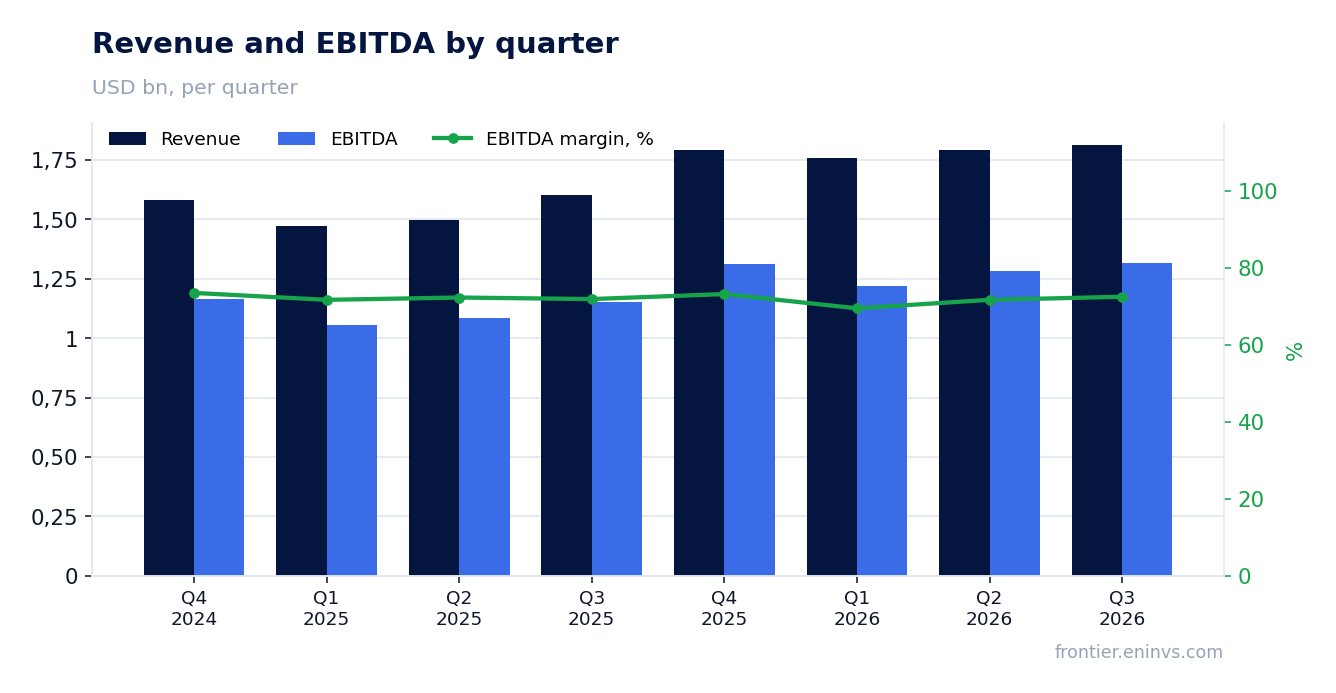
EBITDA added 14.2% and margin rose to 72.5% from 71.9%
EBITDA in the reported quarter was $1.32 bn, up 14.2% year on year. The EBITDA margin rose to 72.5% from 71.9%. Margin expansion was driven mainly by higher lease income with relatively stable operating expenses.
Operating profit declined to $804.5 mn from $812.9 mn a year earlier. This reflects higher depreciation and amortisation of $510.8 mn versus $338.6 mn, reflecting asset revaluation and new properties coming online. Thus, at the EBITDA level the company shows growth, but depreciation eats into operating profit.
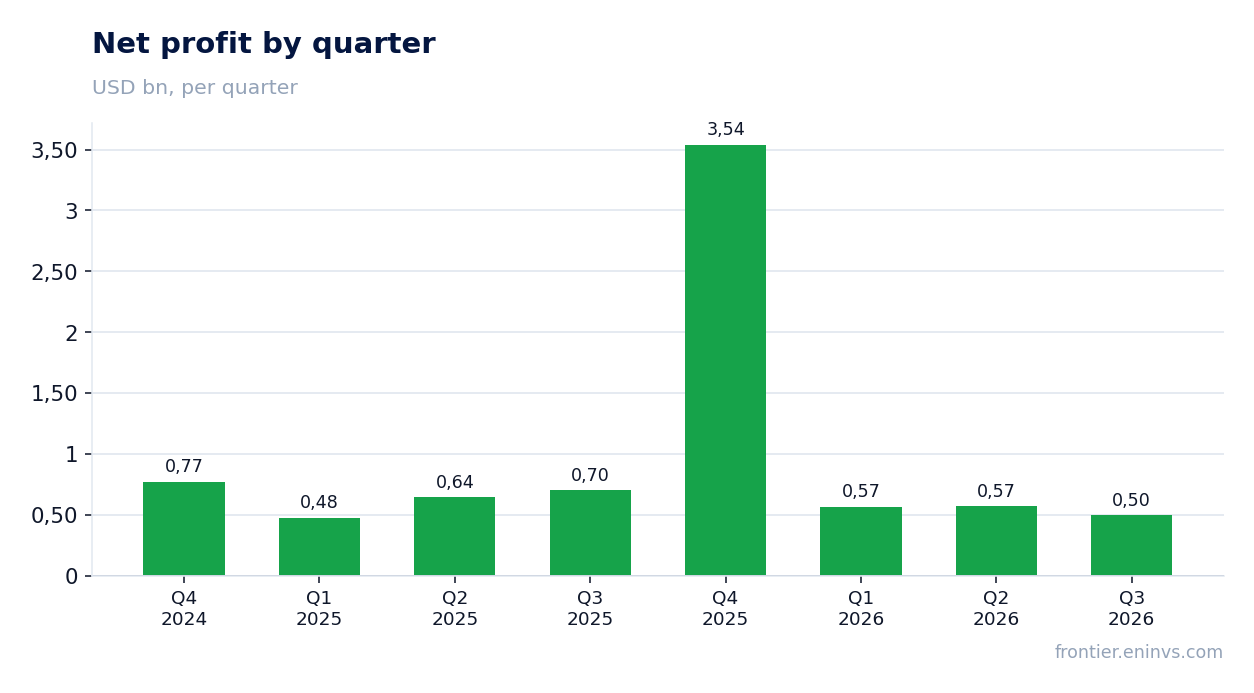
Net income fell 29.0% on non-cash losses of $99.6 mn
Net income attributable to common stockholders was $499.0 mn, or $1.54 per diluted share, versus $606.2 mn ($1.86) a year earlier. The 29.0% decline was driven by non-cash after-tax losses of $99.6 mn, or $0.27 per share, from revaluation of Klépierre exchangeable bonds and a publicly traded equity security held by an unconsolidated Other Platform Investment.
Excluding these one-off items, profit would have been higher, but even with them Real Estate FFO per share rose 4.7% to $3.37. This indicates that operating activity remains profitable and the net income decline is accounting-driven.
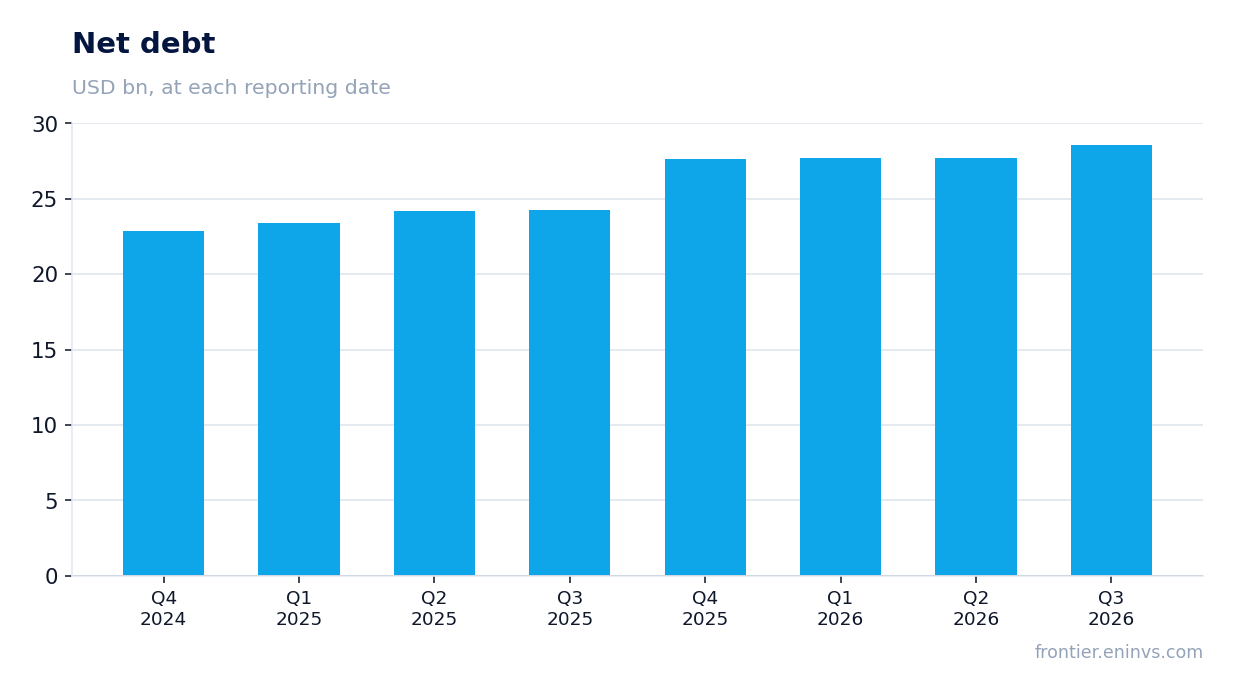
Net debt rose to $28.6 bn from $27.7 bn at end-June
Net debt at September 30, 2026 was $28.6 bn, up from $27.7 bn at June 30, 2026 (+$0.9 bn). Over twelve months, net debt rose from $24.2 bn at September 30, 2025 to $28.6 bn (+$4.3 bn). The increase reflects financing of development and share repurchases.
During the quarter, the company issued $800 mn of senior notes at a weighted-average coupon of 5.45% and completed seven secured loan transactions totalling $970 mn at 6.33%. Liquidity remains high at approximately $9.0 bn, including $1.3 bn of cash. Interest expense rose to $287.6 mn from $242.8 mn a year earlier.
Dividend raised 4.5% to $2.30 per quarter
The board declared a quarterly dividend of $2.30 per share for the fourth quarter of 2026, up 4.5% from the previous level. Payment is due December 31, 2026 to shareholders of record on December 10. The increase reflects management's confidence in cash flow sustainability.
Over the last twelve months, the company paid dividends that at the current price provide a yield competitive with the risk-free rate. Our estimate for the full-year 2026 dividend is about $9.20 per share, based on quarterly payments. The payout is supported by Real Estate FFO, which was $9.82 per share for the nine months.
Real Estate FFO per share rose 4.7% to $3.37
Real Estate FFO, the key REIT metric, was $1.277 bn, or $3.37 per diluted share, versus $1.215 bn ($3.22) a year earlier. The 4.7% increase reflects higher lease income and cost control. FFO including one-off items was $3.09 per share.
The company raised its 2026 Real Estate FFO guidance to $13.30–$13.40 per share, $0.10 above the previous range. This is the second guidance increase this year. Net income guidance is $6.32–$6.42 per share.
Bottom line
Simon Property delivered strong operating results: revenue grew 13.3%, EBITDA – 14.2%, margin rose to 72.5%. The 29.0% decline in net income was driven by non-cash losses and does not reflect a deterioration in the business. The company raised its Real Estate FFO guidance and increased the dividend by 4.5%. The key question for a holder is the deceleration in revenue growth and rising debt, but the dividend yield and stable cash flow make the share attractive.
Open the company's financial profile SPG →
See also: market overview · valuation map · stock screeners