Vertiv Holdings Co: revenue up 24% and guidance raised, but shares fell 17%
Contents
29 июля Vertiv Holdings Co раскрыла результаты за второй квартал 2026 года. Выручка выросла на 24,1% до 3 274,3 млн долл., EBITDA – на 46,2% до 753,7 млн долл., чистая прибыль – на 53,5% до 497,8 млн долл. Несмотря на сильные цифры и повышение годового прогноза, акции в день публикации упали на 17,3%. На наш взгляд, при текущей цене бумага выглядит скорее привлекательно: рост ускоряется, маржинальность расширяется, долг минимален, а оценка, хотя и выше собственной трехлетней истории, отражает высокие ожидания, которые компания пока оправдывает.
Key takeaways
— Revenue in Q2 grew 24.1% to $3,274.3 million, with organic growth of 17.8%
— EBITDA margin expanded by 3.5 pp to 23.0% on operational efficiency and favorable price-cost
— Net profit rose 53.5% to $497.8 million, with one-off items adding about $100 million
— Operating cash flow reached $1,099.8 million, and the company achieved a net cash position
— The company raised its 2026 guidance: revenue of $14,000 million and adjusted EPS of $6.70
— Shares fell 17.3% on the release day but have since recovered 4.1%
— The portal's model implies 16% upside to the current price
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 2.64 | 3.27 | +24.1% |
| EBITDA | 0.52 | 0.75 | +46.2% |
| Operating profit | 0.44 | 0.64 | +44.2% |
| Net profit | 0.32 | 0.50 | +53.5% |
| Operating cash flow | 0.32 | 1.10 | +240.6% |
| Capex | 0.04 | 0.17 | +287.8% |
| EBITDA margin | 19.5% | 23.0% | +3.5 pp |
| Net margin | 12.3% | 15.2% | +2.9 pp |
Revenue in Q2 grew 24.1% to $3,274.3 million, with organic growth of 17.8%
In Q2 2026, Vertiv Holdings Co's revenue reached $3,274.3 million, up 24.1% year-over-year. Organic growth, excluding currency and acquisitions, was 17.8%. The company highlights growth in the Americas (+29.2%) and Asia-Pacific (+28.5%), while EMEA was nearly flat (+1.7%).
The report mentions minor timing shifts in revenue due to supply chain congestion and multi-phased project execution. Nevertheless, the company raised its full-year revenue guidance to $14,000 million, implying organic growth of about 31%.
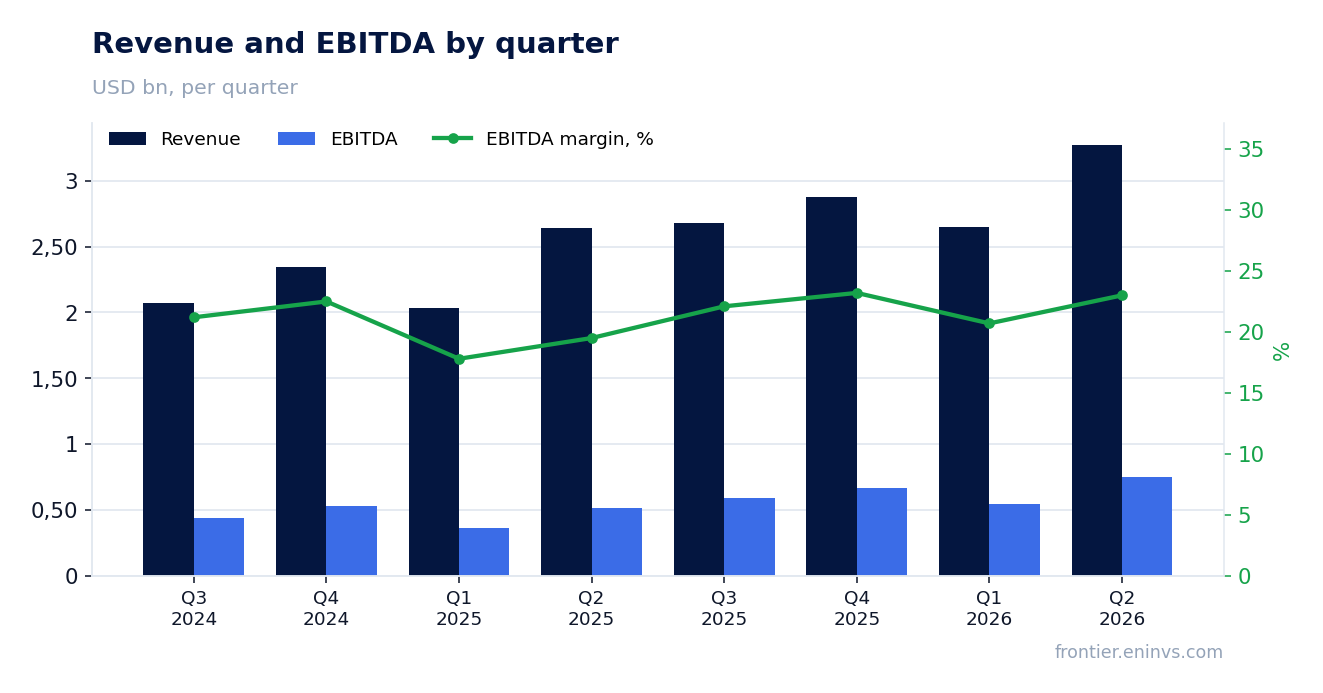
EBITDA margin expanded by 3.5 pp to 23.0% on operational efficiency and favorable price-cost
EBITDA in Q2 rose 46.2% to $753.7 million, with an EBITDA margin of 23.0% versus 19.5% a year earlier. The company attributes the margin expansion to operational execution, continued productivity, and favorable price-cost, including tariff impacts and countermeasures.
Operating profit increased 44% to $637.9 million, and adjusted operating margin was 22.6% – up 410 basis points year-over-year. Margin expansion is the key driver allowing profit to grow faster than revenue.
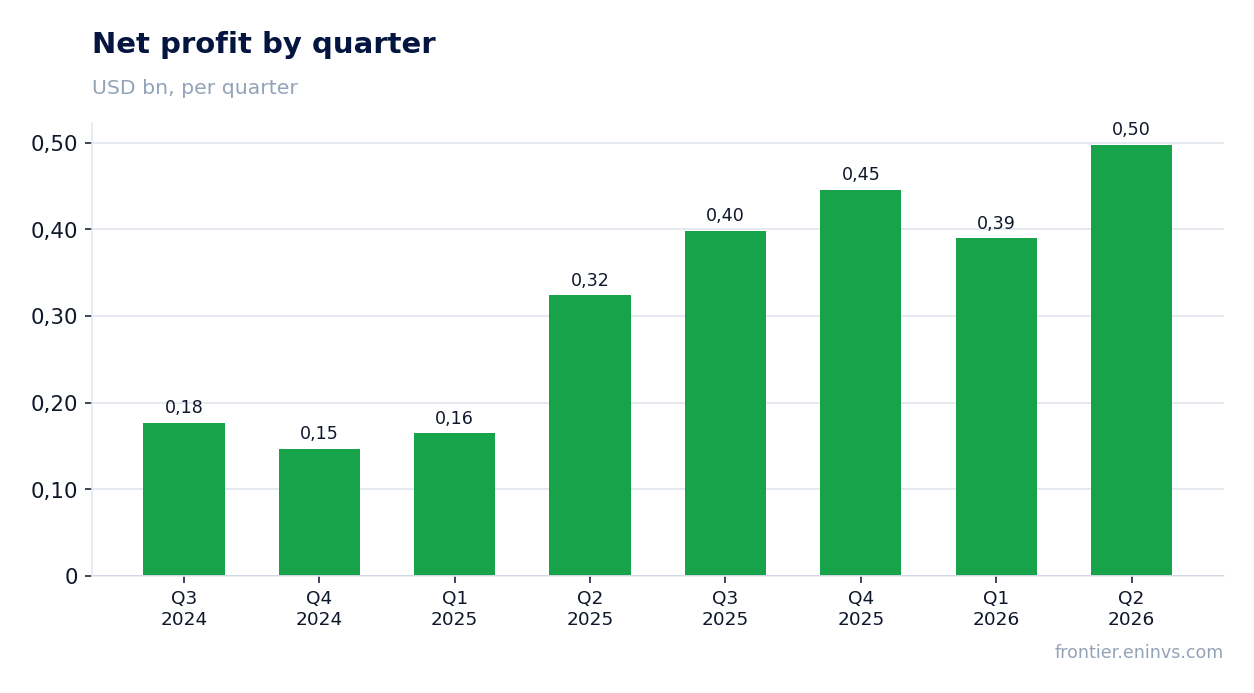
Net profit rose 53.5% to $497.8 million, with one-off items adding about $100 million
Net profit for Q2 was $497.8 million, up 53.5% year-over-year. Diluted EPS rose to $1.27. The profit includes one-off items: remeasurement of contingent consideration for the PurgeRite acquisition (+$28.8 million), restructuring costs (-$3.9 million), and M&A costs (+$1.9 million). Excluding these, adjusted EPS would have been $1.52, up 60% from a year ago.
Thus, roughly $100 million of net profit (or about $0.25 per share) is related to one-off and non-operating items. Still, operating performance remains the main growth driver.
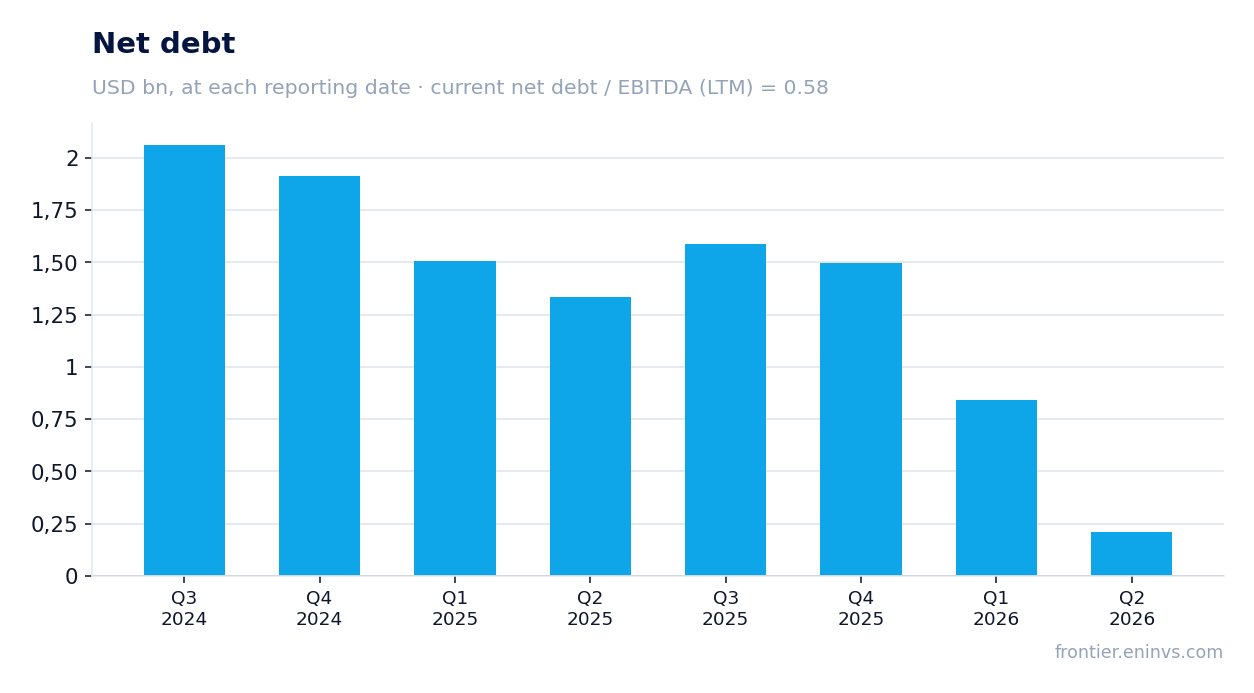
Operating cash flow reached $1,099.8 million, and the company achieved a net cash position
In Q2, operating cash flow was $1,099.8 million – almost 3.4 times higher than a year earlier. Adjusted free cash flow reached $925.3 million, up 234%. The company attributes the increase to working capital efficiency and lower cash interest.
At quarter-end, Vertiv had $5.6 billion in liquidity and a net cash position: net debt fell to $211.2 million (from $1,336.5 million a year earlier). Capital expenditures in Q2 were $174.5 million, in line with plans to invest in capacity expansion.
The company raised its 2026 guidance: revenue of $14,000 million and adjusted EPS of $6.70
Vertiv raised its full-year 2026 guidance across all key metrics. It expects revenue in the range of $13,800–14,200 million (midpoint $14,000 million), with organic growth of 30–32%. The adjusted EPS guidance was raised to $6.65–$6.75 (midpoint $6.70), implying 60% growth over 2025.
The company also confirmed capital expenditures of about 4% of revenue and expects adjusted free cash flow of $2,400–2,600 million. The guidance raise reflects management's confidence in sustained demand for AI infrastructure.
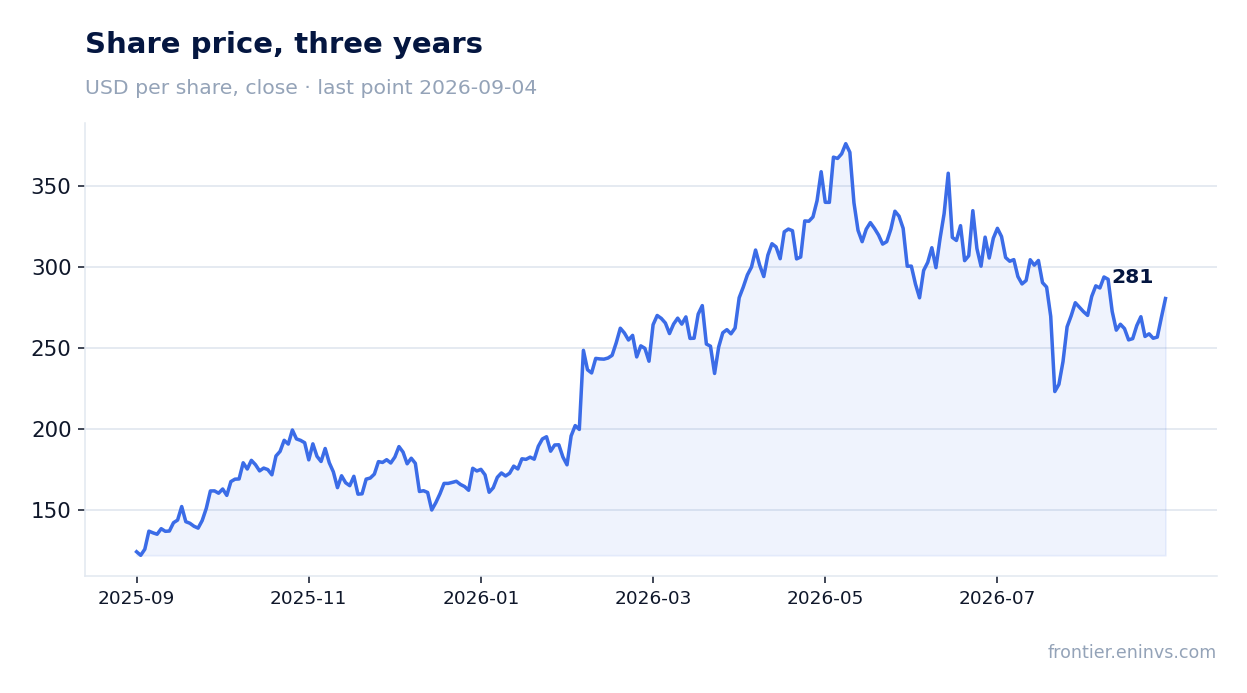
Shares fell 17.3% on the release day but have since recovered 4.1%
The closing price before the release was $269.56, and shares fell 17.3% on the release day. From the release to September 4, the stock recovered 4.1%, partially offsetting the drop. Market capitalization stands at $112,709.9 million.
The decline likely reflects profit-taking after a strong rally rather than deteriorating fundamentals. Over the last twelve months, revenue reached $11,500 million, net profit $1,732 million, and EBITDA $2,591 million.
The portal's model implies 16% upside to the current price
Our fundamental value-creation model, based on EBITDA growth and a target multiple, implies 16% upside to the current price. This is the portal's model estimate, not a market consensus or a target price.
The share is held in the 'US AI infrastructure' strategy on the portal. This is a fact, not an argument for the verdict: membership follows the strategy's screen, not our assessment.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 113 bn USD |
| P/E (LTM) | 65.1 |
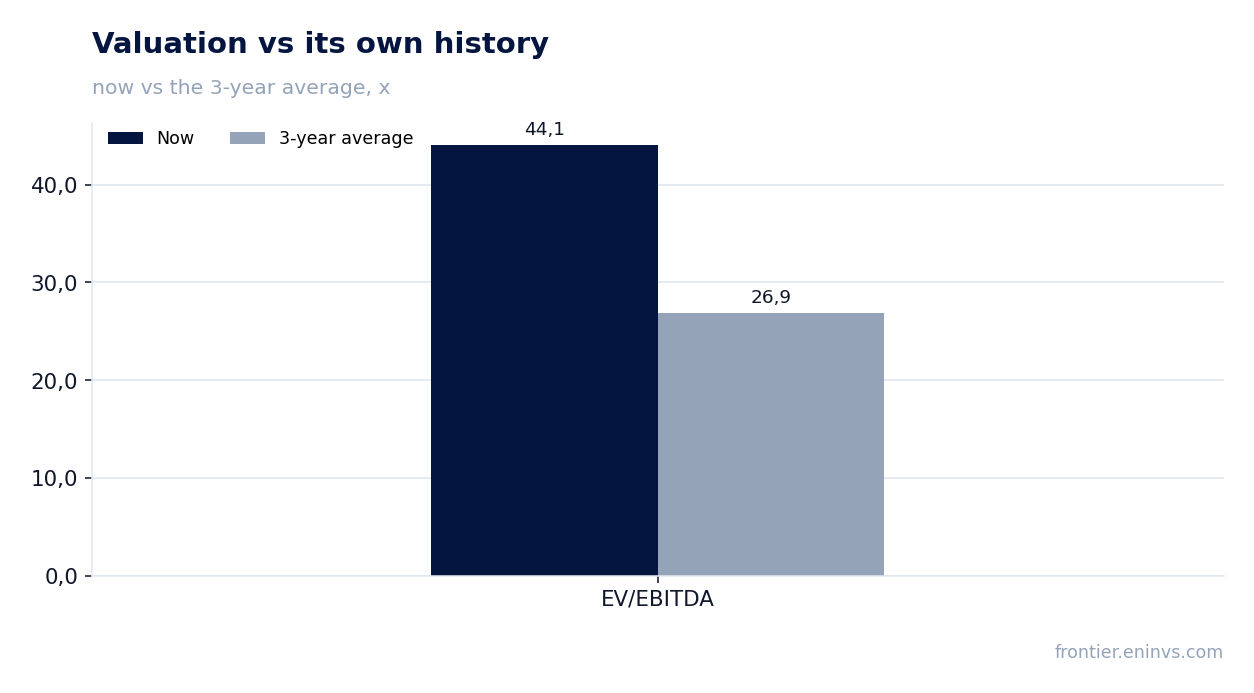
| EV/EBITDA (LTM) | 44.1 |
| P/B | 28.60 |
| Net debt / EBITDA (LTM) | 0.58 |
| Operating cash flow (LTM) | 2.10 bn |
| ROE | 44.2% |
| Dividend yield (12m) | 0.1% |
| EV/EBITDA, 3-year average | 26.9 |
Bottom line
Vertiv's Q2 2026 report is strong: revenue growing 24%, EBITDA margin expanding to 23%, operating cash flow at a record $1.1 billion, and a net cash position. The raised full-year guidance confirms management's confidence in sustained demand. However, the stock trades at a premium to its own history: EV/EBITDA LTM is 1.6 times above the three-year average. The portal's model implies 16% upside, making the share rather attractive but not cheap. The key question for holders is whether the company can continue to justify high expectations with growth and margins.