Abu Dhabi Commercial Bank: quarterly profit up 15.2%, but return on equity stays low for a bank
Abu Dhabi Commercial Bank today released its results for the third quarter of 2026. Quarterly net profit came to AED 3,559 million, up 15.2% year on year. Over the trailing twelve months the bank earned AED 13,637 million on net interest income of AED 21,000 million. At a market capitalisation of AED 131,850 million the shares trade at a P/E LTM of 9.67 with an ROE of 5.26%, and the portal's model implies +11% upside. We see the stock as neutral: profit growth is steady, but the low return on equity and modest model upside do not tip the balance in favour of buying.
Key takeaways
— Quarterly profit rose 15.2%, but that is slower than the top line grew a year earlier
— Trailing-twelve-month net interest income reached AED 21,000 million and remains the backbone of profit
— A return on equity of 5.26% is low for a bank, and it is what caps the valuation
— A P/E LTM of 9.67 with the portal model's +11% upside offers no clear edge
— The dividend history is not disclosed in the facts, so we do not build the payout into the valuation
Attractiveness
Key figures, AED bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net profit | 3.09 | 3.56 | +15.2% |
| Capex | 0.24 | — | — |
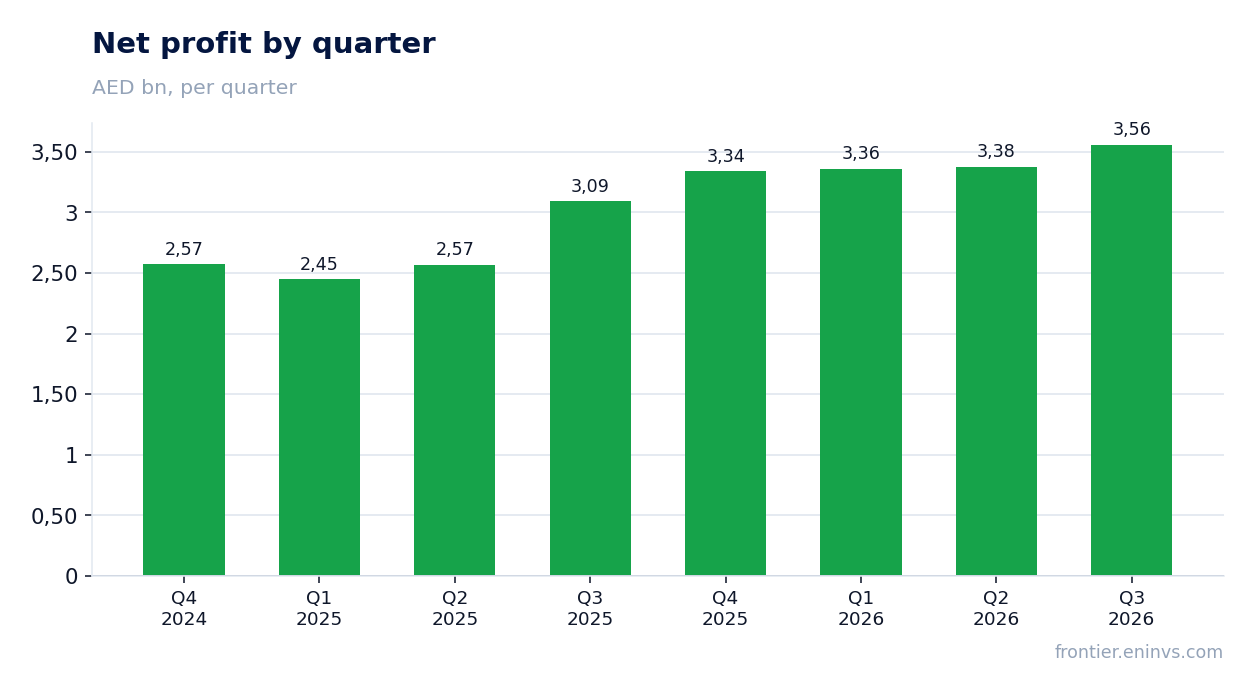
Quarterly profit rose 15.2%, but that is slower than the top line grew a year earlier
Net profit for the third quarter of 2026 came to AED 3,559 million, up 15.2% on the same quarter a year earlier. This is a standalone quarterly figure, not a nine-month cumulative one.
For comparison, the bank's top line grew 21.3% year on year in the second quarter of 2026, and the pace was roughly the same as in the first quarter. Profit is growing more slowly than revenue, which means part of the income is absorbed by costs or provisions.
The quarterly series confirms the steadiness: the bank earned AED 3,361 million in the first quarter of 2026, AED 3,376 million in the second and AED 3,559 million in the third. The growth is sequential, without dips, but also without a surge.
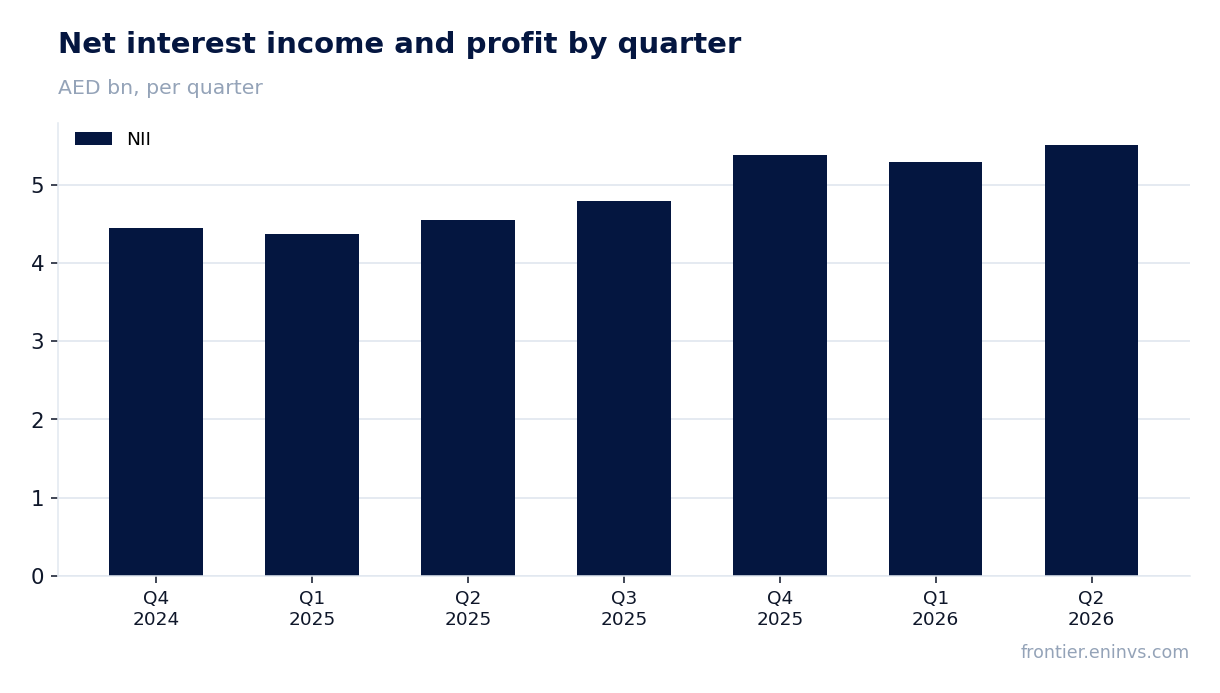
Trailing-twelve-month net interest income reached AED 21,000 million and remains the backbone of profit
Over the trailing twelve months the bank's net interest income came to AED 21,000 million. This is the core revenue line, and it covers the bulk of the AED 13,637 million profit earned over the same period.
The quarterly trend in net interest income is positive: AED 5,296 million in the first quarter of 2026 and AED 5,511 million in the second. The growth is even, without jumps, which matters more for a bank than one-off spikes.
The facts do not disclose fee and commission income, so revenue cannot be broken down by source. But the steady growth of net interest income shows the loan book is working and lending rates exceed the cost of funding.
A return on equity of 5.26% is low for a bank, and it is what caps the valuation
The bank's return on equity is 5.26%. For a banking business this is a modest level: it means the bank earns about five and a half fils for every dirham of capital.
At the same time, the P/E LTM is 9.67. The combination of a low return on equity and a moderate multiple suggests the market does not expect a sharp improvement in the return on capital.
Return on equity is the main constraint on the valuation. If it does not start rising, the multiple is unlikely to expand, even with steady profit growth.
A P/E LTM of 9.67 with the portal model's +11% upside offers no clear edge
The shares trade at a P/E LTM of 9.67 on a market capitalisation of AED 131,850 million. On the portal's model, which sets return on equity against price to book, the upside to fair value is +11%.
That is a moderate upside: it does not offset the risks tied to the low return on equity and to profit growing more slowly than revenue.
A comparison of the current multiple with its own three-year history is not possible: the facts do not include a three-year average. We therefore build the valuation on the absolute levels of P/E and ROE.
The dividend history is not disclosed in the facts, so we do not build the payout into the valuation
The facts contain no data on the bank's dividend payments over the last twelve months. We can neither confirm nor rule out a payout, so we do not include the dividend in the valuation.
For a bank with a return on equity of 5.26%, dividend policy would be an important anchor: with a low return on capital, the payout becomes the main way to return value to shareholders.
While this element is missing from the calculation, the portal model's +11% upside remains the only quantitative guide to attractiveness.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 132 bn AED |
| P/E (LTM) | 9.7 |
| P/B | 1.49 |
| ROE | 5.3% |
Bottom line
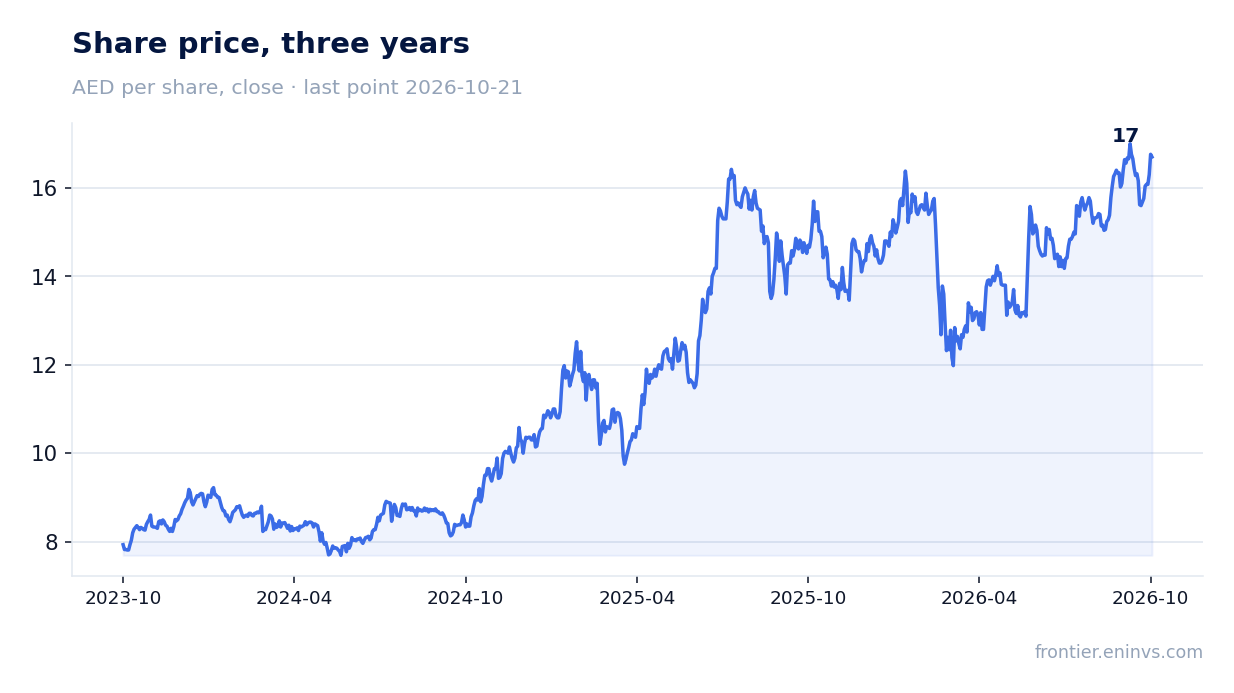
The strong side of the report is steady profit growth: AED 3,559 million in the third quarter, up 15.2% year on year, with a consistent three-quarter series and no dips. The weak side is the return on equity of 5.26%, which is low for a bank and caps the valuation. A P/E LTM of 9.67 and the portal model's +11% upside offer no clear edge in favour of buying. The dividend history is not disclosed in the facts, so we do not build the payout into the valuation. The verdict is neutral: the arguments for and against balance each other out.
Open the company's financial profile ADCB →
See also: market overview · valuation map · stock screeners