Dubai Islamic Bank: quarterly profit slipped 3.4% as net interest income fell below last year's level for the first time in a year
In its third-quarter 2026 report, Dubai Islamic Bank posted net profit of AED 1,799.7 million, down 3.4% year on year, on net interest income of AED 3,017.1 million, which fell 7.7% year on year. The slowdown from the second quarter's +1.7% marks the first negative reading in a year. With a P/E LTM of 6.87 and a trailing dividend yield of 4.87%, the share looks rather attractive than not, but weak net interest income is the main argument against.
Key takeaways
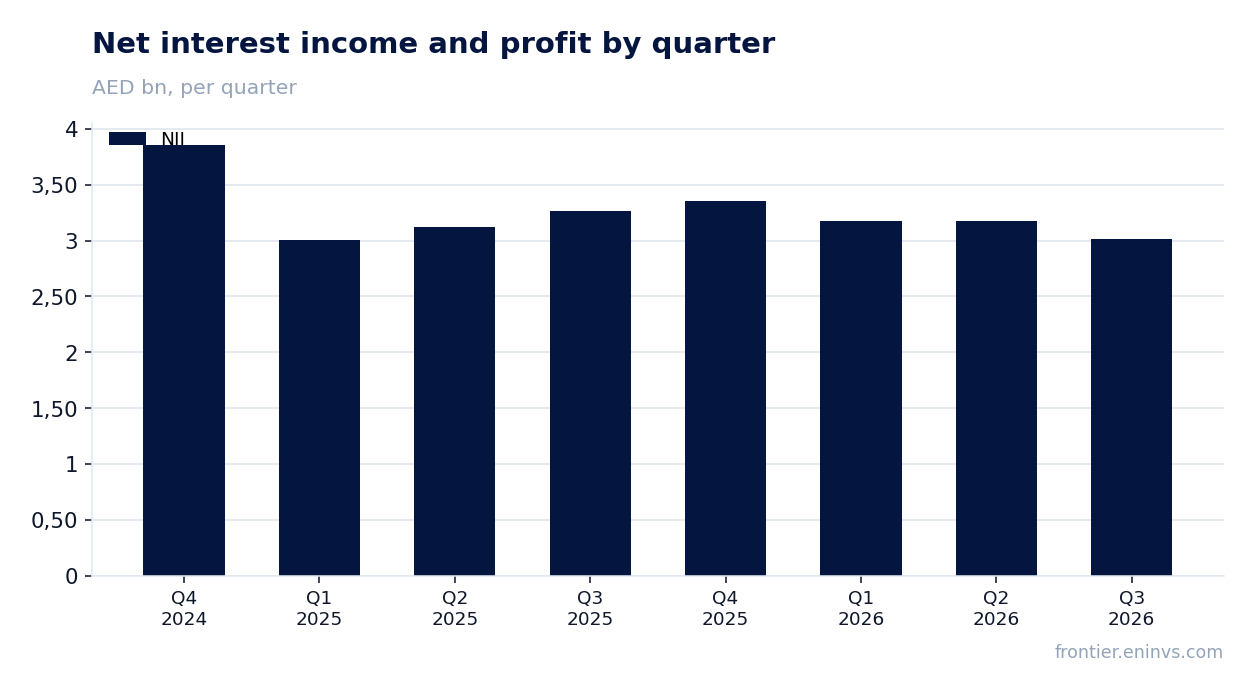
— Net interest income fell below last year's level for the first time in a year – down 7.7% year on year
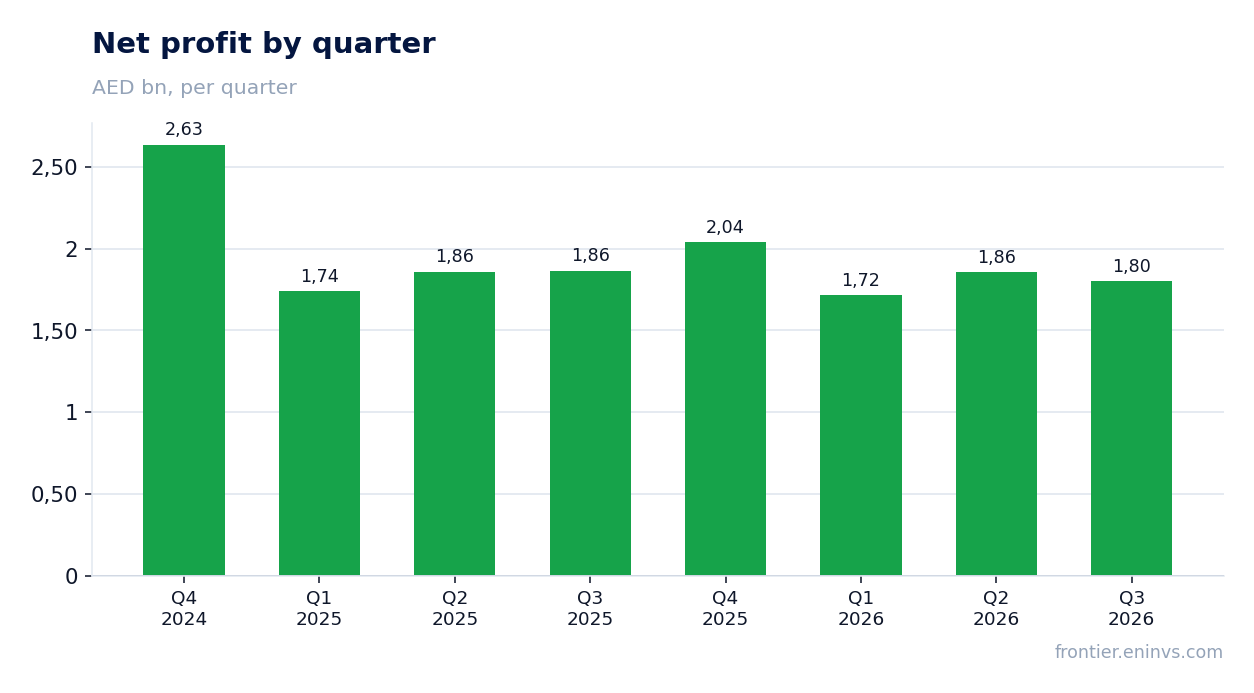
— Quarterly net profit shrank 3.4%, though it was still growing a quarter earlier
— P/E LTM of 6.87 is low for a bank with a 4.4% ROE, but profit is under pressure
— The 4.87% dividend yield rests on a payout supported by prior-period earnings
— On the portal's model, the share's upside to fair value is estimated at +14%
Attractiveness
Key figures, AED bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net interest income | 3.27 | — | — |
| Net profit | 1.86 | 1.80 | -3.4% |
| Capex | 0.35 | 0.21 | -41.0% |
| Net margin | 57.0% | — | — |
Net interest income fell below last year's level for the first time in a year – down 7.7% year on year
Net interest income in the third quarter of 2026 came to AED 3,017.1 million, 7.7% below the third quarter of 2025. This is the first negative reading in a year: in the second quarter of 2026 the figure was still growing at 1.7%, in the first at 5.5%, while in the fourth quarter of 2025 it fell 13.2%.
The decline in net interest income is a key signal for a bank whose top line consists almost entirely of interest income. If the fourth-quarter 2025 drop looked one-off, the negative dynamic has now repeated, and it no longer looks accidental. The facts do not disclose the cause, so we confine ourselves to stating it: income from core operations is contracting.
Quarterly net profit shrank 3.4%, though it was still growing a quarter earlier
Net profit for the third quarter of 2026 was AED 1,799.7 million, 3.4% below a year earlier. In the second quarter of 2026 profit was AED 1,855.9 million, in the first AED 1,716.1 million, so the quarterly dynamic is uneven, but profit broadly holds in a range of AED 1.7–1.9 billion.
A 3.4% profit decline against a 7.7% fall in net interest income means the bank partly offset weakness in its core income. The facts do not show how: the non-interest income and cost lines are not disclosed. For a holder, what matters is that profit has not collapsed, but it is not growing either.
P/E LTM of 6.87 is low for a bank with a 4.4% ROE, but profit is under pressure
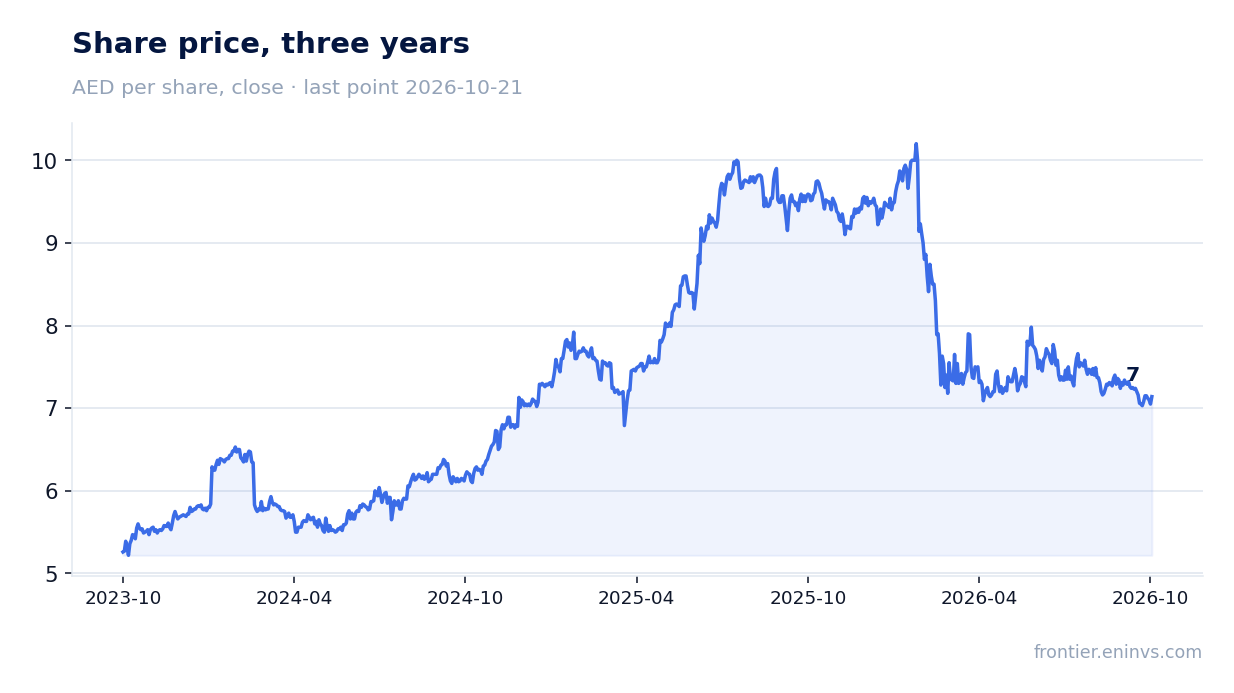
With a market capitalisation of AED 50,951.1 million and trailing-twelve-month profit of AED 7,411.2 million, the P/E LTM stands at 6.87. Return on equity is 4.38%, modest for a bank: the market prices earnings cheaply precisely because it does not expect sustained growth.
A comparison of the current P/E with its own three-year history is not possible – no such average is in the facts. Even so, it is clear the share trades below the level usually associated with a bank yielding around 5%. The discount is justified by weak net interest income, and until that turns, a re-rating should not be expected.
The 4.87% dividend yield rests on a payout supported by prior-period earnings
The trailing-twelve-month dividend yield is 4.87%. The payout rests on prior-period earnings: over the last twelve months the bank earned AED 7,411.2 million, enough to cover the dividend at a reasonable payout ratio.
However, third-quarter 2026 profit fell 3.4% and net interest income 7.7%. If that dynamic persists, the dividend base will start to shrink, and the 4.87% yield will come into question. For now the payout looks stable, but the margin of safety is not growing.
On the portal's model, the share's upside to fair value is estimated at +14%
On the portal's model, which sets annualised earnings against market capitalisation and ROE against P/B, the share's upside to fair value is estimated at +14%. This is our own estimate, not a market consensus and not a target price.
The model rests on current earnings, and those fell 3.4% in the third quarter. If profit keeps declining, the model will have to be revised down. For now it says that at a P/E of 6.87 and an ROE of 4.38% the share is undervalued relative to its own return.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 51.0 bn AED |
| P/E (LTM) | 6.9 |
| P/B | 0.96 |
| ROE | 4.4% |
| Dividend yield (12m) | 4.9% |
Bottom line
What was strong in the report is that profit held near AED 1.8 billion despite a 7.7% fall in net interest income. What was weak is net interest income itself: it fell below last year's level for the first time in a year, and this is no longer a one-off. The 4.87% dividend yield and 6.87 P/E look attractive, but they rest on profit that is not growing. The question for a holder now is whether net interest income turns in the next quarter; so far there are no signals of that.
Open the company's financial profile DIB →
See also: market overview · valuation map · stock screeners