e& (Etisalat): profit nearly quadrupled, but almost all of it is one-off
In its Q3 2026 report, e& (Etisalat) posted revenue of AED 19,464.0 mn, operating profit of AED 6,103.0 mn and net profit of AED 11,235.1 mn. Revenue growth slowed year-on-year to 4.5% from 6.4% a quarter earlier, while net profit jumped 276.2% – but with a net margin of 57.7% versus 16.0% a year ago, almost all of the gain came from one-off items rather than the operating business. The company also moved into a net cash position: net debt at 30 September 2026 stood at minus AED 19,268.9 mn. In our view the share looks rather attractive at the current price: EV/EBITDA of 5.15 is below its own history, and the portal's model implies +35% upside.
Key takeaways
— Revenue grew 4.5% year-on-year, but the pace slowed from 6.4% a quarter earlier
— Net profit of AED 11,235.1 mn is 276.2% above last year's, and almost all of the gain is one-off
— The 57.7% net margin versus 16.0% a year ago reflects one-off items, not an operating leap
— The company moved into a net cash position: net debt of minus AED 19,268.9 mn at 30 September 2026
— Operating cash flow of AED 11,334.0 mn covers capital expenditure of AED 2,187.8 mn almost fivefold
— EV/EBITDA of 5.15 and P/E of 12.9 are below their own history, and the portal's model implies +35% upside
— The next report will show whether revenue growth above 4% holds without one-off items
Attractiveness
Key figures, AED bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 18.6 | 19.5 | +4.5% |
| EBITDA | 8.19 | — | — |
| Operating profit | 5.40 | 6.10 | +13.1% |
| Net profit | 2.99 | 11.2 | +276.2% |
| Operating cash flow | 9.75 | 11.3 | +16.3% |
| Capex | 2.35 | -2.19 | -193.2% |
| EBITDA margin | 44.0% | — | — |
| Net margin | 16.0% | 57.7% | +41.7 pp |
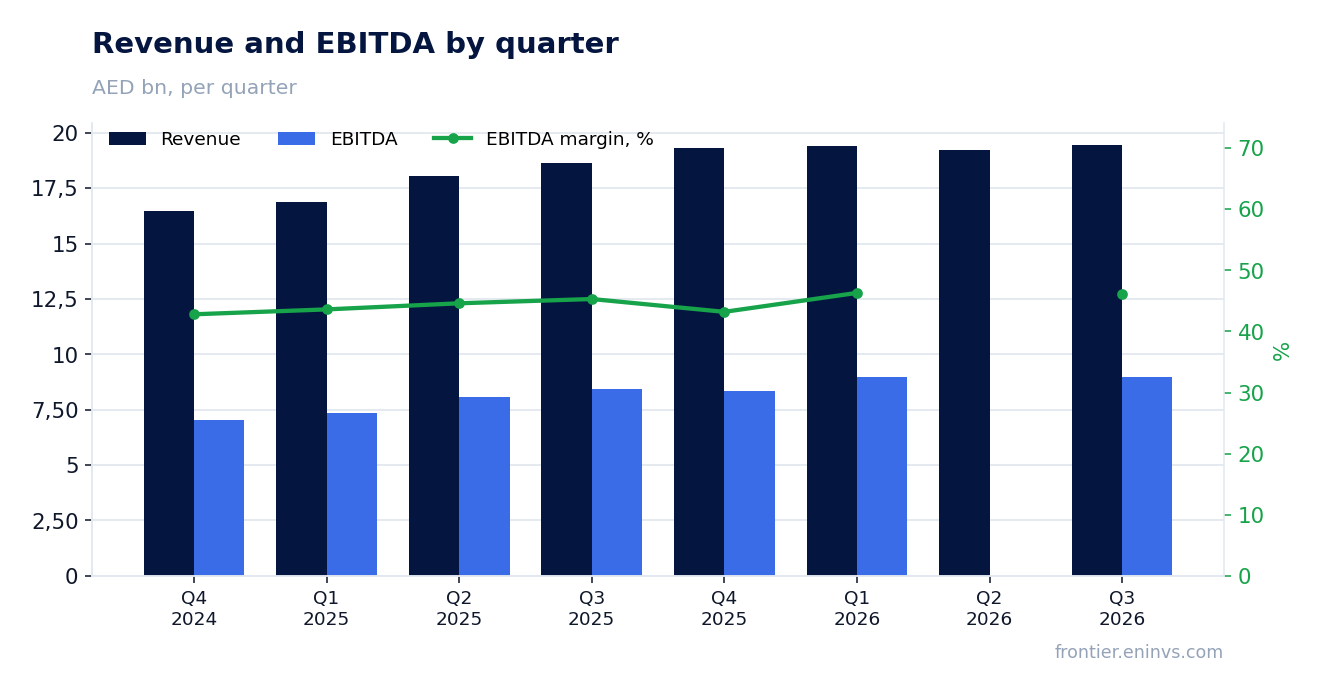
Revenue grew 4.5% year-on-year, but the pace slowed from 6.4% a quarter earlier
Revenue for Q3 2026 was AED 19,464.0 mn, 4.5% above the same quarter last year. A quarter earlier growth was 6.4%, so the pace has slowed. The deceleration has now run for two quarters: revenue grew 15.1% in Q1 2026 and 6.4% in Q2.
The absolute level has barely moved: AED 19,416.6 mn in Q1, AED 19,203.7 mn in Q2 and AED 19,464.0 mn in Q3. The company has plateaued at around AED 19.4 bn a quarter, and the annual growth now rests on a low base rather than on an acceleration in the business.
For an investor this means the operating momentum is weakening. To keep growth above 4%, the company needs either faster subscriber additions, higher tariffs or a new revenue source. The report gives no data on any of these yet.
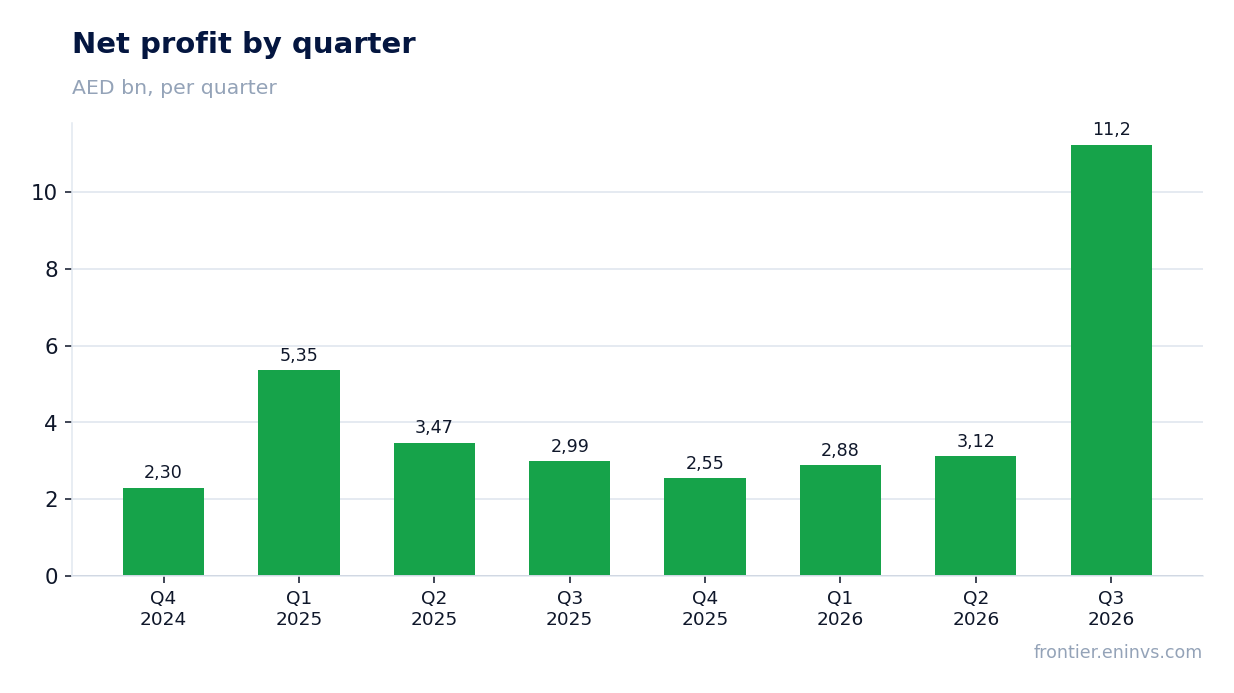
Net profit of AED 11,235.1 mn is 276.2% above last year's, and almost all of the gain is one-off
Net profit for Q3 2026 was AED 11,235.1 mn versus AED 2,986.3 mn a year earlier – growth of 276.2%. Operating profit, by contrast, rose only to AED 6,103.0 mn from AED 5,395.9 mn, or about 13%. The gap between operating and net profit dynamics is enormous.
This means almost all of the net profit gain came from lines below the operating line. The report does not disclose which items produced this effect, but the scale – more than AED 8 bn – cannot be the result of ordinary operations. Most likely it is a one-off gain from an asset sale or a revaluation, but the exact cause is not given in the facts.
To judge the sustainability of the business, one should look at operating profit. It grew 13% year-on-year – a healthy but far more modest result than the 276.2% on net profit.
The 57.7% net margin versus 16.0% a year ago reflects one-off items, not an operating leap
The net margin in Q3 2026 was 57.7% versus 16.0% in the same quarter last year. Such a jump, with revenue up only 4.5% and operating profit up 13%, can only be explained by one-off items below the operating line.
The operating margin remained stable: operating profit of AED 6,103.0 mn on revenue of AED 19,464.0 mn gives about 31.4%, versus 29.0% a year earlier. The 2.4 percentage point improvement is moderate and may reflect cost control, not one-off factors.
Investors should not extrapolate the 57.7% margin into future periods. The sustainable net margin is likely closer to 15–20%, judging by last year. One-off profit adds to equity but does not repeat quarter after quarter.
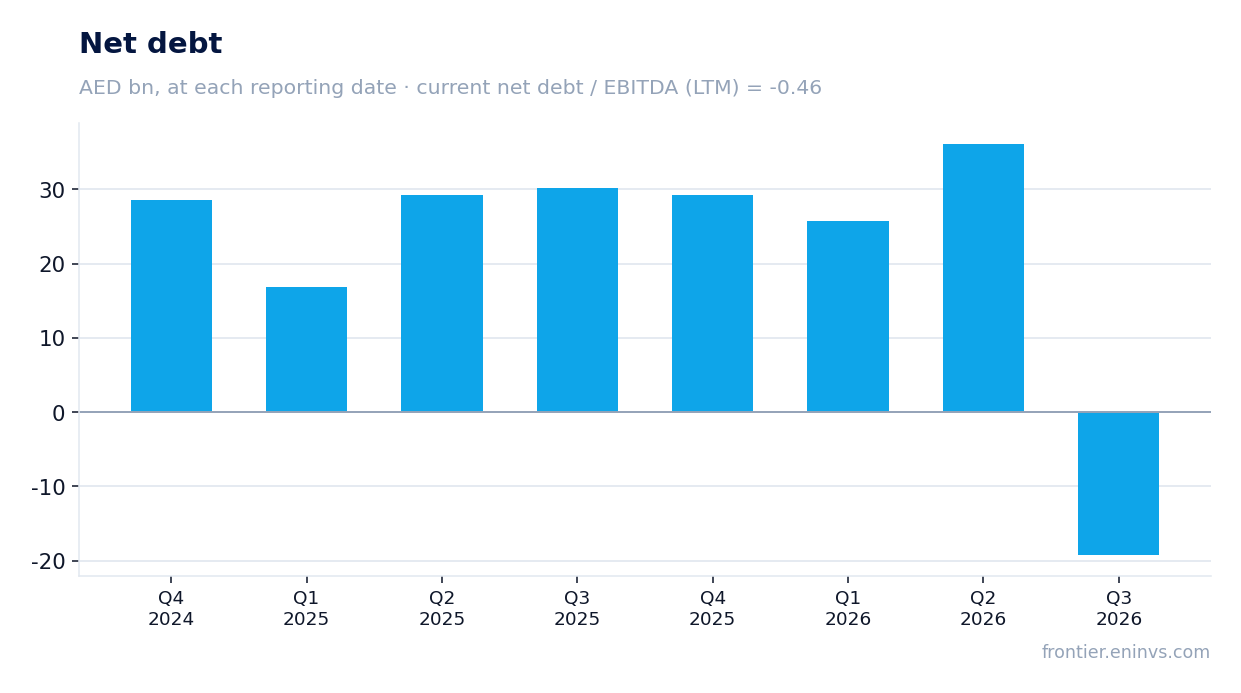
The company moved into a net cash position: net debt of minus AED 19,268.9 mn at 30 September 2026
Net debt at 30 September 2026 was minus AED 19,268.9 mn, meaning the company has a net cash position. This is a sharp change: net debt was AED 36,161.2 mn at 30 June 2026 and AED 30,170.8 mn at 30 September 2025. Over the quarter debt fell by AED 55.4 bn, over the year by AED 49.4 bn.
Such a reduction in debt, with operating cash flow of AED 11,334.0 mn for the quarter and capital expenditure of AED 2,187.8 mn, means the company used not only free cash flow but also proceeds from one-off transactions to pay down debt. Without one-off inflows, debt would not have fallen so much.
The ratio of net debt to EBITDA over the last twelve months is minus 0.46. This is a level, not a trend: we do not have an earlier value for this ratio, so we cannot say leverage rose or fell. But the net cash position itself is a strength of the balance sheet.
Operating cash flow of AED 11,334.0 mn covers capital expenditure of AED 2,187.8 mn almost fivefold
Operating cash flow for Q3 2026 was AED 11,334.0 mn, capital expenditure AED 2,187.8 mn. Free cash flow therefore exceeds AED 9 bn for the quarter. This is a very high figure for a company with revenue of AED 19.5 bn.
However, it should be remembered that operating cash flow includes one-off inflows related to the same transaction as the one-off profit. Without them, the flow would be closer to last year's level: AED 9,745.6 mn in Q3 2025. Even without one-off items, the company generates solid cash flow.
Capital expenditure remains moderate – about 11% of revenue. This allows the company to direct significant funds to debt repayment and dividends without increasing the burden on the balance sheet.
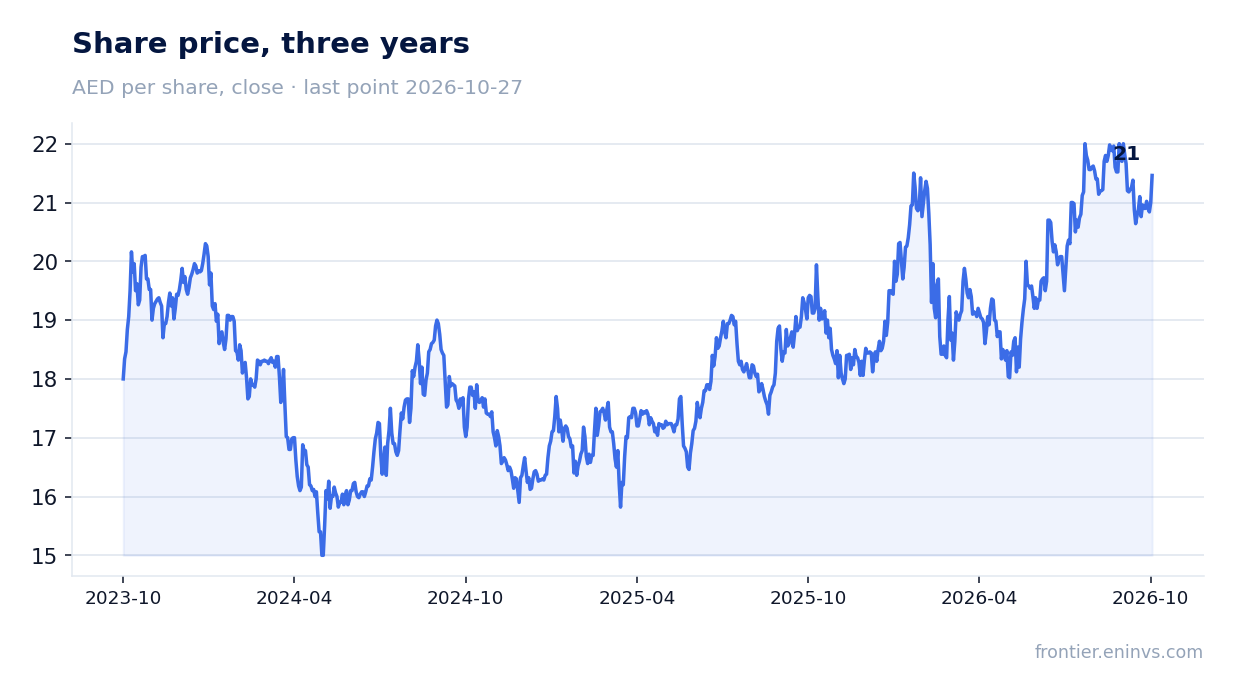
EV/EBITDA of 5.15 and P/E of 12.9 are below their own history, and the portal's model implies +35% upside
The EV/EBITDA multiple over the last twelve months is 5.15, P/E is 12.9. We do not have exact three-year historical averages, but both multiples look low for a telecom company with a net cash position and an EBITDA margin above 40%.
The portal's model, which compares EBITDA growth with a target multiple and market capitalisation, implies +35% upside to fair value. This is our own estimate, not a market consensus or a target price.
At the same time, trailing twelve-month profit includes one-off items that inflate the base. Adjusted for one-offs, P/E would be above 12.9 and the upside would be smaller. But even with this adjustment the share does not look overvalued.
The next report will show whether revenue growth above 4% holds without one-off items
The main question for the next report is revenue dynamics. The slowdown from 15.1% in Q1 to 4.5% in Q3 may continue, and then annual growth could fall below 4%. Investors should watch quarterly rates and whether the company can hold revenue around AED 19.5 bn.
The second question is the sustainability of the operating margin. If it stays around 31%, that will support profit. If revenue growth slows while costs remain unchanged, the margin could decline.
The third question is the recurrence of one-off income. If there are no similar inflows in Q4, net profit will return to a normal level, and the annual figure will be significantly lower than the current quarterly result suggests.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 185 bn AED |
| P/E (LTM) | 12.9 |
| EV/EBITDA (LTM) | 5.2 |
| P/B | 3.00 |
| Net debt / EBITDA (LTM) | -0.46 |
| Operating cash flow (LTM) | 19.2 bn |
| ROE | 22.6% |
Bottom line
The strong points of the report are the move into a net cash position and solid operating cash flow, which covers capital expenditure almost fivefold. However, net profit of AED 11,235.1 mn, up 276.2% year-on-year, is almost entirely due to one-off items, and revenue growth has slowed to 4.5%. EV/EBITDA of 5.15 and P/E of 12.9 are below their own history, and the portal's model implies +35% upside. In our view the share looks rather attractive at the current price, but the key question is the sustainability of revenue and profit without one-off effects.
Open the company's financial profile EAND →
See also: market overview · valuation map · stock screeners