Emirates NBD: Q3 2026 profit slipped 1.5% even as net interest income hit a record
In its Q3 2026 report Emirates NBD posted net profit of AED 6,326mn, down 1.5% year on year, while net interest income reached AED 13,674mn, the strongest quarter in the available history. Revenue grew 7.4% year on year, slower than the 12.1% pace of Q2. Over the trailing twelve months the bank earned AED 24,189mn on net interest income of AED 51,400mn; the stock trades at a P/E of 8.2 with a trailing dividend yield of 3.1%. On our reading the share looks rather attractive: the multiple is modest and the portal model implies +13% upside, but flat profit caps the case.
Key takeaways
— Net interest income rose to AED 13,674mn in Q3 2026, the highest in the available history and 7.4% above a year earlier
— Net profit fell 1.5% year on year to AED 6,326mn in Q3 2026, down from AED 6,416mn in the prior quarter
— Revenue growth decelerated: 7.4% in Q3 2026 versus 12.1% in Q2 2026
— Over the trailing twelve months the bank earned AED 24,189mn on net interest income of AED 51,400mn – profit is holding, not growing
— A P/E of 8.2 and a 3.1% dividend yield mark a moderate valuation, and the portal model implies +13% upside to fair value
— The 3.1% dividend yield is modest for a bank with a 5.2% ROE, and the payout is capped by earnings
Attractiveness
Key figures, AED bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net interest income | 12.7 | — | — |
| Net profit | 6.42 | 6.33 | -1.5% |
| Capex | 0.22 | 0.05 | -79.4% |
| Net margin | 50.4% | — | — |
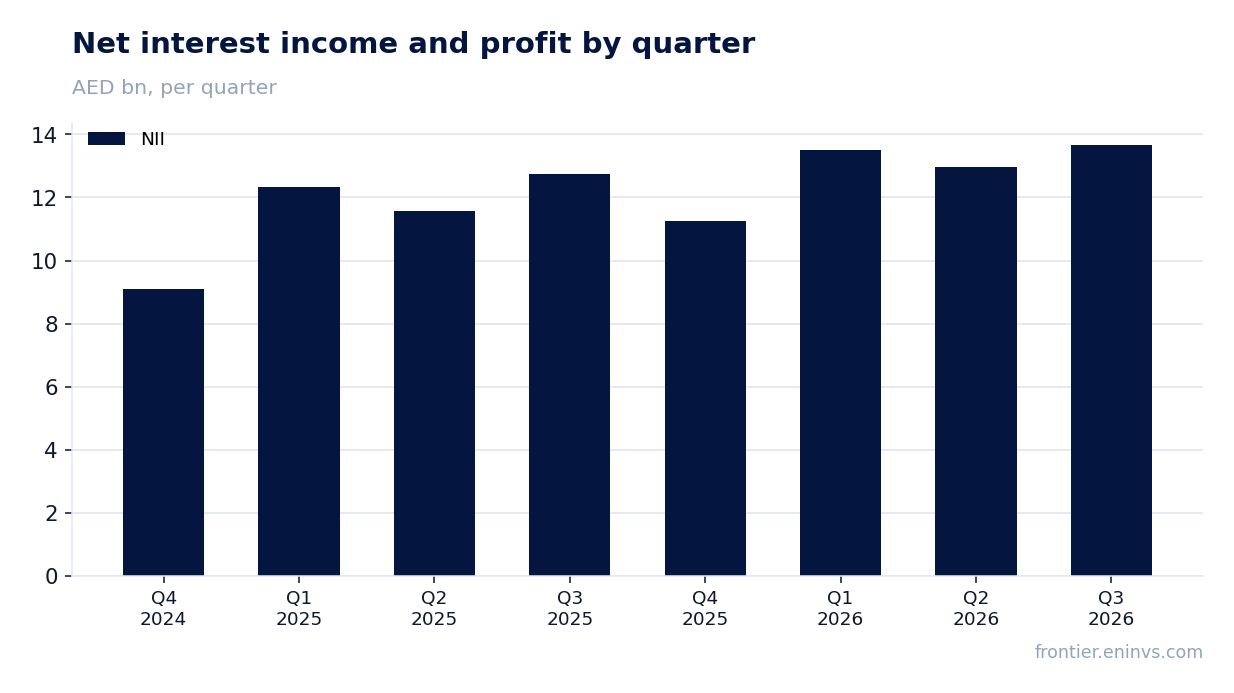
Net interest income rose to AED 13,674mn in Q3 2026, the highest in the available history and 7.4% above a year earlier
Net interest income is the bank's main revenue source, and in Q3 2026 it reached AED 13,674mn. That is the best quarterly result in the available history, ahead of the previous peak of AED 13,507mn in Q1 2026. Year on year the gain was 7.4%, supported by a stable lending base and funding costs.
The intra-year path is uneven: 13,507mn in Q1, 12,951mn in Q2, then back up to 13,674mn. Such swings are normal for a bank whose net interest income depends on asset volumes and the rates on them. Over the trailing twelve months net interest income was AED 51,400mn, the base from which profit is generated.
Growth of 7.4% in net interest income is modest but positive: the core business is expanding. On its own, though, it does not guarantee profit growth if costs or charges rise faster.
Net profit fell 1.5% year on year to AED 6,326mn in Q3 2026, down from AED 6,416mn in the prior quarter
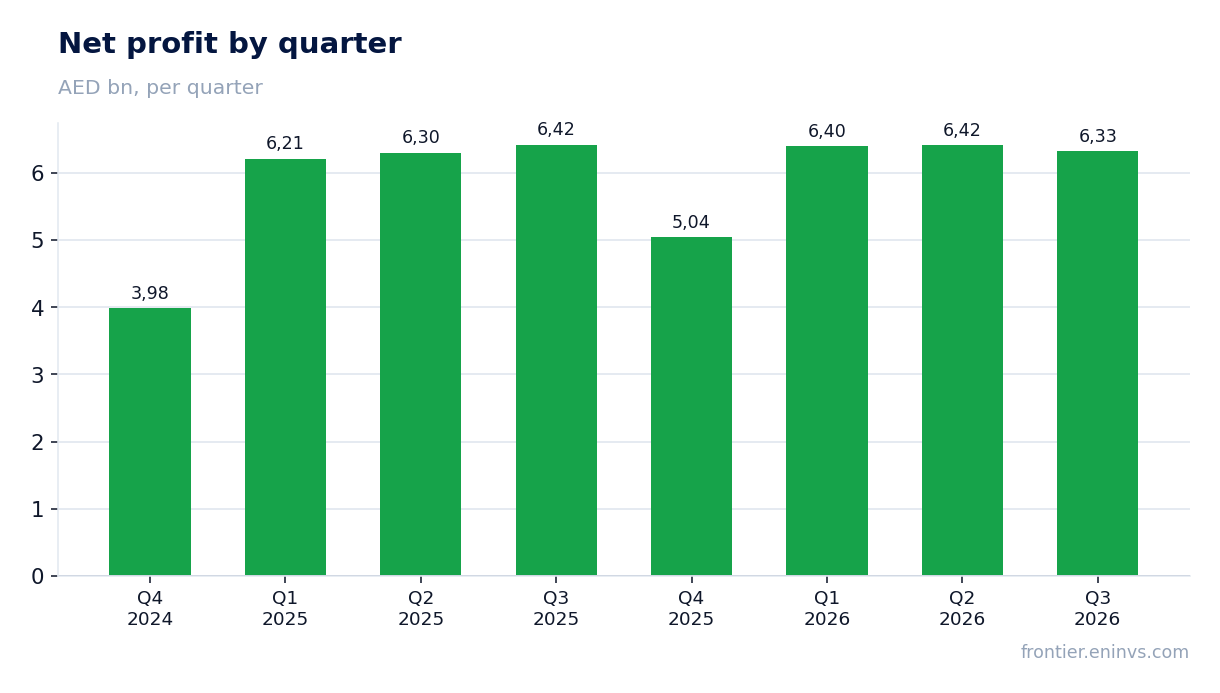
Net profit in Q3 2026 was AED 6,326mn, 1.5% below a year earlier. A decline against rising net interest income means costs or charges absorbed the gain, not weak revenue. Profit was AED 6,416mn in the prior quarter, so the drop shows up sequentially as well.
Over the trailing twelve months the bank earned AED 24,189mn. That sum is the base for dividends and for valuation. With a market cap of AED 199,478mn, the trailing P/E is 8.2 and ROE is 5.2%. For a bank that is a modest return on equity, and it explains why profit is not growing fast.
Profit sits in a narrow band: AED 6,214mn in Q1 2025, 6,301mn in Q2, 6,421mn in Q3, 5,045mn in Q4, then 6,402mn, 6,416mn and 6,326mn. The swings are small, but there is no upward trend. That is what caps the equity upside.
Revenue growth decelerated: 7.4% in Q3 2026 versus 12.1% in Q2 2026
Year on year net interest income grew 7.4% in Q3 2026, versus 12.1% in Q2. A near-halving of the growth rate is a meaningful signal: the core business is losing momentum. For a bank it means assets or the rates on them are expanding more slowly than a quarter earlier.
Earlier periods show that 12.1% in Q2 was no anomaly: growth was 9.6% in Q1 2026, 23.3% in Q4 2025 and 19.8% in Q3 2025. The current 7.4% is the slowest pace in recent quarters. The deceleration is sustained, not a one-off.
For a shareholder this matters: slower net interest income growth pressures profit, especially with stable or rising costs. The next report will show whether the slowdown continues or was a one-quarter dip.
Over the trailing twelve months the bank earned AED 24,189mn on net interest income of AED 51,400mn – profit is holding, not growing
Over the trailing twelve months Emirates NBD earned AED 24,189mn of net profit on net interest income of AED 51,400mn. The profit-to-net-interest-income ratio is about 47%, showing that a large part of revenue goes to costs and charges. That is normal for a bank, but the key point is that profit is not growing: it holds in a narrow band.
Return on equity over the trailing twelve months is 5.2%. That is a modest figure for a bank and explains the low valuation: a P/E of 8.2 on a 5.2% ROE means the market does not expect fast profit growth. At this level of profitability the bank cannot quickly build capital from retained earnings.
Trailing profit is the base for dividends. If it does not grow, payouts will be constrained too. That is the key limitation for an investor looking for income growth.
A P/E of 8.2 and a 3.1% dividend yield mark a moderate valuation, and the portal model implies +13% upside to fair value
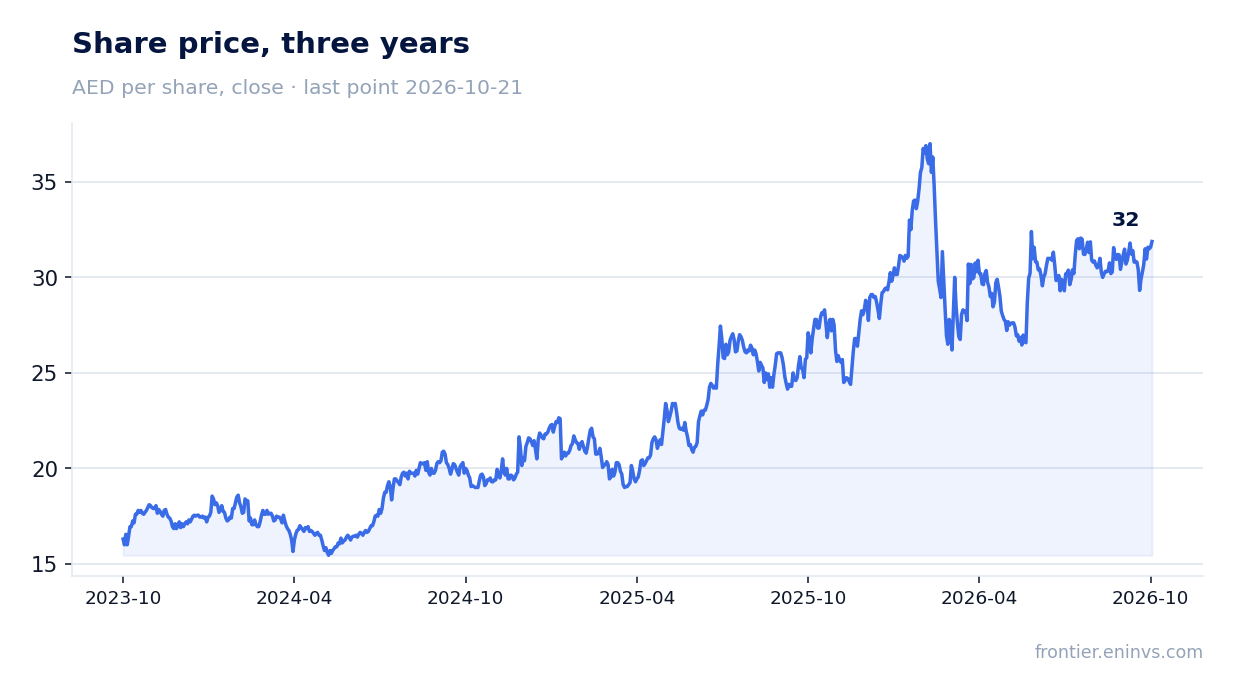
Emirates NBD trades at a trailing P/E of 8.2 on a market cap of AED 199,478mn. That is a modest multiple, but it matches a 5.2% ROE: the market pays little for earnings because it does not expect fast growth. The portal model puts fair value 13% above the current price – our own estimate, not a market consensus.
The trailing dividend yield is 3.1%. For a bank with a 5.2% ROE that is a moderate payout: neither generous nor stingy. The yield is lower than one might expect from a stock on this multiple, but it reflects constrained earnings.
Valuation looks fair: a P/E of 8.2 and 13% upside on the portal model leave room to rise, but not quickly while profit is flat. A re-rating needs either profit growth or a higher dividend yield.
The 3.1% dividend yield is modest for a bank with a 5.2% ROE, and the payout is capped by earnings
The trailing dividend yield is 3.1%. With trailing profit of AED 24,189mn and a market cap of AED 199,478mn, that implies roughly a quarter of earnings goes to dividends. For a bank that is a moderate share and leaves room to raise payouts if profit grows.
Profit, however, is not growing: it fell 1.5% year on year in Q3 2026. If profit stays at the current level, the dividend is unlikely to rise much. Our estimate for the current year is a payout close to last year's, but it hinges on the bank holding profit.
A 3.1% yield is lower than one might expect from a stock on a P/E of 8.2, but that is explained by the low return on equity. For an income-oriented investor this is a constraint: a higher yield needs either profit growth or a re-rating of the share.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 199 bn AED |
| P/E (LTM) | 8.2 |
| P/B | 1.38 |
| ROE | 5.2% |
| Dividend yield (12m) | 3.1% |
Bottom line
The strong point of the report remains net interest income: AED 13,674mn in Q3 2026, the highest in the available history. But profit fell 1.5% year on year to AED 6,326mn, and revenue growth decelerated to 7.4% from 12.1%. Valuation is moderate – a P/E of 8.2 and 13% upside on the portal model – but flat profit and a modest 3.1% dividend yield cap the upside. The verdict is rather attractive: the multiple is low, but a turn in profit dynamics is needed for the share to re-rate.
Open the company's financial profile EMIRATESNBD →
See also: market overview · valuation map · stock screeners