Bradesco: profit up by a third, but net interest income growth slowed to 11.7%
In its Q3 2026 report, Bradesco posted net profit of 1,384.0 million dollars, up 33.8% year on year, on net interest income of 14,606.1 million dollars. Net interest income growth slowed to 11.7% year on year from 29.6% in the prior quarter. With a trailing P/E of 5.85 and a return on equity of 15.3%, the share looks rather attractive than not, but the slowdown in the main income source needs confirmation that profit is sustainable.
Key takeaways
— Net profit rose 33.8% to 1,384.0 million dollars, but rests on cost reduction rather than faster income
— Net interest income grew 11.7% year on year, half the pace of the previous quarter
— A 15.3% return on equity at a P/E of 5.85 leaves a margin of safety in the valuation
— A trailing dividend yield of 11.0% remains the main argument for a holder
— The portal's model implies only 3% upside to fair value
— Capital expenditures of 397.0 million dollars stay moderate and do not threaten the dividend
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net profit | 1.03 | 1.38 | +33.8% |
| Capex | 0.38 | 0.40 | +5.4% |
Net profit rose 33.8% to 1,384.0 million dollars, but rests on cost reduction rather than faster income
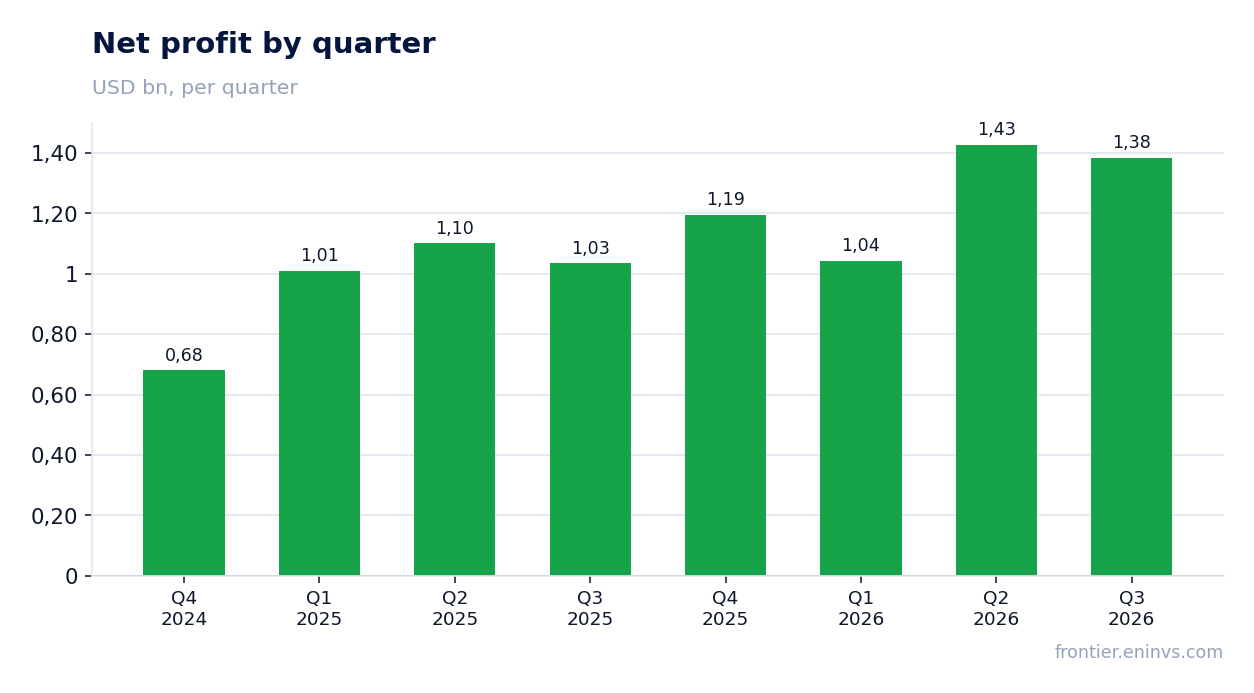
In Q3 2026, Bradesco's net profit was 1,384.0 million dollars, up 33.8% from the same quarter a year earlier. That is markedly faster than the 11.7% growth in net interest income over the same period. The gap between the two means profit was supported not by faster core income but by cost containment or lower credit-loss provisions.
That profit structure is less durable than growth driven by income. If cost savings are exhausted, the next quarter may show more modest profit growth at the current pace of net interest income. For a holder, this is the report's central question: how repeatable the quarter's profit will prove to be.
Net interest income grew 11.7% year on year, half the pace of the previous quarter
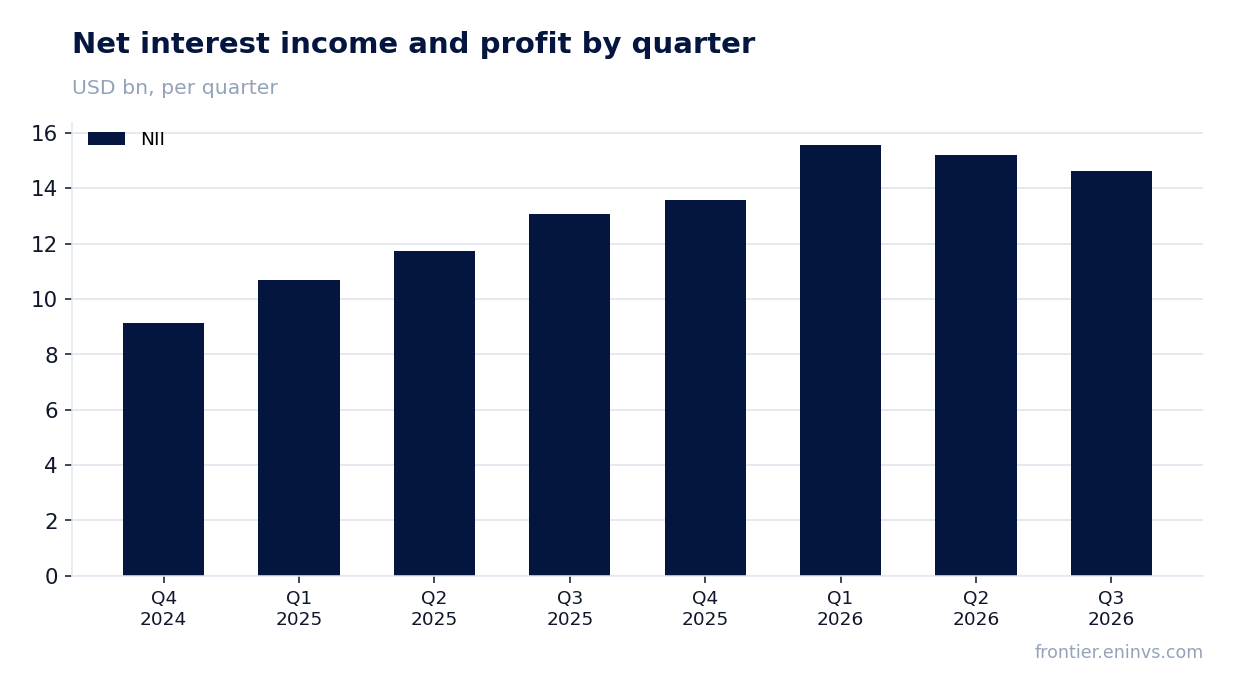
Net interest income in Q3 2026 was 14,606.1 million dollars. It grew 11.7% year on year, versus 29.6% in Q2. The near halving of the growth rate is the report's main signal, since net interest income is the bulk of a bank's revenue.
The slowdown is also visible sequentially: the figure fell from 15,182.0 million dollars in Q2. Some of that may reflect seasonality, but a sustained deceleration in the annual pace points to slower loan growth or margin compression. For the share, what matters is whether this trend reverses next quarter.
A 15.3% return on equity at a P/E of 5.85 leaves a margin of safety in the valuation
Bradesco's return on equity over the last twelve months was 15.3%, with a market capitalisation of 29,516.4 million dollars. At that return, a P/E of 5.85 means the market values the bank below its earnings power. That is typical for banks with slowing growth but leaves room for re-rating if income stabilises.
The portal's model, comparing return on equity with price to book, implies only 3% upside to fair value. That is a moderate guide: the share looks neither markedly undervalued nor overheated. The valuation supports the current level rather than promising significant gains.
A trailing dividend yield of 11.0% remains the main argument for a holder
Bradesco's trailing twelve-month dividend yield was 11.0%. That is a high yield which, at the current price, provides a substantial part of the share's total return. For a bank with a 15.3% return on equity, such a payout means a significant share of profit is returned to shareholders rather than retained to build capital.
Dividend sustainability depends on the bank's ability to hold profit. The slowdown in net interest income growth to 11.7% is the main risk to payouts: if profit stops growing, the dividend may be maintained from capital, but its growth will slow. At the current 11.0% yield, the share remains attractive for income-oriented investors but requires monitoring of profit dynamics.
The portal's model implies only 3% upside to fair value
On the portal's model, comparing return on equity with price to book, Bradesco's fair value is only 3% above the current price. That means the market already reflects the bank's current profitability, and further gains require improvement in fundamentals.
Such limited upside makes the share less interesting for investors expecting significant capital appreciation. The main contribution to return will come from dividends rather than re-rating. For a holder, this means the investment case should rest on payout sustainability, not on price growth.
Capital expenditures of 397.0 million dollars stay moderate and do not threaten the dividend
Bradesco's capital expenditures in Q3 2026 were 397.0 million dollars. That is a moderate level that does not pressure dividend payouts. For a bank, capex is mainly tied to technology infrastructure and is not the primary consumer of capital.
Against net profit of 1,384.0 million dollars, capex is less than a third of profit, leaving ample room for shareholder payouts. However, the sustainability of the 11.0% dividend will depend on the bank's ability to maintain profit at the current level, not on capex.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 29.5 bn USD |
| P/E (LTM) | 5.8 |
| P/B | 0.90 |
| ROE | 15.3% |
| Dividend yield (12m) | 11.0% |
Bottom line
The strong point of Bradesco's Q3 2026 report was net profit of 1,384.0 million dollars, up 33.8% year on year, and a 15.3% return on equity. However, profit growth outpaced net interest income growth, which slowed to 11.7%, suggesting possible reliance on one-off factors. The 11.0% dividend yield remains the main argument for a holder, but its sustainability depends on the bank's ability to hold profit. At a P/E of 5.85 and with only 3% upside on the portal's model, the share looks rather attractive but without significant room for growth.
Open the company's financial profile BBDC →
See also: market overview · valuation map · stock screeners