Albemarle: profit tripled on lithium prices, but next quarter's margin will be squeezed by costly feedstock
On November 4 Albemarle Corporation reported third-quarter 2026 results: revenue of $1,553.1 million (+18.8% year on year), adjusted EBITDA of $645.5 million (+186.1%), and net income of $296.8 million against a $160.7 million loss a year earlier. Profit was driven mainly by a doubling of realised lithium prices in Energy Storage rather than volumes: segment sales in tonnes fell 18.8%. The stock added 4.9% on the release day, but the portal's model puts the upside to fair value at minus 8%, so the share looks neutral: a strong quarter is already priced in, and the next one promises margin compression.
Key takeaways
— Revenue rose 18.8%, but growth decelerated from 31.1% a quarter earlier
— Profit tripled on a doubling of lithium prices, not on volumes
— Adjusted EBITDA of $645.5 million is nearly double our $316.6 million EBITDA because of the Talison stake
— Net debt fell from $3.0 billion to $0.3 billion in the quarter after $1.3 billion of debt was repaid
— Free cash flow of $325 million covered dividends and debt reduction
— An EV/EBITDA of 9.0x leaves little cushion at a lithium price near $10/kg
— A 1.7% dividend yield is modest against the key rate and does not shield from the cycle
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 1.31 | 1.55 | +18.8% |
| EBITDA | 0.13 | 0.32 | +146.2% |
| Operating profit | -0.22 | 0.15 | to profit |
| Net profit | -0.16 | 0.30 | to profit |
| Operating cash flow | 0.36 | 0.41 | +14.1% |
| Capex | 0.13 | 0.08 | -39.2% |
| EBITDA margin | 9.8% | 20.4% | +10.6 pp |
| Net margin | -12.3% | 19.1% | +31.4 pp |
Revenue rose 18.8%, but growth decelerated from 31.1% a quarter earlier
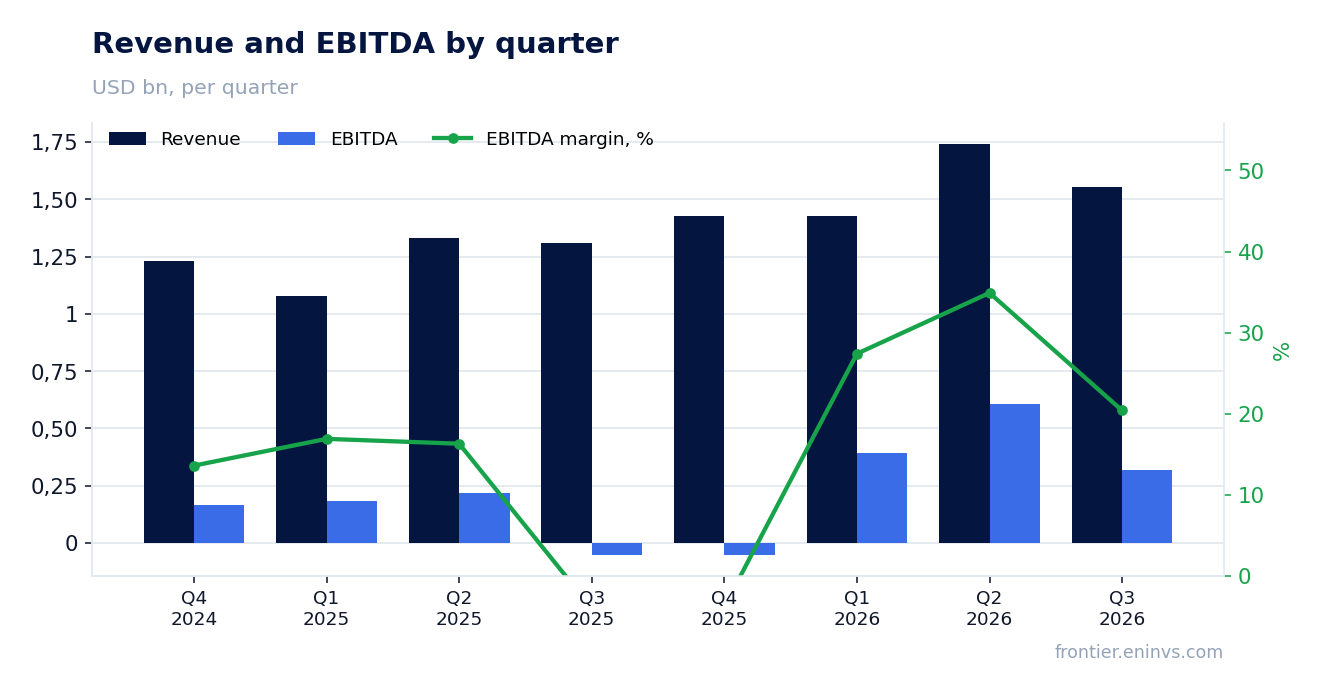
Third-quarter revenue was $1,553.1 million, up 18.8% year on year. The deceleration is visible: growth was 31.1% in the second quarter and 32.7% in the first. The company attributes the dynamic to price: in Energy Storage the average realised price rose to $20.02/kg on a lithium carbonate equivalent basis from $10.28/kg a year earlier, nearly double.
Volumes fell: Energy Storage sales were 56 kt against 69 kt a year earlier, down 18.8%. The release says the cause was a base effect – the third quarter of 2025 was the segment's record volume quarter because of inventory destocking and higher-than-usual spodumene shipments. Revenue growth is therefore entirely price-driven, not physical.
Specialties added 12.7% to revenue, to $388.6 million, on price (+10%) and volumes (+3%). It is the smaller but steadier segment: it grows even without a lithium price spike.
Profit tripled on a doubling of lithium prices, not on volumes
Net income was $296.8 million against a $160.7 million loss a year earlier. The net margin rose to 19.1% from minus 12.3%. Last year's quarter was hit by a $181.1 million goodwill impairment and weak lithium prices – both factors are gone.
Adjusted earnings per share were $2.58 against minus $0.19 a year earlier. The gap between net and adjusted profit is small: the company excluded $56.1 million of one-off items, mainly restructuring and cost-savings programme costs. Profit this quarter is therefore mostly operating, not accounting-driven.
Energy Storage was the main contributor: its adjusted EBITDA rose to $559.8 million from $124.1 million. Specialties added $98.7 million against $75.5 million. Profit rests on price, and that is the main risk: price is a variable the company does not control.
Adjusted EBITDA of $645.5 million is nearly double our $316.6 million EBITDA because of the Talison stake
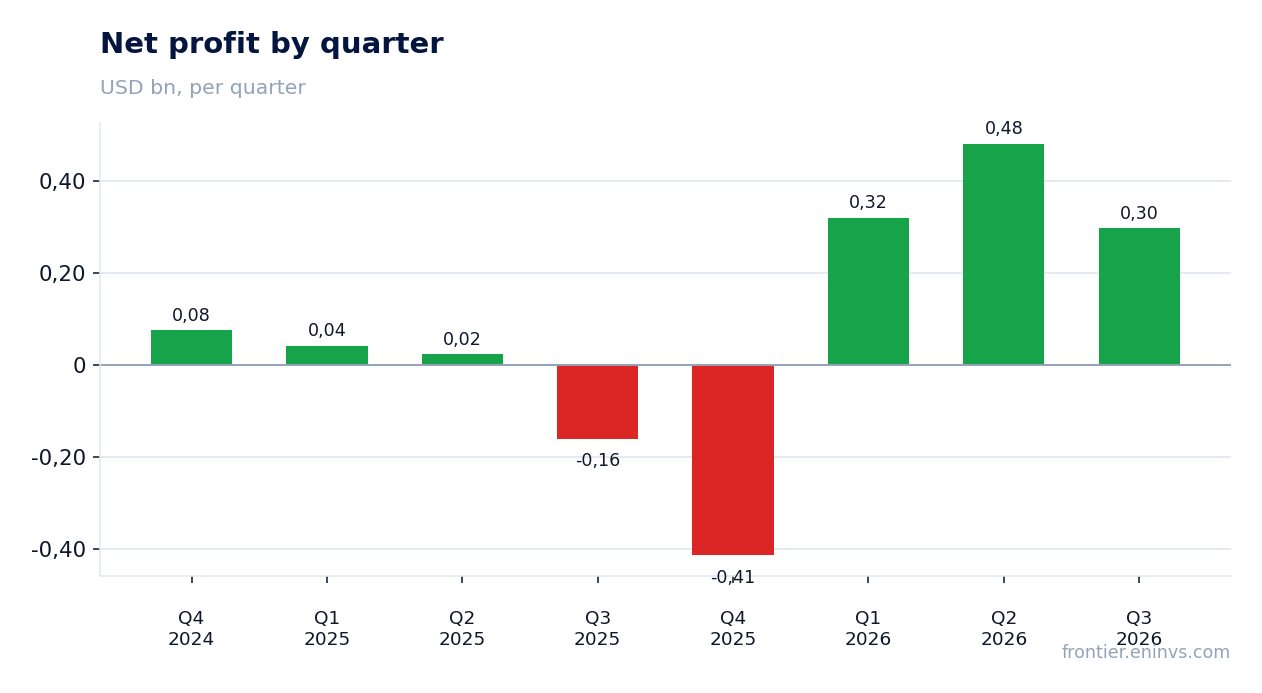
The company's adjusted EBITDA was $645.5 million, up 186.1% year on year. Our reported EBITDA is $316.6 million, and the gap is methodological: the company adds its share of profit from the Talison joint venture, which arrives as dividends and equity income rather than operating revenue.
The release shows the difference: equity in net income of unconsolidated investments was $205.4 million, and the proportionate share of Windfield income tax was $85.4 million. Both are in adjusted EBITDA but not in ours. When comparing with multiples, remember the company's base is wider.
The adjusted EBITDA margin was 41.6% against 17.3% a year earlier. That level rests on the lithium price; the release says directly that fourth-quarter margin will decline because of higher-cost spodumene purchased earlier.
Net debt fell from $3.0 billion to $0.3 billion in the quarter after $1.3 billion of debt was repaid
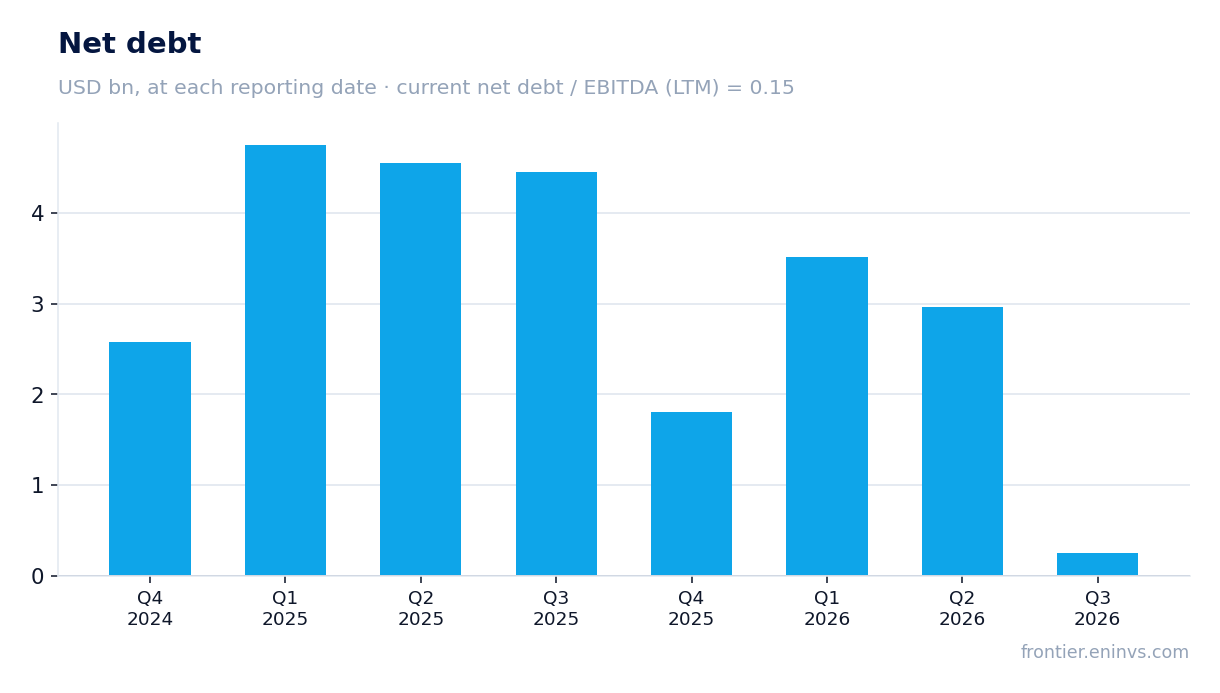
Net debt at September 30, 2026 was $256.0 million. At June 30 it was $3.0 billion, so it fell by $2.7 billion in the quarter. A year earlier, at September 30, 2025, it was $4.5 billion – a decline of $4.2 billion over 12 months.
The reduction came from cash flow and debt repayment: in nine months the company repaid $1,331.2 million of long-term debt and raised only $53.0 million. The release also mentions a discounted debt buyback that produced a one-off gain of $12.5 million.
The ratio of net debt to trailing-twelve-month EBITDA is 0.15. That is a low level, but it cannot be compared with last year: the facts contain no earlier value. The company estimates liquidity at $3.4 billion, including $1.8 billion of cash.
Free cash flow of $325 million covered dividends and debt reduction
Operating cash flow for the quarter was $405.8 million, and free cash flow was $325 million. Operating cash flow conversion of 63% was supported by a dividend from Talison that partly offset working-capital changes.
Capital expenditure was $80.4 million in the quarter and $250.8 million in nine months, $184 million less than a year earlier. The company cut its 2026 capex forecast to $300–350 million from about $500 million, citing efficiency and resequencing of early-stage projects.
Free cash flow in nine months was $1.2 billion. That covered both dividends and debt repayment. But the flow depends on the lithium price: at a scenario near $10/kg the company expects full-year adjusted EBITDA of only $0.9–1.0 billion against $2.4–2.6 billion at $20.
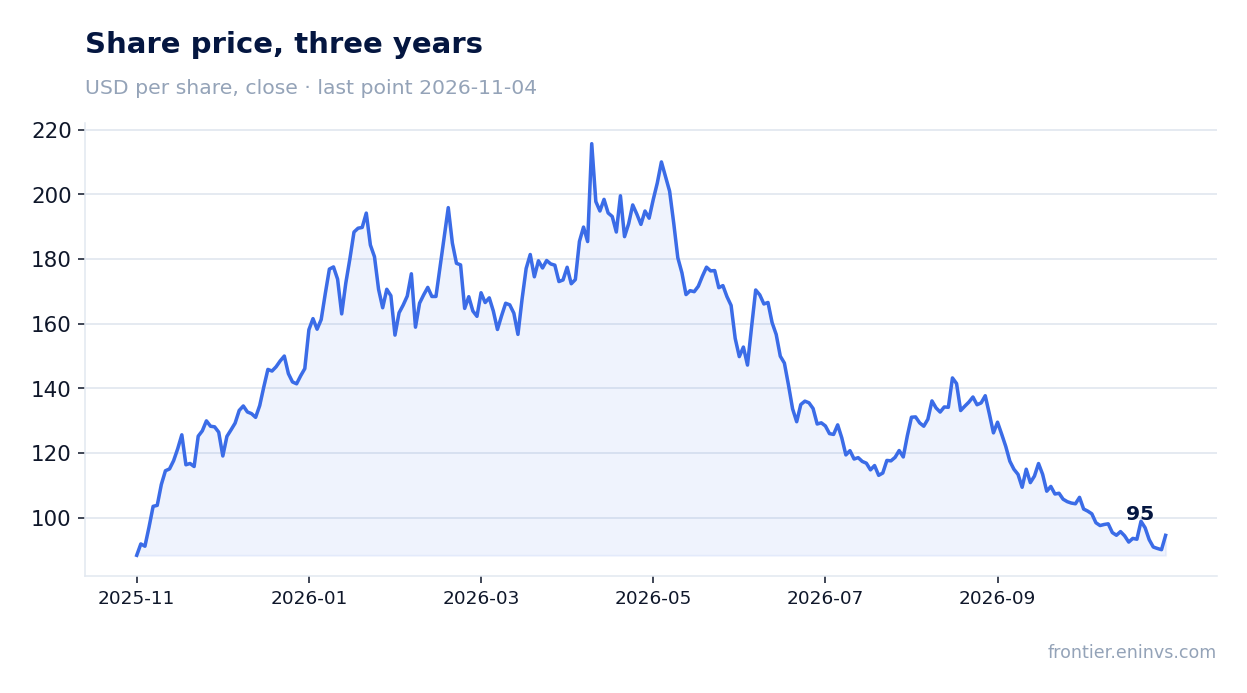
An EV/EBITDA of 9.0x leaves little cushion at a lithium price near $10/kg
EV/EBITDA over the last 12 months is 9.0x, and P/E is 16.4. Return on equity is 11.4%. The multiples look moderate, but the EBITDA base includes the Talison stake and is calculated at high lithium prices.
The release gives three scenarios for 2026. At an average price near $10/kg adjusted EBITDA is expected at $0.9–1.0 billion, at $20 it is $2.4–2.6 billion, and at $30 it is $4.2–4.4 billion. The current price is closer to the low scenario, and at that level a 9.0x multiple no longer looks cheap.
On the portal's model the share trades 8% above fair value at current commodity prices. That is our own estimate, not a consensus. It says the market is pricing a recovery in lithium prices rather than the current level.
A 1.7% dividend yield is modest against the key rate and does not shield from the cycle
The trailing-twelve-month dividend yield is 1.7%. In nine months the company paid $143.2 million of common dividends and $125.1 million on preferred stock. Payments are stable but not growing: common dividends a year earlier were $142.9 million.
Our estimate for the current year is a yield of about 1.7% at a share price of $90.19. It rests on profit, and profit depends on the lithium price. At a $10/kg scenario full-year EBITDA falls to $0.9–1.0 billion, and the payout becomes sensitive to cash flow.
The yield is modest against the key rate and does not compensate for cyclicality. For a holder the dividend here is a pleasant extra rather than a reason to buy the stock.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 11.2 bn USD |
| P/E (LTM) | 16.4 |
| EV/EBITDA (LTM) | 9.0 |
| P/B | 1.14 |
| Net debt / EBITDA (LTM) | 0.15 |
| Operating cash flow (LTM) | 1.85 bn |
| ROE | 11.4% |
| Dividend yield (12m) | 1.7% |
Bottom line
The strong side of the report is cash flow and the balance sheet: free cash flow of $325 million, net debt cut to $0.3 billion, and a ratio to EBITDA of 0.15. But profit tripled on a doubling of lithium prices while volumes fell 18.8%, and the company itself warns of margin compression next quarter. A 9.0x multiple and the portal's minus 8% estimate say the market has already priced in a price recovery. The verdict is neutral: the share is fairly valued at the current lithium price, and an improvement needs either a higher price or sustained volume growth.
Open the company's financial profile ALB →
See also: market overview · valuation map · stock screeners