Amerigo Resources: revenue up 61.2% while EBITDA jumped 154% on the same sales pace
On 25 November Amerigo Resources reported results for the third quarter of 2026. Revenue came in at $84.6 million (+61.2% year on year), EBITDA at $43.7 million (+154.0%) and net profit at $22.7 million (+240.3%). Top-line growth was roughly the same pace as in the second quarter (+61.1%), while the EBITDA margin rose to 51.7% from 32.8% a year earlier. At an EV/EBITDA of 6.0 against its own three-year average of 3.9 the share is more expensive than its history, so the verdict is neutral.
Key takeaways
— Revenue added 61.2% at a pace roughly unchanged from the second quarter
— EBITDA grew 154.0%, faster than revenue, lifting the margin to 51.7%
— Net profit rose 240.3%, with the net margin reaching 26.8%
— Operating cash flow of $32.6 million covers profit and needs almost no capital
— A 9.6% dividend yield rests on payouts funded by high profit
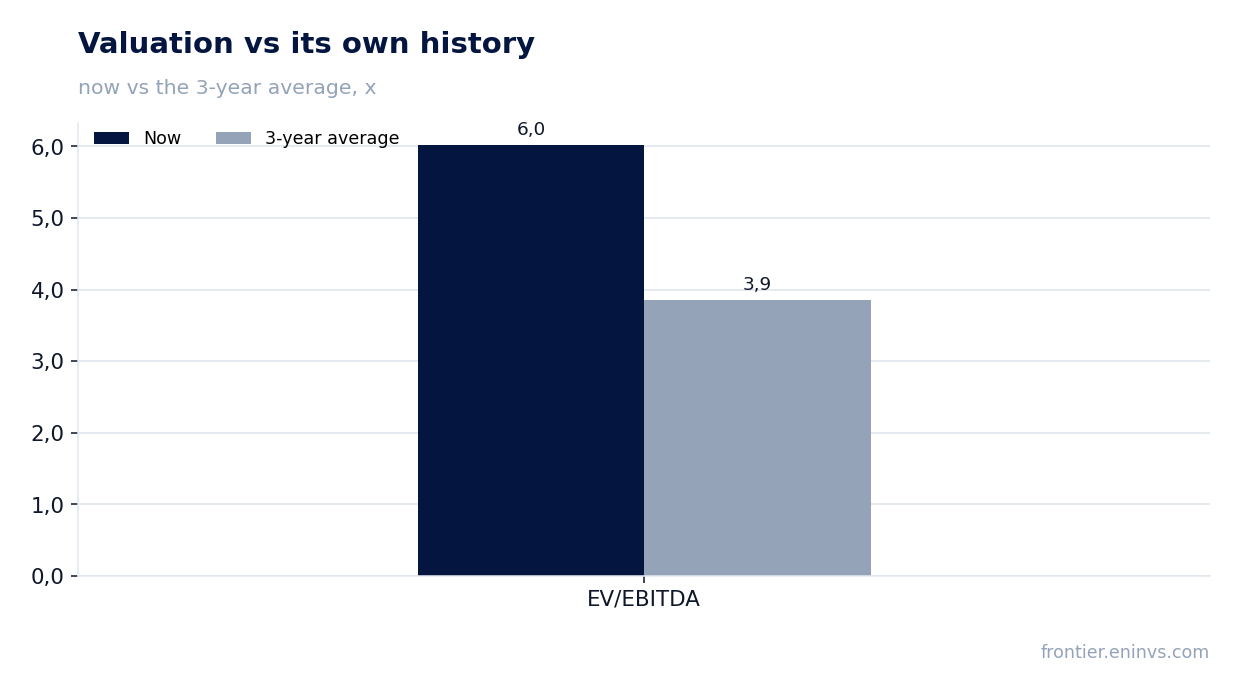
— EV/EBITDA of 6.0 against its own three-year average of 3.9 – the share is above its history
— The portal's model implies +15% upside to fair value
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 0.05 | 0.08 | +61.2% |
| EBITDA | 0.02 | 0.04 | +154.0% |
| Operating profit | 0.01 | 0.04 | +226.7% |
| Net profit | 0.01 | 0.02 | +240.3% |
| Operating cash flow | 0.01 | 0.03 | +175.0% |
| EBITDA margin | 32.8% | 51.7% | +18.9 pp |
| Net margin | 12.7% | 26.8% | +14.1 pp |
Revenue added 61.2% at a pace roughly unchanged from the second quarter
In the third quarter of 2026 revenue reached $84.6 million, 61.2% more than a year earlier. Growth in the second quarter was 61.1%, so the pace was roughly the same: the company has held a high sales base for two quarters in a row.
The absolute level is below the second quarter ($120.3 million) but above the third quarter of 2025 ($52.5 million). Seasonality or one-offs are not disclosed in the figures, so we simply note that the quarter is weaker than the previous one but clearly stronger than a year ago.
Further growth will depend less on the comparison base than on copper prices and production volumes, which are not in the reported block. For now the revenue trend confirms that demand and prices remain high.
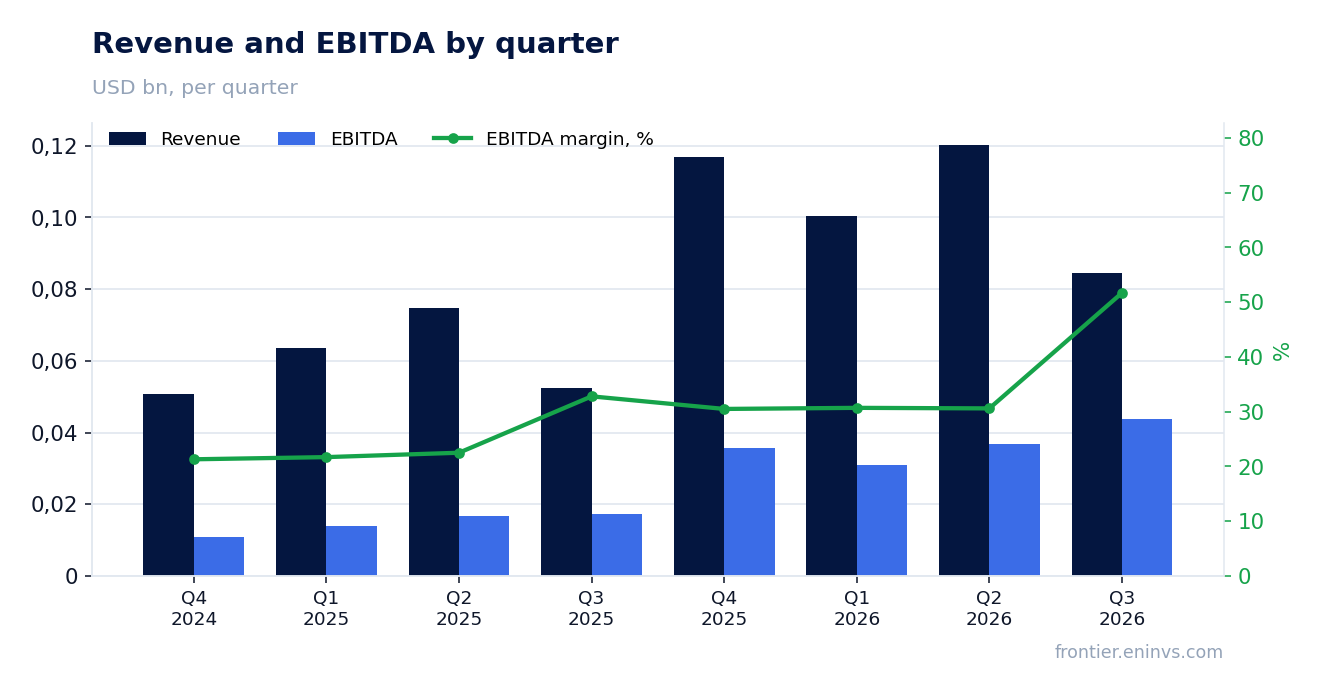
EBITDA grew 154.0%, faster than revenue, lifting the margin to 51.7%
EBITDA for the third quarter of 2026 was $43.7 million, 154.0% more than a year earlier. Growth faster than revenue means costs barely rose with sales.
The EBITDA margin rose to 51.7% from 32.8% a year earlier. That is a very high level for a mining company: more than half of revenue remains before depreciation and interest.
Operating profit was $37.6 million, so depreciation in the quarter was small. The main driver of the margin was copper prices rather than cost cuts – the reported block gives no breakdown of cost lines.
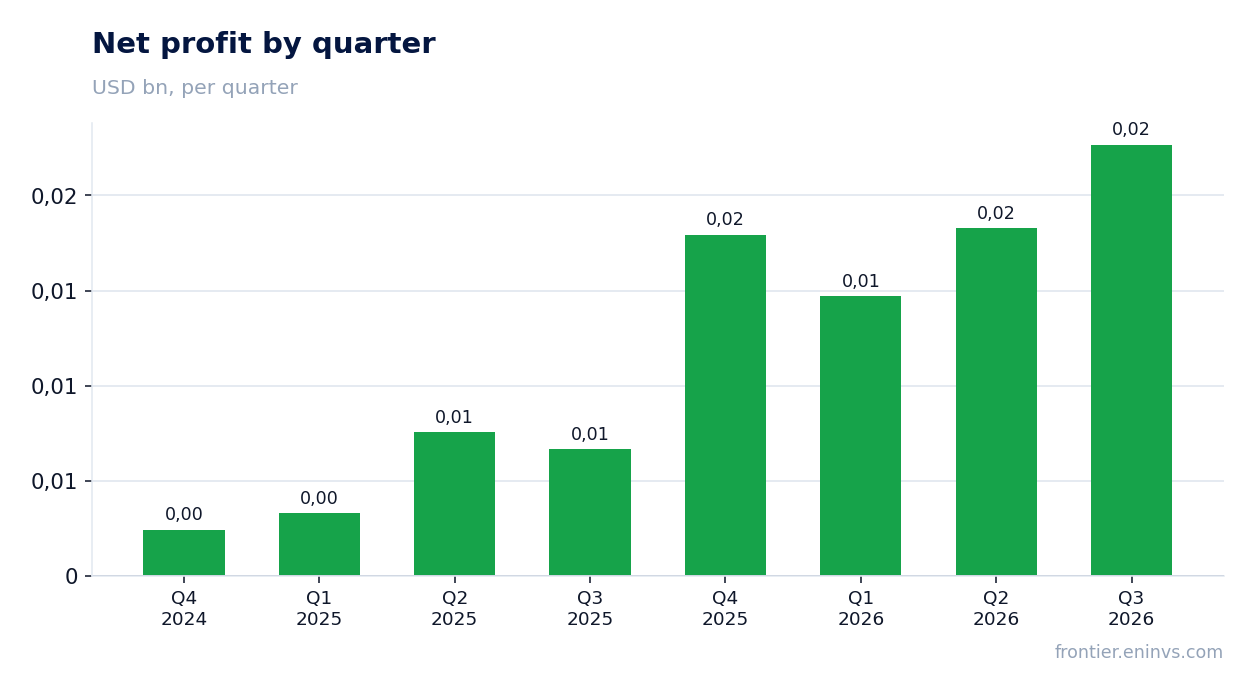
Net profit rose 240.3%, with the net margin reaching 26.8%
Net profit for the third quarter of 2026 was $22.7 million, 240.3% more than a year earlier. The net margin reached 26.8% from 12.7% a year earlier.
Profit growing faster than EBITDA reflects interest and taxes not rising proportionally. No one-off items are disclosed in the reported block, so the profit looks operational rather than the result of asset sales.
Over the last twelve months net profit was $73.6 million – the base on which the dividend rests.
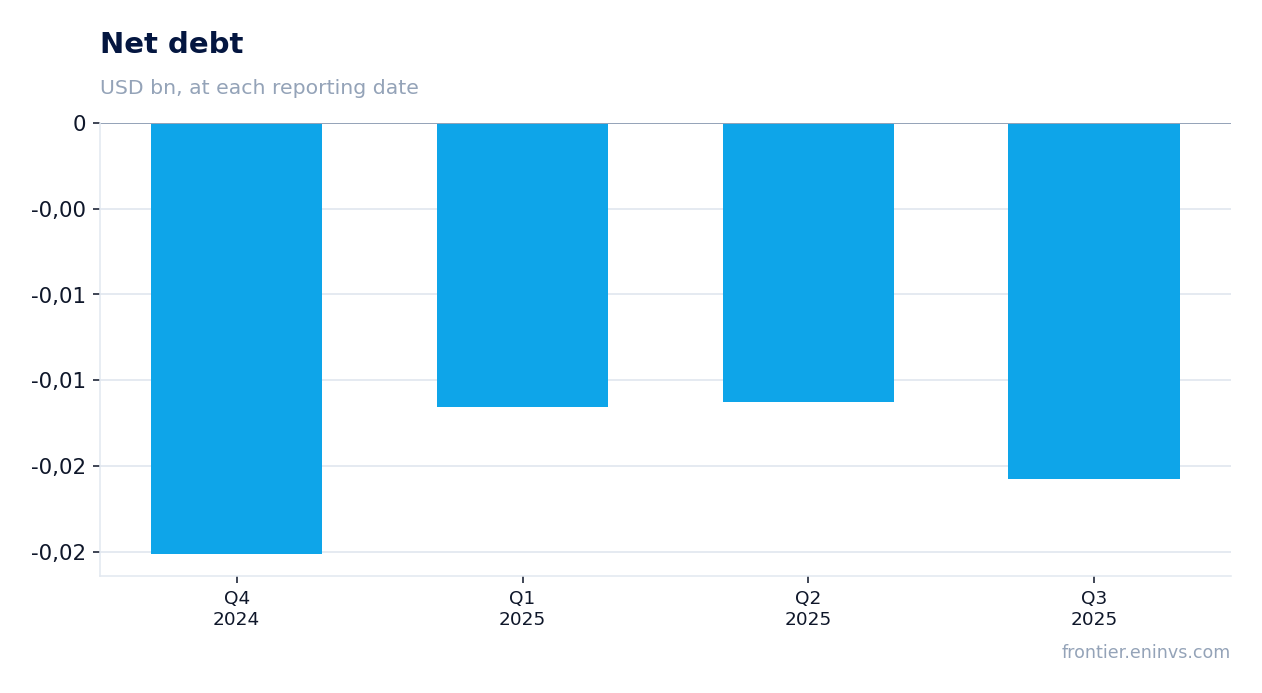
Operating cash flow of $32.6 million covers profit and needs almost no capital
Operating cash flow for the third quarter of 2026 was $32.6 million, above net profit of $22.7 million. Profit is therefore backed by cash rather than a build-up of receivables.
Over the last twelve months operating cash flow was $119.4 million on revenue of $422.3 million. Capex is not disclosed in the reported block, but it was small in prior quarters: $5.7 million in the first quarter of 2026 and $4.7 million in the second.
Free cash flow therefore remains high, and it is the main source of shareholder payouts.
A 9.6% dividend yield rests on payouts funded by high profit
The trailing twelve-month dividend yield is 9.6%. That is a high yield, well above risk-free rates, and it explains investor interest in the stock.
Payouts rest on trailing twelve-month profit of $73.6 million and operating cash flow of $119.4 million. On that base the company can pay generously without adding debt.
Our estimate for the current year is payouts close to last year's level, provided copper prices stay high. The risk to the payout is a fall in metal prices: the quarter's profit is 240.3% above last year's largely on prices rather than volumes.
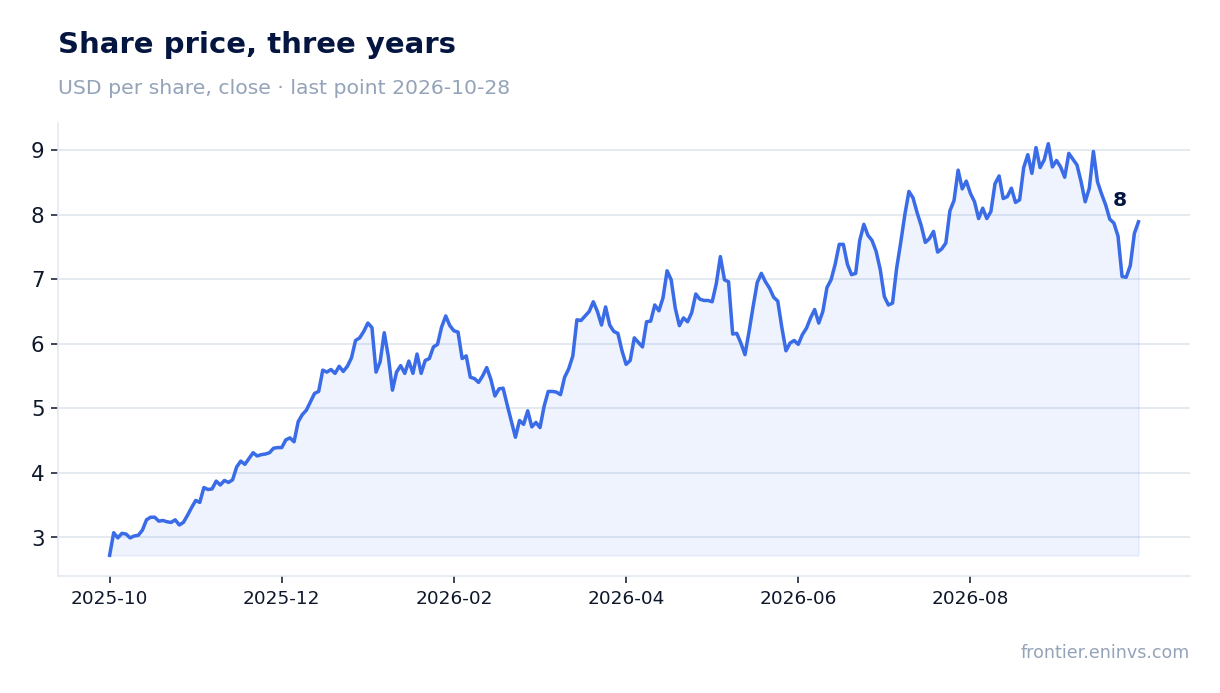
EV/EBITDA of 6.0 against its own three-year average of 3.9 – the share is above its history
The trailing twelve-month EV/EBITDA is 6.0, 56% above its own three-year average of 3.9. On this multiple the share is more expensive than its three-year history.
The trailing P/E is 12.3 – a moderate level for a company with a 26.8% net margin. The gap between a rich EV/EBITDA and a moderate P/E reflects high depreciation and low debt.
The portal's model, which reprices EBITDA at current commodity prices at the target EV/EBITDA, implies +15% upside to fair value. That is our own estimate, not a market consensus.
The portal's model implies +15% upside to fair value
On the portal's model fair value is 15% above the current market price. The calculation reprices EBITDA at current commodity prices at the target EV/EBITDA multiple.
The 15% upside is moderate: it does not offset the 56% premium to the company's own EV/EBITDA history. In other words, even with favourable prices the room for growth is limited.
The next report is needed to confirm the estimate: if EBITDA stays above $40 million a quarter, the model will look conservative. If copper prices fall, the upside disappears.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 0.91 bn USD |
| P/E (LTM) | 12.3 |
| EV/EBITDA (LTM) | 6.0 |
| P/B | 7.88 |
| Operating cash flow (LTM) | 0.12 bn |
| ROE | 62.9% |
| Dividend yield (12m) | 9.6% |
| EV/EBITDA, 3-year average | 3.9 |
Bottom line
The quarter was strong: revenue rose 61.2%, EBITDA 154.0%, the EBITDA margin reached 51.7%, and operating cash flow of $32.6 million covers profit. But profit growth of 240.3% rests on copper prices rather than volumes, which makes the result vulnerable to a commodity reversal. The 9.6% dividend yield is attractive, but payouts rest on the same high profit. An EV/EBITDA of 6.0 against its own three-year average of 3.9 shows the share is already above its history, and the portal model's upside is only +15%. The verdict is neutral: strong operating results are balanced by a rich valuation and dependence on copper prices.
Open the company's financial profile ARG →
See also: market overview · valuation map · stock screeners