Alliance Resource Partners: profit up 46.8%, but half the gain came from one-off items
On 26 October Alliance Resource Partners reported third-quarter 2026 results: revenue of $603.0 million (+5.5% year on year), adjusted EBITDA of $233.9 million (+27.7%) and net income of $139.6 million (+46.8%). Revenue growth accelerated from +0.7% in the second quarter to +5.5% in the third on coal logistics and record royalties, but a visible share of profit came from bitcoin revaluation and a one-off acquisition gain. At an EV/EBITDA of 5.6 against its own three-year average of 4.5 and a portal-model upside of -2%, the unit looks neutral: the 9.1% dividend yield is attractive, but the price already reflects the recovery.
Key takeaways
— Revenue accelerated to +5.5% on coal volumes and record royalties
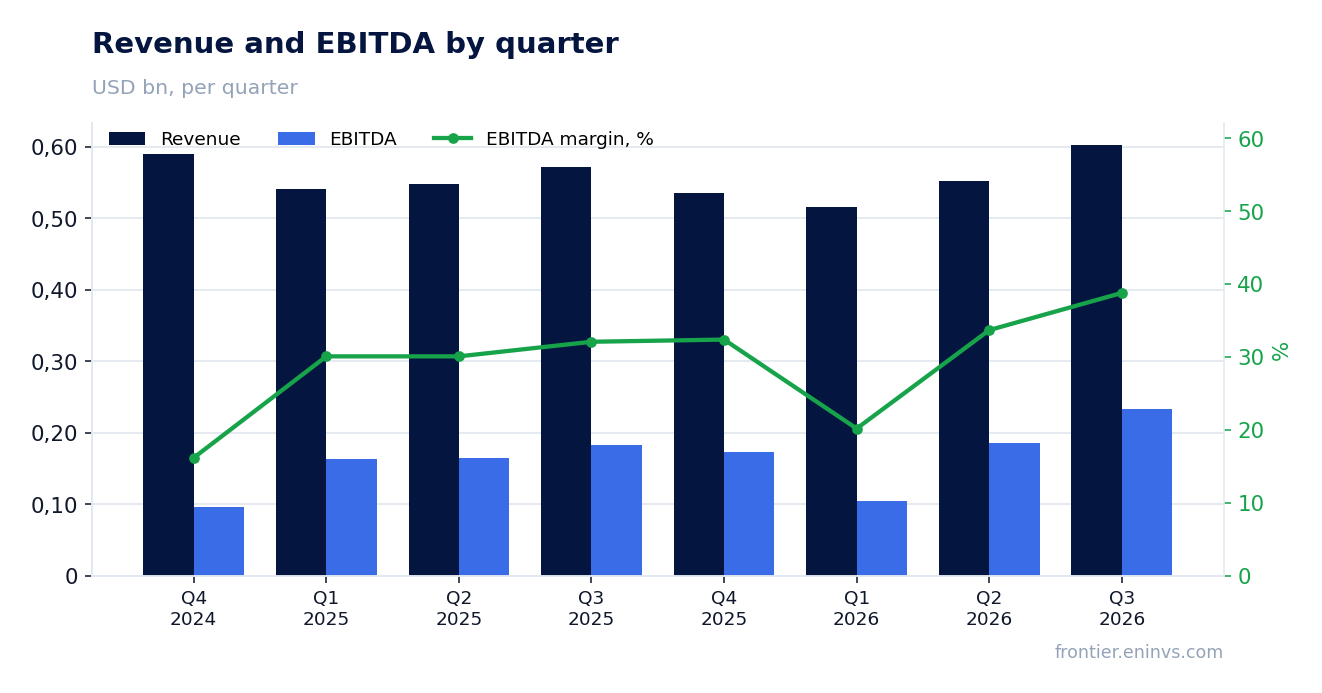
— EBITDA margin rose to 38.8% as unit costs fell 13.1%
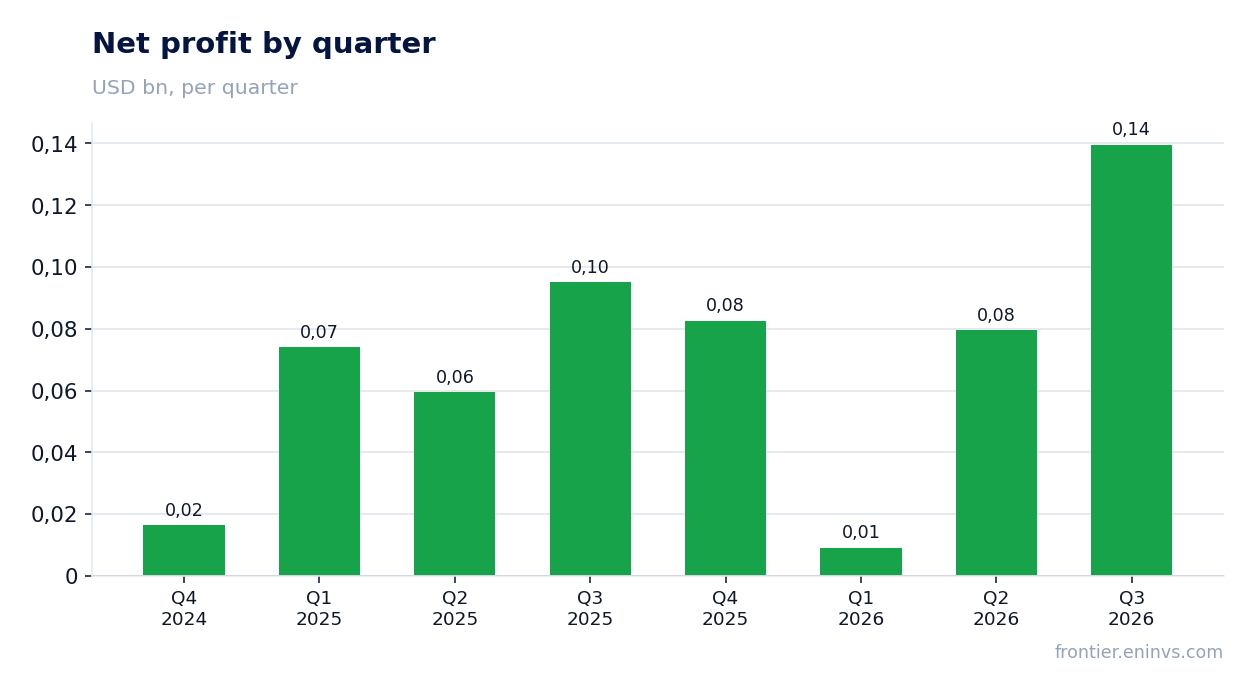
— Half the profit gain came from bitcoin revaluation and a one-off acquisition gain
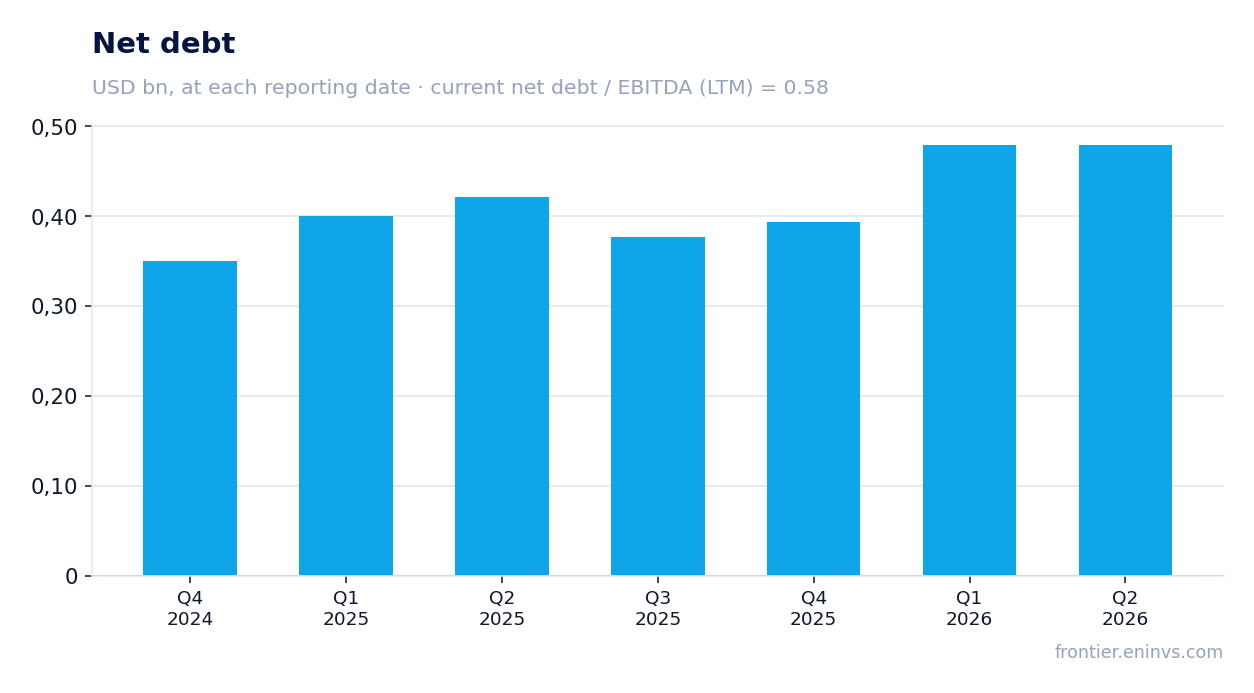
— Leverage of 0.58x LTM EBITDA is low, but liquidity is limited to $430.8 million
— The $0.60 quarterly distribution is covered 1.76x by cash flow
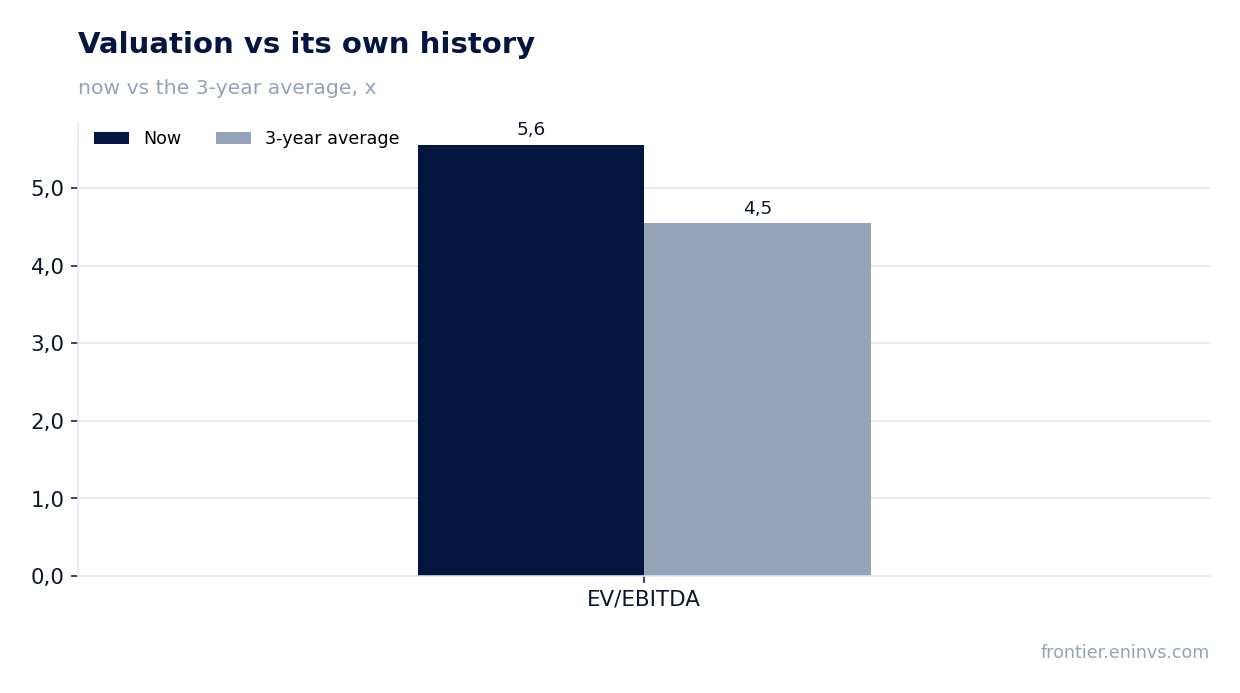
— The 5.6 multiple is 22% above its own three-year average of 4.5
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 0.57 | 0.60 | +5.5% |
| EBITDA | 0.18 | 0.23 | +27.7% |
| Operating profit | 0.10 | — | — |
| Net profit | 0.10 | 0.14 | +46.8% |
| Operating cash flow | 0.21 | — | — |
| Capex | 0.06 | — | — |
| EBITDA margin | 32.1% | 38.8% | +6.7 pp |
| Net margin | 16.6% | 23.2% | +6.6 pp |
Revenue accelerated to +5.5% on coal volumes and record royalties
Third-quarter 2026 revenue was $603.0 million against $571.4 million a year earlier, up 5.5%. That is an acceleration from +0.7% in the second quarter: the company restored volumes after the extended longwall move at Hamilton and raised sales in Appalachia.
The coal segment sold 9.348 million tons (+7.4% year on year), but the average price fell 8.3% to $53.93 per ton on a mix shift toward lower-priced Tunnel Ridge volumes. Oil and gas royalties rose to a record $59.8 million, and total royalty revenue reached $87.5 million (+52.5%).
The AllDale III IV acquisition, closed on 1 July 2026 for $206.2 million, added about 48,500 net royalty acres and increased oil and gas volumes 1.6-fold. Without this purchase, revenue growth would have been noticeably more modest.
EBITDA margin rose to 38.8% as unit costs fell 13.1%
Adjusted EBITDA reached $233.9 million, up 27.7% year on year, and the margin rose to 38.8% from 32.1%. The main driver was a 13.1% fall in coal-segment unit costs to $35.64 per ton.
In the Illinois Basin, cost per ton fell 10.2% on higher output at Hamilton and improved performance at River View. In Appalachia, unit costs dropped 19.9% on higher production at Tunnel Ridge and a favourable sales mix.
Coal-segment EBITDA rose 18.6% to $186.8 million, while the royalties segment added $61.8 million (+40.0%). Operating expenses fell 4.4% while revenue grew, which delivered the margin expansion.
Half the profit gain came from bitcoin revaluation and a one-off acquisition gain
Net income was $139.6 million against $95.1 million a year earlier, up 46.8%. The release explicitly names two non-operating items: a $16.5 million revaluation of digital assets and a $6.3 million gain on remeasuring the previously held stake in AllDale III.
Together these items account for about $22.8 million, or roughly half of the $44.5 million profit increase. Without them, net income growth would have been closer to 25%, still solid but noticeably more modest than the headline.
Profit was also supported by equity-method investment income rising to $12.8 million from $4.5 million and by lower operating expenses. Partly offsetting were higher income tax ($19.0 million versus $5.9 million) and a $7.3 million loss on derivatives assumed in the acquisition.
Leverage of 0.58x LTM EBITDA is low, but liquidity is limited to $430.8 million
Net debt at the latest annual balance sheet was $394.2 million, and net debt to trailing-twelve-month EBITDA was 0.58. That is a comfortable level for a coal company, although the ratio alone says nothing about its direction.
Total debt and finance leases at 30 September 2026 were $679.9 million, and the debt-to-EBITDA ratio for the trailing twelve months was 0.89. Liquidity stood at $430.8 million, including $84.8 million of cash and $346.0 million of available credit lines.
Interest expense rose to $15.8 million from $11.0 million a year earlier, still moderate at this leverage. The company also holds 673 bitcoins valued at $56.3 million, which add volatility to earnings but not to debt.
The $0.60 quarterly distribution is covered 1.76x by cash flow
The board approved a quarterly distribution of $0.60 per unit, or $2.40 annualised. Payment is due on 13 November 2026 to unitholders of record on 6 November.
Distributable cash flow for the quarter was $136.8 million, and the coverage ratio was 1.76x, more than 27% better than the previous quarter. With a market capitalisation of $3,396.6 million, the trailing-twelve-month dividend yield is 9.1%.
Our estimate: at the current quarterly pace, the annual payout will stay at $2.40 per unit. It rests on earnings and cash flow but is sensitive to coal prices and to the one-off items that already boosted profit this quarter. A cut is possible if energy prices fall or capital spending exceeds the $270–290 million guided for the year.
The 5.6 multiple is 22% above its own three-year average of 4.5
On a trailing-twelve-month EV/EBITDA basis the unit trades at 5.6 against its own three-year average of 4.5, or 22% above its history. The trailing P/E is 10.9 and return on equity is 17.8%.
The portal model, which reprices EBITDA at current commodity prices at the target EV/EBITDA, implies -2% upside to the current price. That is not a consensus but our own model, and it says the market has already priced in the earnings recovery.
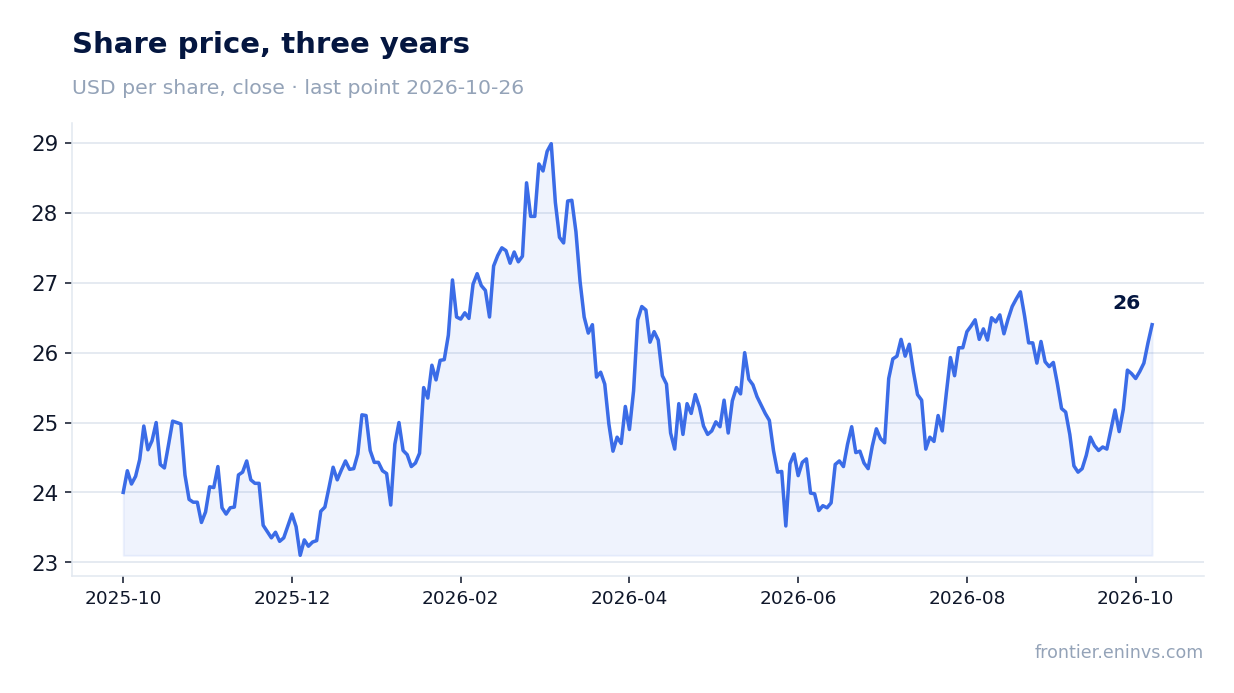
The price reaction was muted: the unit added 1.0% on the release day and the same from publication to 26 October. With a 9.1% yield and a multiple above its historical average, further gains require confirmation that earnings are sustainable without one-off items.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 3.40 bn USD |
| P/E (LTM) | 10.9 |
| EV/EBITDA (LTM) | 5.6 |
| P/B | 1.83 |
| Net debt / EBITDA (LTM) | 0.58 |
| ROE | 17.8% |
| Dividend yield (12m) | 9.1% |
| EV/EBITDA, 3-year average | 4.5 |
Bottom line
The quarter was strong operationally: revenue accelerated to +5.5%, EBITDA margin rose to 38.8% and unit costs fell 13.1%. However, half the profit gain came from bitcoin revaluation and a one-off acquisition gain rather than the core business. The distribution is covered 1.76x by cash flow and yields 9.1%, which supports the unit. The question for a holder now is whether earnings hold without one-off items at a multiple above its own history. Verdict – neutral: the dividend is attractive, but the price already reflects the recovery.
Open the company's financial profile ARLP →
See also: market overview · valuation map · stock screeners