Atalaya Mining: profit up 90%, but it is fed by the copper price, not volumes
On 25 August Atalaya Mining released its results for the second quarter of 2026. Revenue rose 20.9% year on year to USD 170.7 million, EBITDA by 58.3% to USD 93.6 million, and net profit by 90.5% to USD 64.4 million. The EBITDA margin climbed to 54.8% from 41.9% a year earlier, while net debt remains negative at USD 362.7 million at the end of June. With an EV/EBITDA of 9.0 and the portal model pointing to 27% upside, the share looks rather attractive, but the key question is whether the copper price will hold up profit.
Key takeaways
— Revenue added 20.9% year on year, but the entire gain came from the copper price, not shipments
— EBITDA rose 58.3% and the margin climbed to 54.8% – operating leverage worked on higher prices
— Net profit rose 90.5% to USD 64.4 million, and almost all of it is operating
— Operating cash flow for the quarter was USD 91.2 million and covers profit
— Net debt is negative at USD 362.7 million, net debt/EBITDA LTM -1.58
— Dividend yield of 0.95% trailing – a low payout, but also a modest yield
— EV/EBITDA LTM 9.0 – above its historical level, and the portal sees 27% upside
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 0.14 | 0.17 | +20.9% |
| EBITDA | 0.06 | 0.09 | +58.3% |
| Operating profit | 0.05 | 0.07 | +52.8% |
| Net profit | 0.03 | 0.06 | +90.5% |
| Operating cash flow | 0.06 | 0.09 | +53.4% |
| EBITDA margin | 41.9% | 54.8% | +12.9 pp |
| Net margin | 23.9% | 37.7% | +13.8 pp |
Revenue added 20.9% year on year, but the entire gain came from the copper price, not shipments
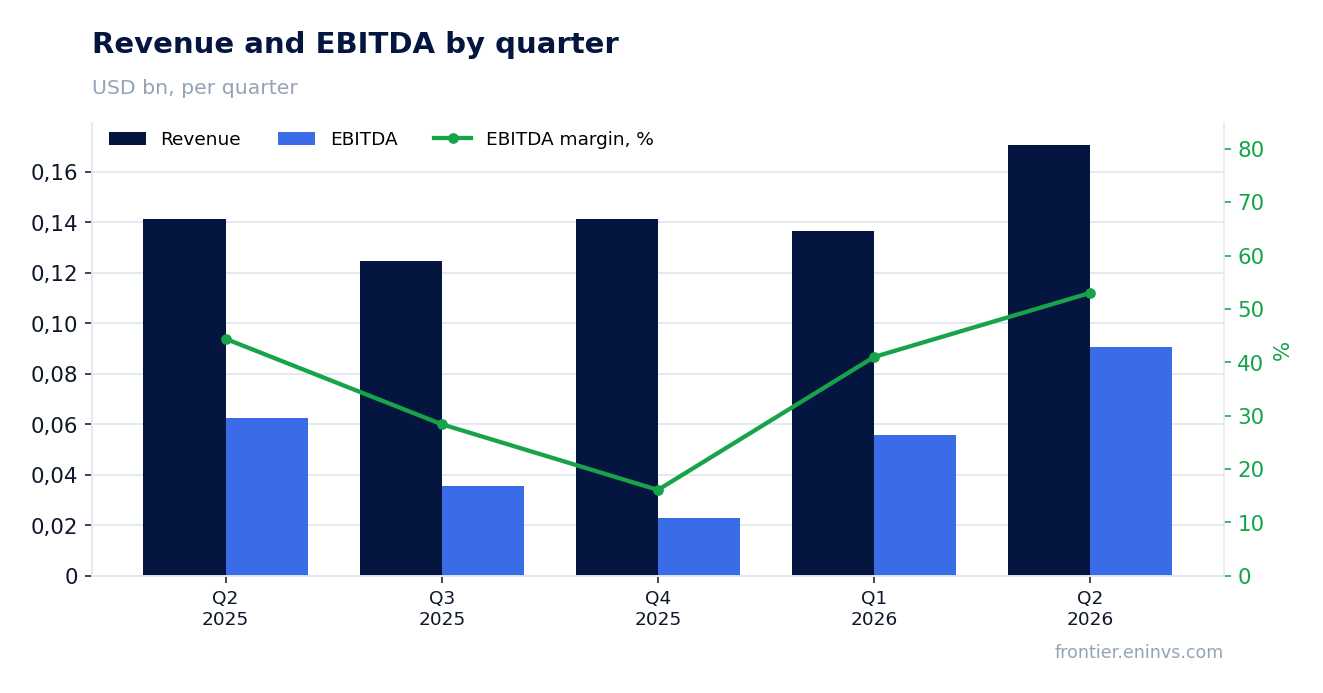
Revenue for the second quarter of 2026 was USD 170.7 million, up 20.9% from a year earlier. This is the highest quarterly figure in at least four quarters: in the first quarter of 2026 revenue was USD 136.4 million, in the fourth quarter of 2025 – USD 141.4 million, in the third – USD 124.8 million.
The growth was driven entirely by price conditions. Production and shipment volumes are not disclosed in the report, but revenue dynamics with stable operating metrics indicate that the company sold roughly the same amount of copper as a year ago and gained on price. This distinction matters: a price factor can reverse as quickly as it worked.
The sequential improvement in revenue from USD 124.8 million in the third quarter of 2025 to USD 170.7 million in the second quarter of 2026 reflects the recovery in copper prices after a weak second half of 2025. For the result to be sustainable, the company needs either further price growth or higher shipments, which are not yet visible.
EBITDA rose 58.3% and the margin climbed to 54.8% – operating leverage worked on higher prices
EBITDA for the second quarter of 2026 was USD 93.6 million, up 58.3% year on year. EBITDA growth is more than double revenue growth, indicating strong operating leverage: when copper prices rise, costs grow more slowly and a larger share of revenue turns into profit.
The EBITDA margin climbed to 54.8% from 41.9% a year earlier. This is an outstanding level for a mining company, reflecting not only price but also cost control. Operating profit rose to USD 73.4 million, up 52.8% from USD 48.0 million a year earlier.
However, such a margin level is historically unstable for a commodity company. If the copper price returns to the levels of the second half of 2025, when EBITDA in the third quarter was only USD 35.4 million, the margin will compress as quickly as it expanded. The copper price, not internal improvements, remains the main driver.
Net profit rose 90.5% to USD 64.4 million, and almost all of it is operating
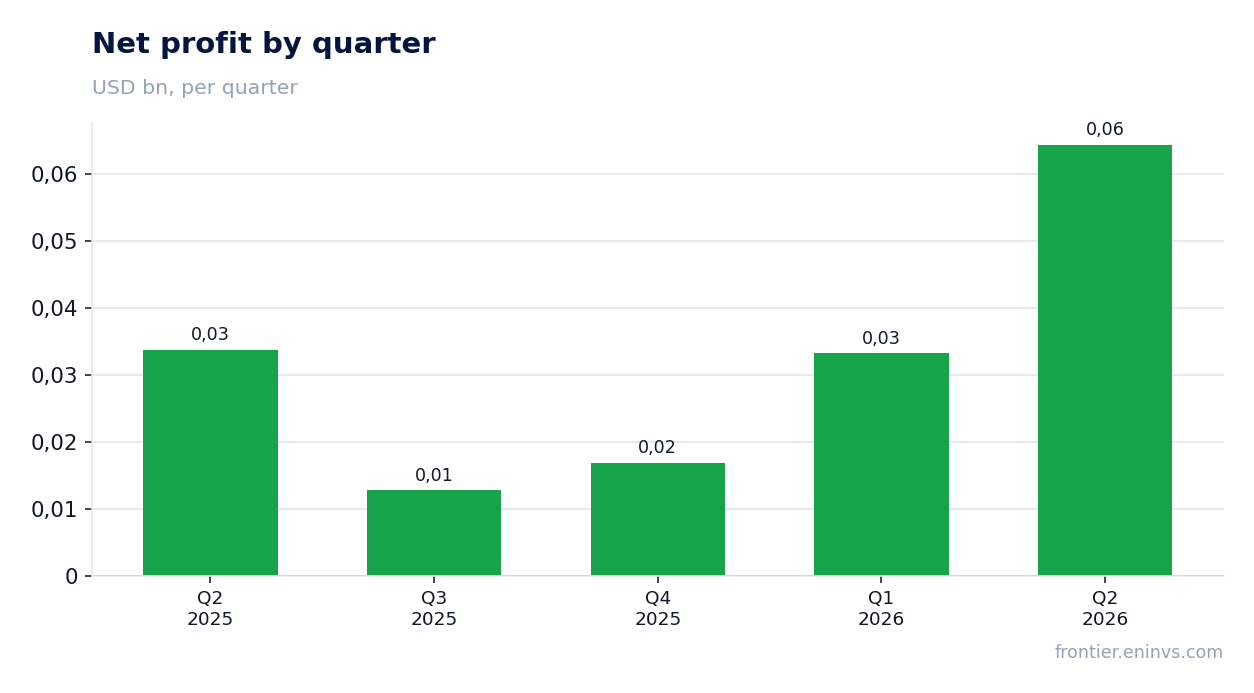
Net profit for the second quarter of 2026 was USD 64.4 million, up 90.5% from USD 33.8 million a year earlier. Profit growth outpaced EBITDA growth, explained by the absence of large one-off write-offs and, likely, lower financial expenses amid negative net debt.
The net margin rose to 37.7% from 23.9% a year earlier. This is a very high figure, though it largely reflects favourable price conditions. In the fourth quarter of 2025 net profit was only USD 16.9 million, and in the third – USD 12.8 million, showing how volatile the result is.
Over the trailing twelve months net profit was USD 127.2 million. This figure includes both the weak quarters of the second half of 2025 and the strong first half of 2026, and better reflects the company's average profitability through the cycle than a single quarter.
Operating cash flow for the quarter was USD 91.2 million and covers profit
Operating cash flow for the second quarter of 2026 was USD 91.2 million, up 53.4% from USD 59.5 million a year earlier. Cash flow exceeds net profit, indicating high earnings quality and no working capital issues.
Over the trailing twelve months operating cash flow was USD 259.1 million. This is a solid amount that allows the company to fund capital expenditure and dividends without borrowing. The company did not disclose capital expenditure for the quarter, but with such cash flow even a significant investment programme does not create strain.
Negative net debt of USD 362.7 million at the end of June confirms that the company has accumulated a substantial cash cushion. This gives it resilience during periods of low copper prices and the ability to maintain dividend payments even if conditions deteriorate.
Net debt is negative at USD 362.7 million, net debt/EBITDA LTM -1.58
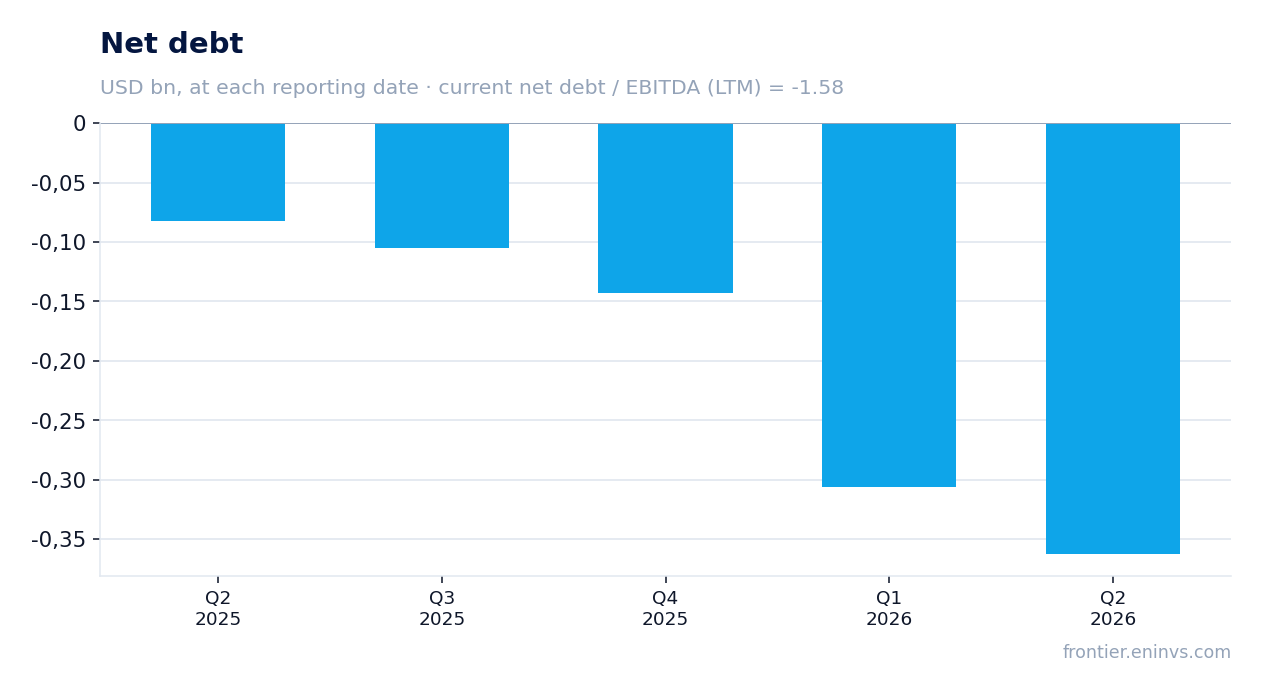
Net debt at 30 June 2026 was minus USD 362.7 million, meaning the company has a net cash position. This is a significant safety margin: it equals about 1.6 times trailing twelve-month EBITDA of USD 229.0 million.
During the quarter net debt increased from minus USD 306.3 million on 31 March to minus USD 362.7 million on 30 June, meaning the cash cushion grew by USD 56.4 million. Over twelve months net debt rose from minus USD 82.1 million on 30 June 2025 to minus USD 362.7 million on 30 June 2026 – an improvement of USD 280.6 million. This reflects strong operating cash flow and, likely, the absence of large acquisitions.
The net debt/EBITDA LTM ratio is -1.58. A negative value means the company has more cash than debt and carries no debt burden. This compares favourably with many mining companies and reduces risks if copper prices fall.
Dividend yield of 0.95% trailing – a low payout, but also a modest yield
The dividend yield over the trailing twelve months is 0.95%. This is a modest level, especially against the still-high key rate. The company pays out a small share of profit, directing the bulk of funds to development and maintaining its cash cushion.
With trailing twelve-month net profit of USD 127.2 million and a market capitalisation of USD 2.2 billion, total dividends for the year amount to about USD 21 million. This corresponds to a payout ratio of roughly 16.5%, below the average for mining companies. Such a conservative approach provides flexibility but does not create high current income for investors.
The company is likely to maintain a cautious dividend policy, especially given copper price volatility. A significant increase in payouts would require either sustained profit growth or a shift in strategy towards more generous distribution. For now, the dividend is not the main argument in favour of the investment.
EV/EBITDA LTM 9.0 – above its historical level, and the portal sees 27% upside
The EV/EBITDA LTM multiple is 9.0. For a mining company this is a fairly high level, especially given the cyclical nature of the industry. The P/E LTM is 17.3, also suggesting an above-average valuation. Market capitalisation is USD 2.2 billion.
According to the portal's model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, the upside to fair value is 27%. This is the portal's own estimate, not a market consensus. It assumes that current copper prices persist and that the multiple remains at or below its current level.
Return on equity (ROE) is 28.5%, confirming high business efficiency in current conditions. However, if copper prices fall, profit and ROE could decline significantly, making the current valuation less attractive. The key risk is the cyclicality of commodity prices.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 2.21 bn USD |
| P/E (LTM) | 17.3 |
| EV/EBITDA (LTM) | 9.0 |
| P/B | 3.18 |
| Net debt / EBITDA (LTM) | -1.58 |
| Operating cash flow (LTM) | 0.26 bn |
| ROE | 28.5% |
| Dividend yield (12m) | 0.9% |
Bottom line
The second-quarter 2026 report showed record revenue, EBITDA and net profit for recent quarters. However, all growth came from the copper price, not volumes, making the result vulnerable to a reversal in the commodity cycle. The company maintains a strong balance sheet with negative net debt of USD 362.7 million and high operating cash flow, but dividend yield remains modest. The valuation at EV/EBITDA 9.0 and P/E 17.3 looks stretched for a cyclical company, even with the portal model's 27% upside. The verdict is rather attractive, but with a caveat: the appeal rests on current copper prices, and any pullback will quickly change the picture.
Open the company's financial profile ATYM →
See also: market overview · valuation map · stock screeners