Innovative Industrial Properties: revenue has stalled while earnings lean on loan interest and tenant deposits
On November 2, Innovative Industrial Properties reported results for the third quarter of 2026. Revenue came in at $64.9 million, up just 0.3% year on year, net income at $28.7 million, down 2.0% from a year earlier, while EBITDA jumped 40.4% to $67.5 million at a 104.0% margin. The EBITDA gain rests almost entirely on interest and dividend income from the IQHQ investments rather than on rent, so with EV/EBITDA at 8.9 against its own three-year average of 9.5 and a 14.0% dividend yield the share looks rather attractive, with a caveat on earnings quality.
Key takeaways
— Revenue has stalled: up 0.3% year on year after 0.7% a quarter earlier
— EBITDA rose 40.4% on IQHQ interest, not on rent
— Net income fell 2.0% as interest expense climbed to $11.8 million
— Defaulting tenants delivered $11.6 million in payments and deposits
— Debt at 1.64x LTM EBITDA is a level, not a trend
— The $1.90 dividend at a 14.0% yield rests on AFFO, not on net income
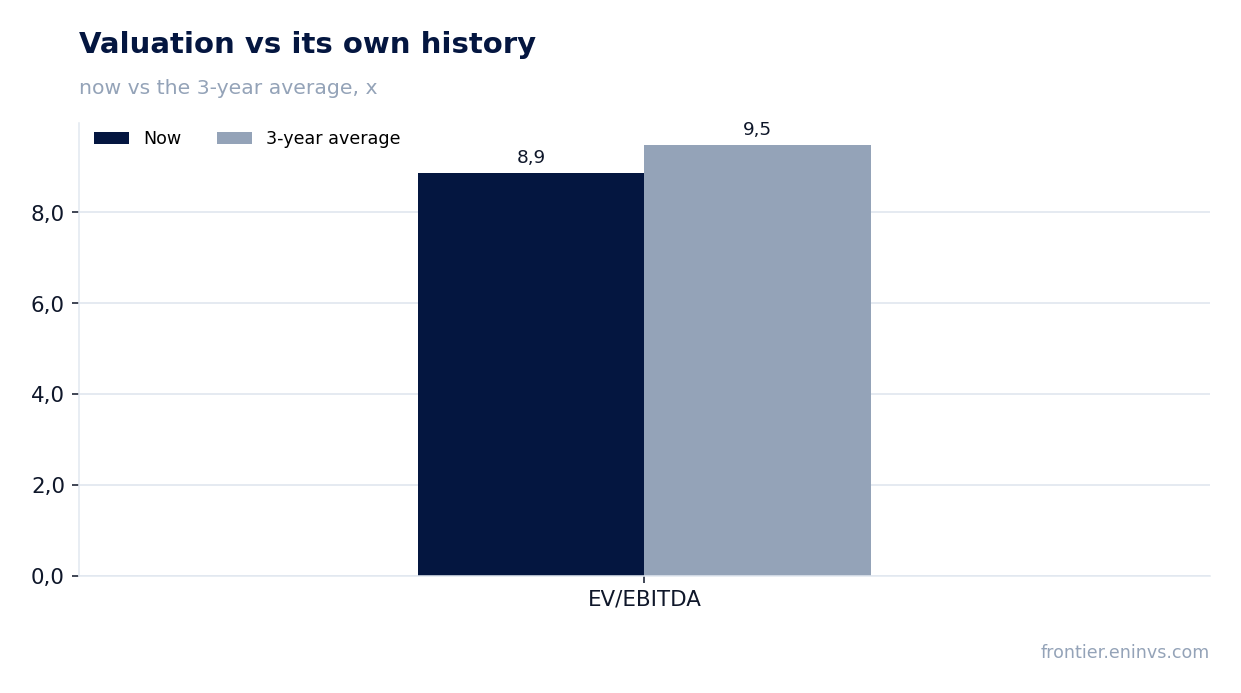
— The 8.9 multiple sits below its own three-year average of 9.5
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 0.06 | 0.06 | +0.3% |
| EBITDA | 0.05 | 0.07 | +40.4% |
| Operating profit | 0.03 | 0.03 | -0.1% |
| Net profit | 0.03 | 0.03 | -2.0% |
| Operating cash flow | 0.05 | — | — |
| Capex | 0.00 | — | — |
| EBITDA margin | 74.3% | 104.0% | +29.7 pp |
| Net margin | 45.3% | 44.2% | -1.1 pp |
Revenue has stalled: up 0.3% year on year after 0.7% a quarter earlier
In the third quarter of 2026 revenue came to $64.9 million against $64.7 million a year earlier – growth of 0.3%. A quarter earlier it was 0.7%, so the pace barely changed. After a 21.2% drop in the second quarter of 2025 the company has flattened out and has held near zero for three quarters.
Rental receipts accounted for $64.7 million of the total, other income for just $0.2 million. The release attributes the increase to deposits applied on repossessed properties, partly offset by lower rent from disposals and lease terminations. Organic rent is not growing; one-off accruals are carrying the top line.
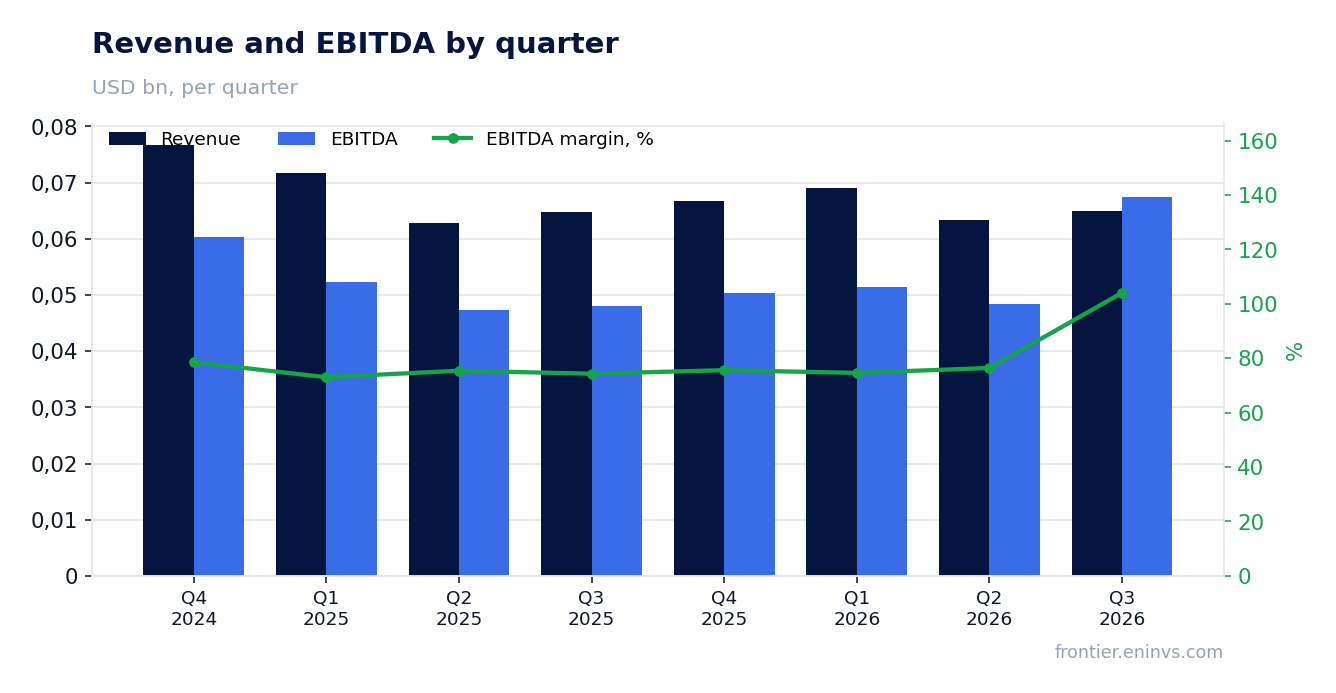
EBITDA rose 40.4% on IQHQ interest, not on rent
EBITDA for the reported quarter was $67.5 million against $48.1 million a year earlier, with the margin at 104.0% versus 74.3%. A margin above 100% is possible because EBITDA includes interest and dividend income unrelated to rent.
Interest and other income rose by $9.9 million to $14.3 million, and the release states plainly that the increase came mainly from $10.4 million of interest and dividend income on the IQHQ financial investments. That is a return on capital placed in a mezzanine loan and preferred equity, not on leased real estate.
Operating profit was essentially flat – $29.4 million against $29.4 million – because higher interest expense and depreciation absorbed the gain. EBITDA here is not a measure of the rental business but the sum of rent and financial investments.
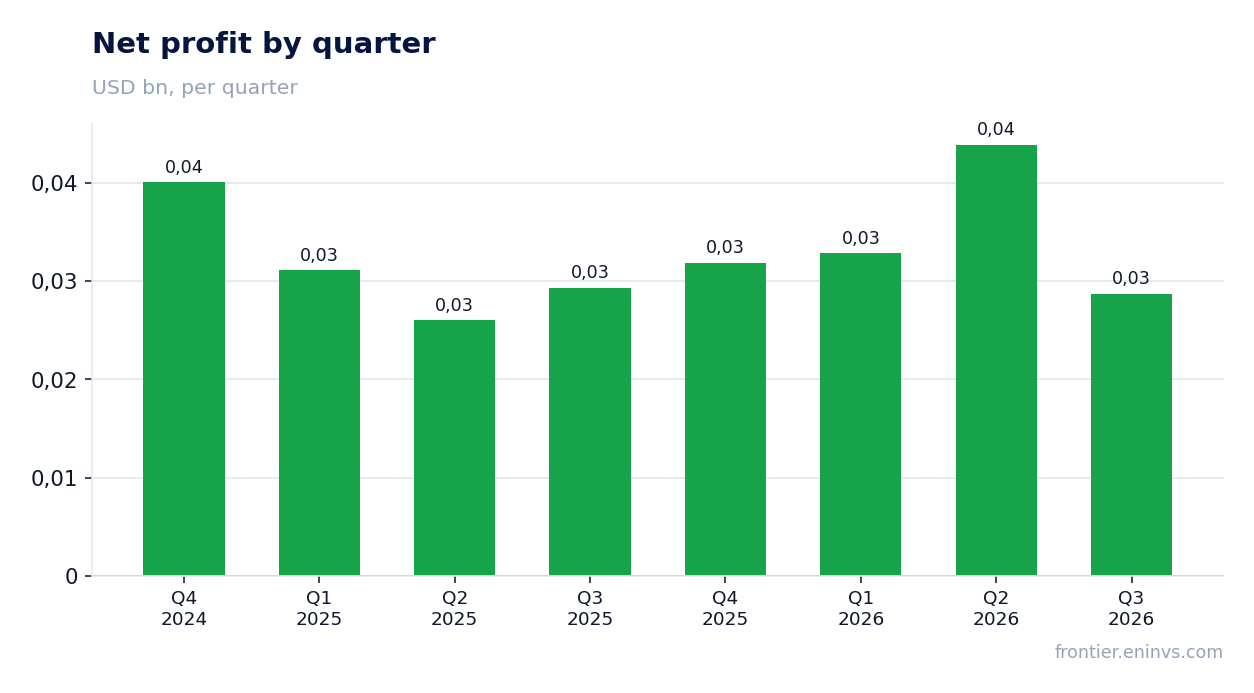
Net income fell 2.0% as interest expense climbed to $11.8 million
Net income attributable to common stockholders was $28.7 million against $29.3 million a year earlier – down 2.0%. The net margin slipped to 44.2% from 45.3%.
The release names the cause: interest expense rose to $11.8 million from $4.5 million a year earlier. The company replaced the maturing 2026 notes with $389.7 million of exchangeable notes, added $118.7 million of term loans and drew its revolver up to $187.5 million. Servicing that debt now costs more than the old structure did.
Preferred dividends rose to $3.2 million from $1.0 million, further reducing what is left for common holders. Diluted earnings per share came to $0.99 against $0.97 a year earlier, as the lower net income was offset by a smaller share count.
Defaulting tenants delivered $11.6 million in payments and deposits
The release tabulates payments and applied deposits for troubled tenants: $11.6 million in the third quarter of 2026, or $0.41 per share, against $10.5 million a quarter earlier. The largest contributions came from Battle Green ($3.5 million) and The Cannabist ($2.9 million), with Parallel at $2.8 million entirely from a deposit.
This is not a sustainable rental stream but collections from tenants in default. Over the quarter the company terminated 16 leases covering 1.2 million square feet and signed 6 new ones for 604,000 square feet, so it is returning less space to service than it loses. All PharmaCann leases are terminated, and three 4Front properties remain, representing 7.1% of annualised contractual rent.
Part of these receipts already flows through revenue as deposits are applied, so they support both the top line and EBITDA. Without them the picture would be weaker, and the repeatability of such collections next quarter is not assured.
Debt at 1.64x LTM EBITDA is a level, not a trend
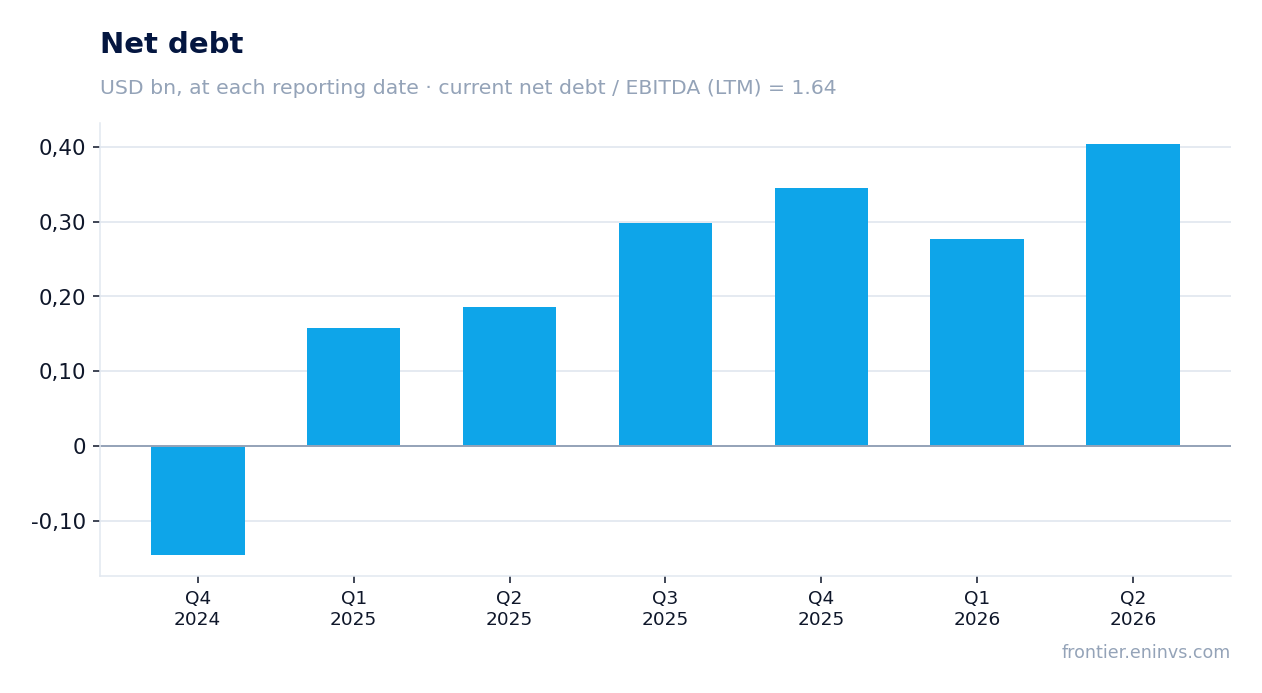
Net debt at the latest annual balance-sheet date was $345.5 million, or 1.64x trailing-twelve-month EBITDA. The release itself shows a different ratio at September 30, 2026 – 2.1x annualised Adjusted EBITDA on net debt of $569.2 million and total debt of $711.6 million. The gap reflects the quarter-end basis and the exchangeable notes and term loans that were not in the old structure.
Liquidity at quarter end was $142.4 million of cash, and net debt to total gross assets was 18.7% on $3.0 billion of assets. After the reporting date the company sold 2.17 million shares of 9.25% Series B preferred for $54.2 million gross and extended its $87.5 million revolver by 90 days to January 21, 2027.
Debt has risen, but calling this an improvement or deterioration in leverage is not possible: no earlier value of the ratio is in the facts. The cost is already visible in the income statement – $11.8 million of interest for the quarter, which is what eats the gain from financial investments.
The $1.90 dividend at a 14.0% yield rests on AFFO, not on net income
A dividend of $1.90 per share was declared for the third quarter of 2026, or $7.60 annualised. It was paid on October 15 to holders of record on September 30. Since inception the company has paid over $1.2 billion in common dividends.
The dividend is covered not by net income but by adjusted funds from operations: AFFO for the quarter was $54.8 million, or $1.96 per share, against $1.71 a year earlier. The company highlights 7% AFFO growth over the prior quarter. Our estimate: if the $1.90 quarterly dividend is maintained, the annual payout will be $7.60, and it rests on AFFO rather than on net income, which declined.
The yield on the current price is 14.0% trailing twelve months. That is a high rate, and it reflects both tenant risk and rising interest expense. A smaller payout could come from further tenant losses: 4Front accounts for 7.1% of contractual rent, and talks continue on the other troubled names. If collections from defaulting tenants stop, AFFO would compress faster than net income.
The 8.9 multiple sits below its own three-year average of 9.5
EV/EBITDA over the trailing twelve months is 8.9 against its own three-year average of 9.5, or 7% below. On this multiple the share is cheaper than its own three-year history. The trailing P/E is 11.1 and return on equity is 6.2%.
On the portal's model, which reprices EBITDA at current prices against a target EV/EBITDA, the upside to fair value is 26%. That is our own estimate, not a market consensus and not a target price.
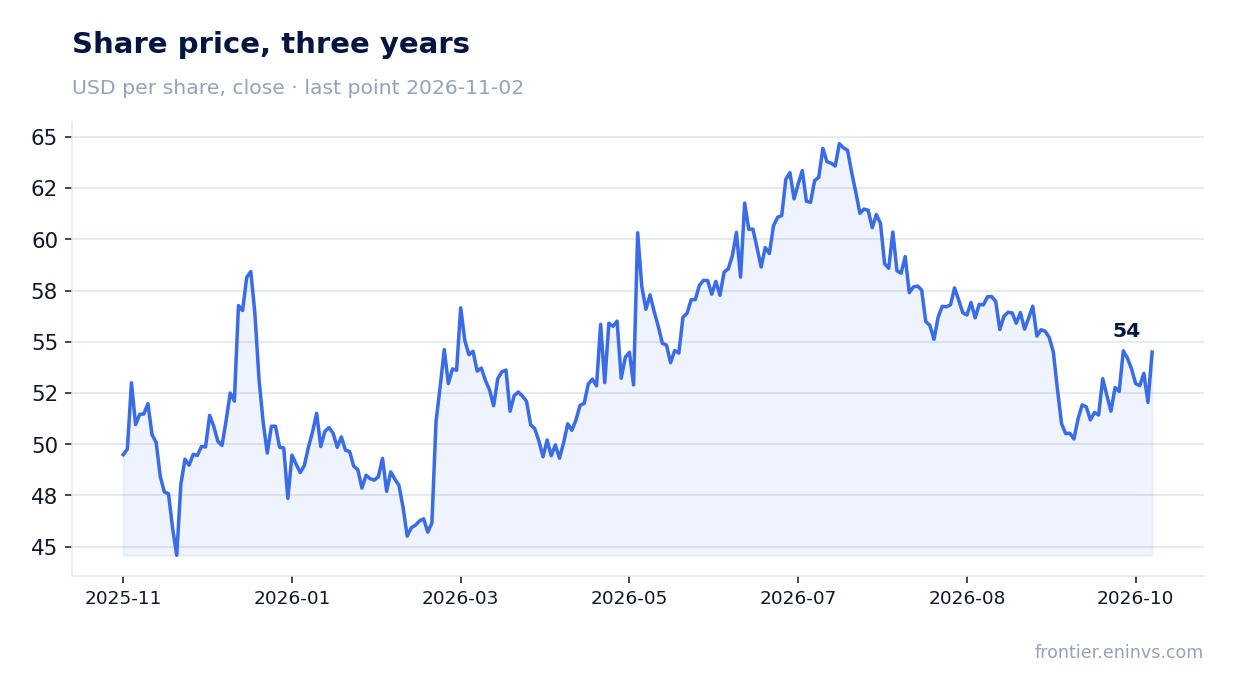
The share closed at $52.04 before the release, added 4.7% on the day and gained a further 4.7% through November 2. The market reacted to the EBITDA and AFFO growth, but the durability of that growth depends on whether IQHQ income and tenant collections persist.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1.53 bn USD |
| P/E (LTM) | 11.1 |
| EV/EBITDA (LTM) | 8.9 |
| P/B | 0.83 |
| Net debt / EBITDA (LTM) | 1.64 |
| ROE | 6.2% |
| Dividend yield (12m) | 14.0% |
| EV/EBITDA, 3-year average | 9.5 |
Bottom line
The strong points were 40.4% EBITDA growth and 7% AFFO growth over the prior quarter, plus the $1.90 dividend at a 14.0% yield. But most of the EBITDA gain is $10.4 million of IQHQ interest and dividends, while revenue rose only 0.3%. Net income fell 2.0% on $11.8 million of interest expense. The question for a holder now is whether financial-investment income and collections from defaulting tenants persist while the rental stream stagnates. At 8.9x against its own 9.5x average and with 26% upside on the portal's model, the share looks rather attractive, with a caveat on earnings quality.
Open the company's financial profile IIPR →
See also: market overview · valuation map · stock screeners