Targa Resources: revenue up 34.9% on prices and volumes, but adjusted EBITDA rose only 18%
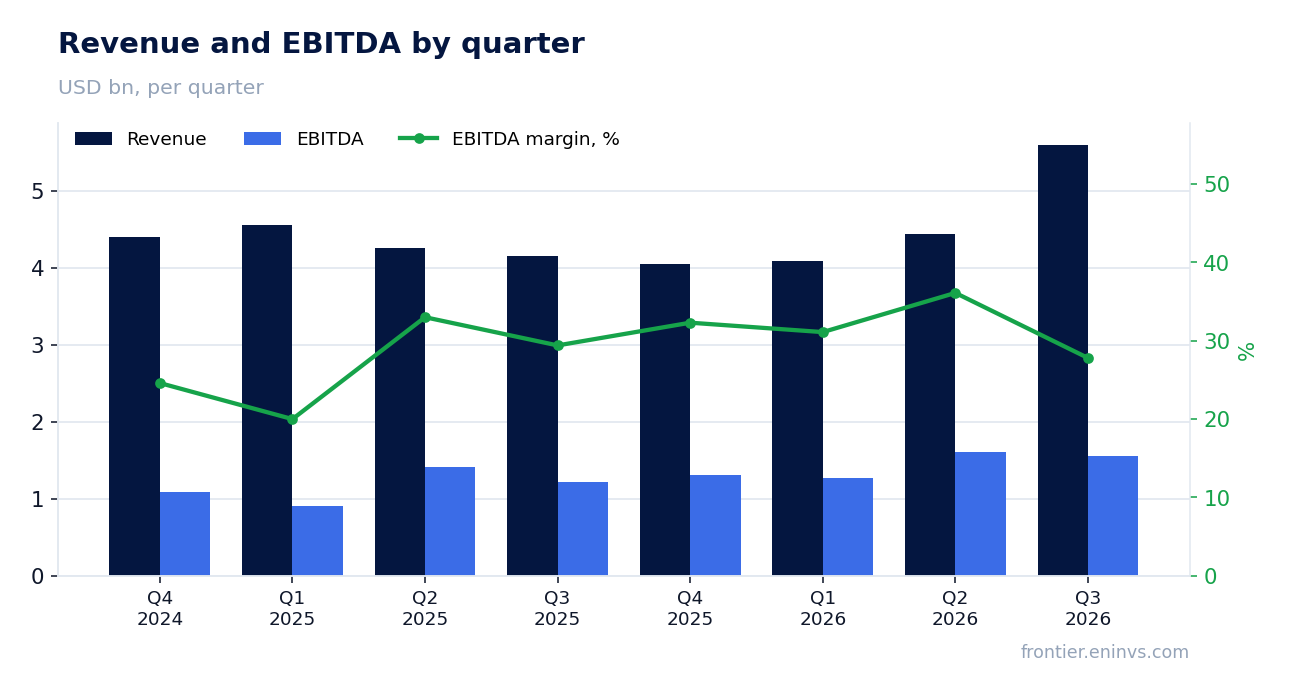
On November 5, Targa Resources released its third-quarter 2026 results. Revenue came in at $5,598.6 million, up 34.9% year-on-year, adjusted EBITDA at $1,504.3 million (+18%), and net income attributable to shareholders at $658.2 million (+37.6%). Revenue growth accelerated from 4.2% in the second quarter, but the EBITDA margin fell from 29.4% to 27.8% and free cash flow shrank to $33.6 million. With EV/EBITDA at 13.6 and the portal model pointing to 12% upside, the share looks rather attractive, though rising capex and margin pressure need confirmation in the next report.
Key takeaways
— Revenue rose 34.9% on prices and volumes, but adjusted EBITDA added only 18%
— EBITDA margin fell to 27.8% on higher product purchases and fuel costs
— Record Permian and logistics volumes supported segment margins
— Free cash flow shrank to $33.6 million as capital spending rose
— Debt rose to $19.1 billion, with net debt/EBITDA LTM at 3.39
— The dividend will rise 20% in 2027, but free cash flow does not yet cover it
— At 13.6 EV/EBITDA and 12% upside on the portal model, the share remains attractive
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 4.15 | 5.60 | +34.9% |
| EBITDA | 1.22 | 1.56 | +27.5% |
| Operating profit | 0.84 | 1.10 | +31.0% |
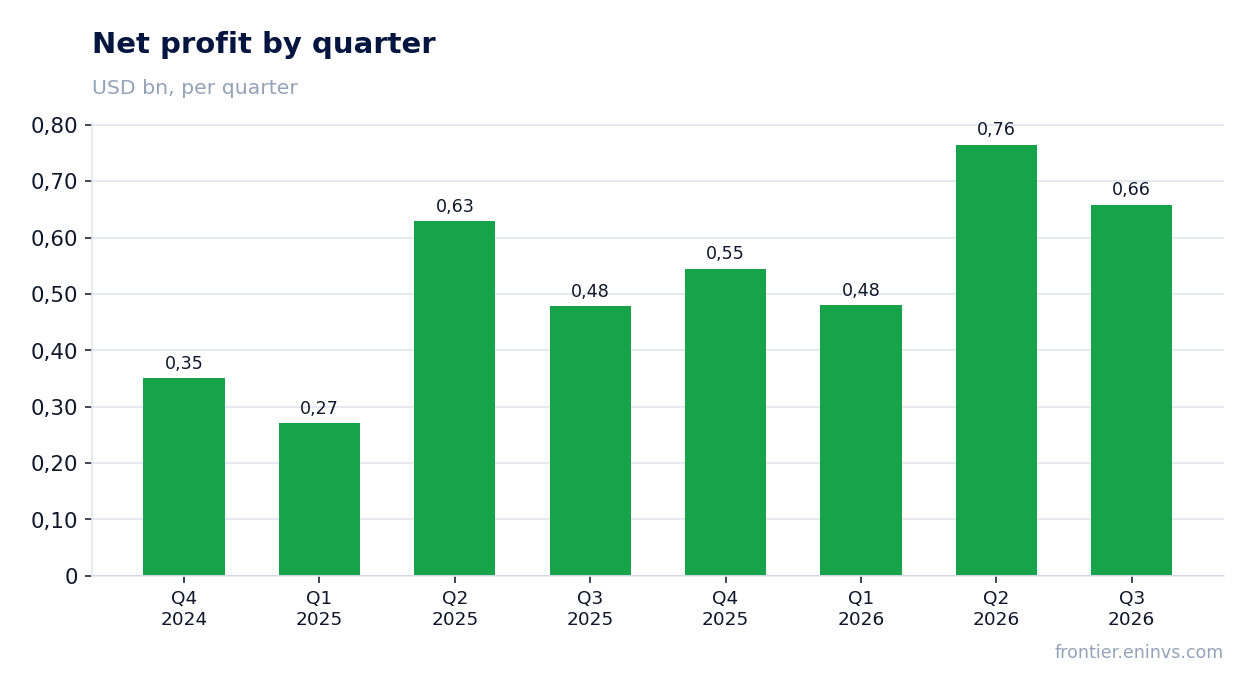
| Net profit | 0.48 | 0.66 | +37.6% |
| Operating cash flow | 0.60 | 1.37 | +127.8% |
| Capex | 0.67 | 1.24 | +85.3% |
| EBITDA margin | 29.4% | 27.8% | -1.6 pp |
| Net margin | 11.5% | 11.8% | +0.3 pp |
Revenue rose 34.9% on prices and volumes, but adjusted EBITDA added only 18%
Revenue in the third quarter of 2026 was $5,598.6 million, up 34.9% from the same quarter a year earlier. Growth accelerated from 4.2% in the second quarter. The company attributes the increase in commodity sales to higher NGL, natural gas and condensate prices ($801.5 million), higher volumes ($383.0 million) and a favorable hedge impact ($68.5 million).
Adjusted EBITDA rose 18% to $1,504.3 million, well short of revenue growth. The reason is faster growth in product purchases and fuel, which rose 43% to $3,578.6 million while revenue added 34.9%. As a result, the EBITDA margin fell from 29.4% to 27.8%.
Net income attributable to shareholders rose 37.6% to $658.2 million, helped by a 31% increase in operating profit to $1,096.0 million and a 30% rise in income tax expense. The gap between revenue and EBITDA growth shows the company cannot yet fully pass higher feedstock prices into margin.
EBITDA margin fell to 27.8% on higher product purchases and fuel costs
The EBITDA margin in the third quarter of 2026 was 27.8% versus 29.4% a year earlier. The main pressure came from product purchases and fuel, which rose 43% to $3,578.6 million while revenue increased 34.9%. Operating expenses added 12% to $372.3 million and G&A rose 8% to $112.9 million.
In the Gathering and Processing segment, adjusted operating margin rose 22% to $1,069.9 million on record Permian volumes. In Logistics and Transportation, margin added 10% to $888.1 million, held back by lower marketing and LPG export margins.
Falling EBITDA margin alongside rising revenue means the company is operating in an environment where feedstock prices rise faster than processing and transportation fees. For an investor, this signals that operating leverage is not working in favor of profit at current market conditions.
Record Permian and logistics volumes supported segment margins
Permian inlet volumes reached a record 7,536.6 MMcf/d, up 14% year-on-year. Midland volumes rose 7% to 3,472.8 MMcf/d and Delaware volumes rose 20% to 4,063.8 MMcf/d. Growth was driven by new plants: Bull Moose II in Q4 2025, Falcon II and East Pembrook in Q1 2026, and East Driver in Q2 2026.
In logistics, NGL pipeline transportation volumes rose 15% to 1,171.7 MBbl/d and fractionation volumes rose 11% to 1,261.5 MBbl/d. Export volumes added 10% to 447.9 MBbl/d. The company notes that Train 12 and the Bull Run Extension pipeline were commissioned ahead of schedule in Q4 2026.
Record volumes are the main argument for the Targa investment case. They show that the company's infrastructure projects are in demand, and the 20-year contracts with ExxonMobil create a base for further growth. However, volume growth is not yet translating into margin growth because of the price factor.
Free cash flow shrank to $33.6 million as capital spending rose
Adjusted free cash flow in the third quarter of 2026 was only $33.6 million versus $172.8 million a year earlier. The reason is higher capital spending: adjusted growth capex was $1,186.0 million versus $853.0 million a year earlier. Maintenance capex was unchanged at $57.2 million.
Operating cash flow for the quarter was $1,365.1 million, higher than a year earlier. However, almost all of it went to fund construction. The company confirms its estimate of 2026 net growth capex at about $5.0 billion and maintenance capex at about $250 million.
Free cash flow of $33.6 million is the remainder from which dividends and buybacks are funded. During the quarter the company repurchased 180,768 shares for $52 million and paid dividends. This means current payouts are funded partly by debt, not only by organic cash flow.
Debt rose to $19.1 billion, with net debt/EBITDA LTM at 3.39
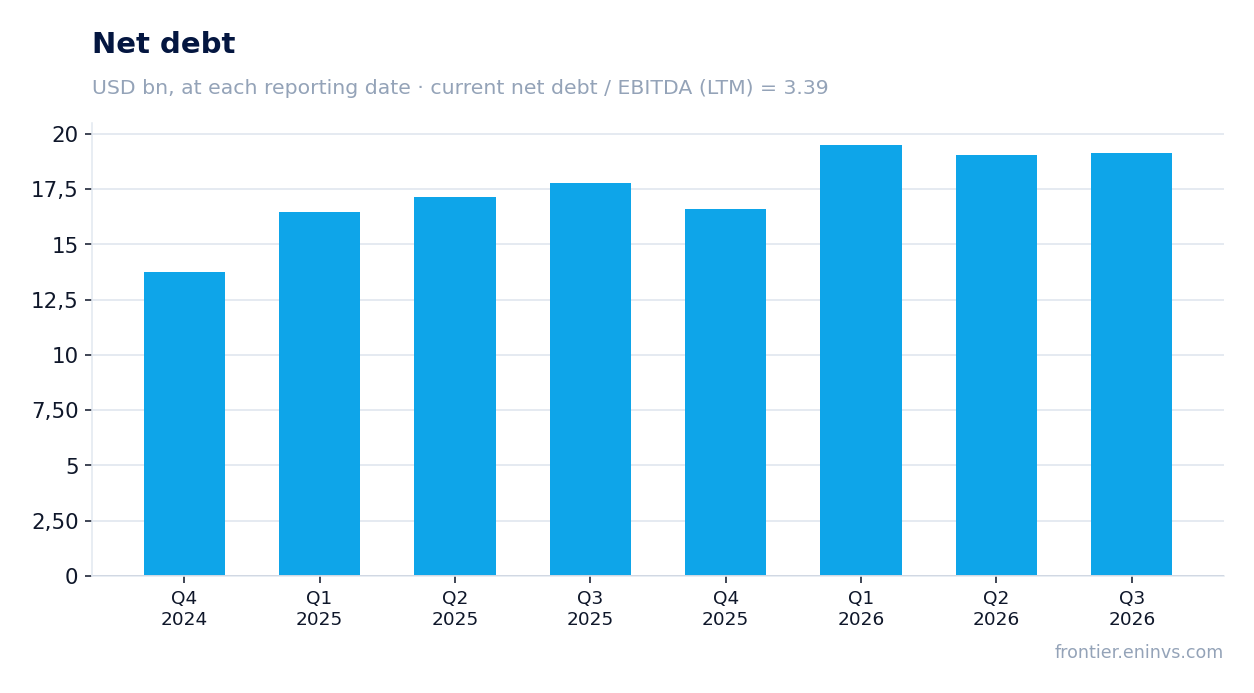
Net debt at September 30, 2026 was $19.1 billion versus $19.0 billion at June 30, 2026 and $17.8 billion at September 30, 2025. Over the year debt rose by $1.3 billion. The net debt/EBITDA ratio for the trailing twelve months is 3.39.
Total consolidated debt is $19.8 billion, including $17.9 billion of senior unsecured notes, $860 million under the commercial paper program, $451 million under the receivables securitization facility and $796 million of finance lease liabilities. Liquidity is about $2.9 billion, including $2.6 billion under the revolver.
Interest expense rose 5% to $232.8 million. With LTM EBITDA of $5,645.5 million, debt at 3.39x EBITDA looks manageable for an infrastructure company, but rising capex and shareholder payouts mean debt may continue to grow.
The dividend will rise 20% in 2027, but free cash flow does not yet cover it
For the third quarter of 2026 the company will pay a dividend of $1.25 per share, or $5.00 annualized. That is 25% more than in the third quarter of 2025. The total payout is about $268 million, payable on November 17, 2026. The company intends to recommend a dividend of $6.00 per share in 2027, 20% above 2026.
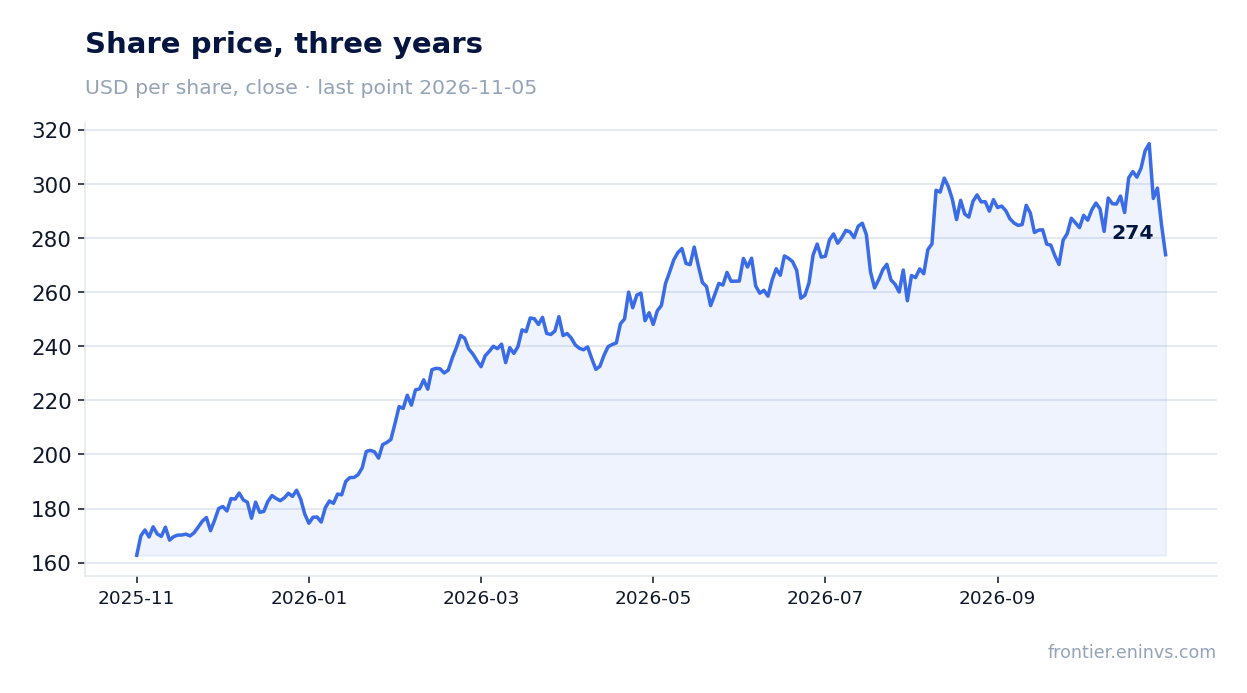
At a share price of $285.0, the annual dividend of $5.00 gives a yield of 1.75%. That is a modest yield for an infrastructure company, but it is offset by growth: the company promises meaningful annual dividend increases beyond 2027 as well.
Free cash flow of $33.6 million for the quarter does not cover dividends of $268 million. Payouts are funded from operating cash flow and debt. If capex stays at $5.0 billion a year, the dividend will grow more slowly than the company promises or will require further debt increases.
At 13.6 EV/EBITDA and 12% upside on the portal model, the share remains attractive
The EV/EBITDA LTM multiple is 13.6 and P/E LTM is 24.0. Return on equity is 70.5%, reflecting a high share of debt capital and efficient use of assets. Market capitalization is $58.7 billion.
On the portal model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, the upside to fair value is +12%. This is the portal's own estimate, not a market consensus.
Since the report was published the share has fallen 3.9%, the same as on the publication day. The market reaction reflects disappointment over lower margin and free cash flow. However, record volumes, the ExxonMobil contracts and the 20% dividend increase in 2027 create a base for valuation recovery.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 58.7 bn USD |
| P/E (LTM) | 24.0 |
| EV/EBITDA (LTM) | 13.6 |
| P/B | 18.36 |
| Net debt / EBITDA (LTM) | 3.39 |
| Operating cash flow (LTM) | 5.05 bn |
| ROE | 70.5% |
Bottom line
The strong points of the report were record Permian and logistics volumes and revenue growth of 34.9%, which accelerated from the second quarter. However, EBITDA margin fell to 27.8% and free cash flow shrank to $33.6 million, which does not cover dividends. Debt rose to $19.1 billion, with net debt/EBITDA LTM at 3.39. At 13.6 EV/EBITDA and 12% upside on the portal model, the share looks rather attractive, but the key question for a holder is whether the company can restore margin and cash flow while maintaining capex.
Open the company's financial profile TRGP →
See also: market overview · valuation map · stock screeners