Exxon Mobil: profit doubled, but the multiple sits 54% above its own history
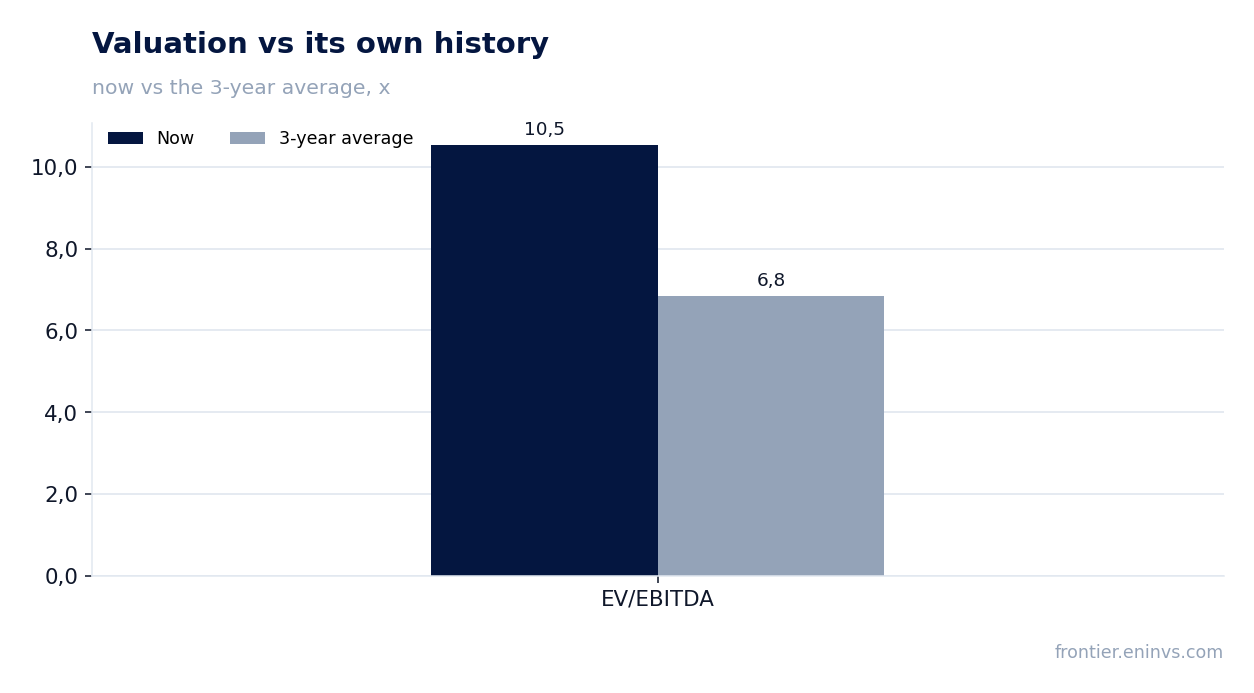
On 2 November Exxon Mobil reported results for the third quarter of 2026. Revenue came in at USD 113.2 bn (+32.7% year on year), net profit at USD 15.4 bn (+104.2%), and operating cash flow at USD 25.7 bn with capital expenditures of USD 7.2 bn. Net debt fell to USD 22.1 bn at 30 September from USD 31.8 bn at the end of June. Despite the strong report, the share looks rather unattractive: EV/EBITDA LTM of 10.5 is 54% above its own three-year average of 6.8, and the portal's model implies downside of 39%.
Key takeaways
— Revenue grew 32.7% year on year, but the pace decelerated from 42.3% a quarter earlier
— Net profit doubled to USD 15.4 bn, with the margin rising from 8.8% to 13.6%
— Cash flow of USD 25.7 bn covered capital expenditures of USD 7.2 bn with room to spare
— Net debt fell to USD 22.1 bn from USD 31.8 bn at the end of June
— A dividend yield of 2.3% is modest against the share price
— EV/EBITDA LTM of 10.5 is 54% above its own three-year average of 6.8
— The portal's model implies 39% downside for the share
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 85.3 | 113 | +32.7% |
| EBITDA | 17.4 | — | — |
| Operating profit | 10.9 | — | — |
| Net profit | 7.55 | 15.4 | +104.2% |
| Operating cash flow | 14.8 | 25.6 | +73.5% |
| Capex | 8.73 | 7.18 | -17.7% |
| EBITDA margin | 20.4% | — | — |
| Net margin | 8.8% | 13.6% | +4.8 pp |
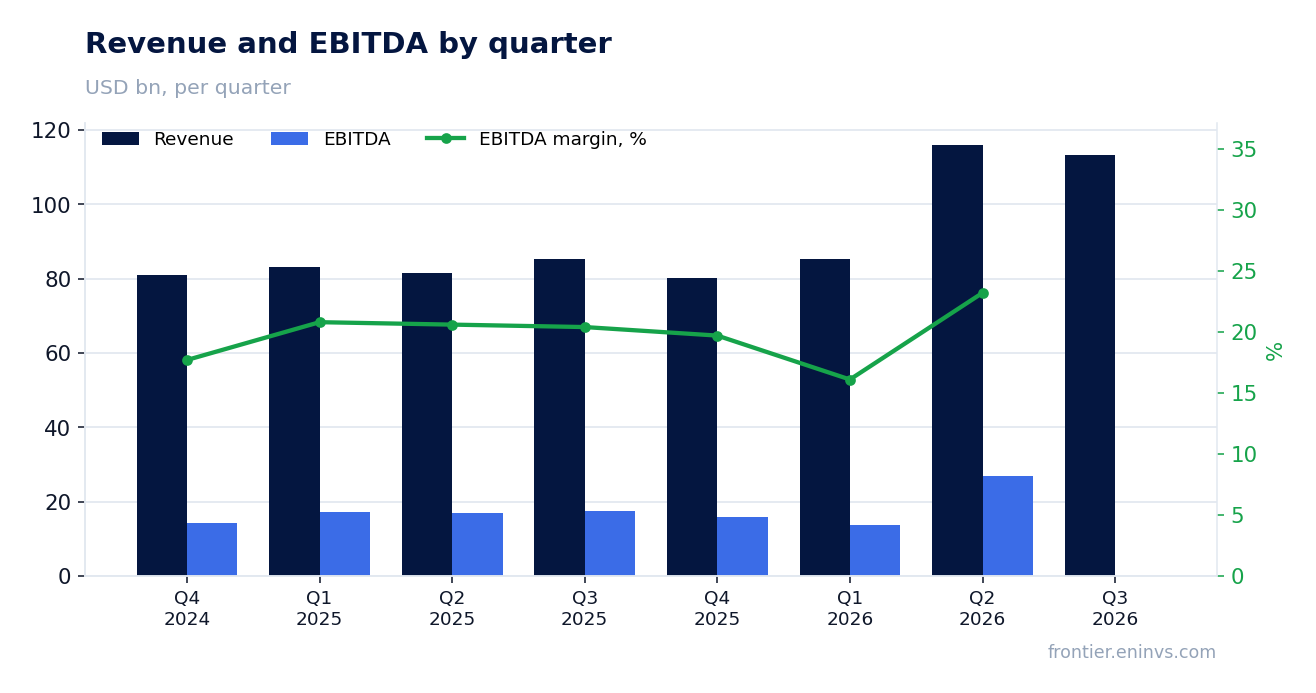
Revenue grew 32.7% year on year, but the pace decelerated from 42.3% a quarter earlier
In the third quarter of 2026 Exxon Mobil's revenue reached USD 113.2 bn, 32.7% more than a year earlier. This is the second consecutive quarter of double-digit growth: in the second quarter the top line added 42.3%.
The deceleration from 42.3% to 32.7% shows the growth rate has started to ease. The absolute level remains high, though – USD 113.2 bn against USD 85.3 bn in the third quarter of 2025.
The facts provided do not disclose the causes of the slowdown. What is visible is that growth remains solid but is no longer as fast as a quarter earlier.
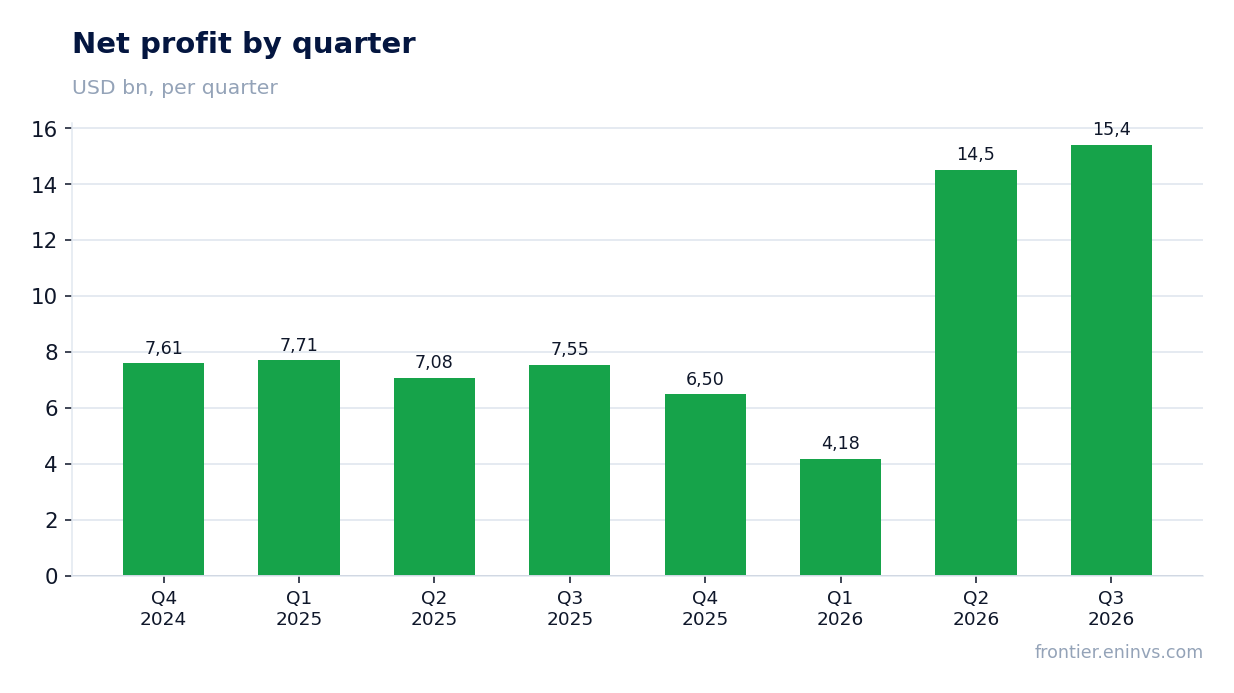
Net profit doubled to USD 15.4 bn, with the margin rising from 8.8% to 13.6%
Net profit for the third quarter of 2026 reached USD 15.4 bn, 104.2% more than a year earlier. Profit growth was more than twice as fast as revenue growth.
The net margin rose to 13.6% from 8.8% a year earlier. Such a margin expansion on revenue that grew 32.7% means costs rose more slowly than income.
The facts do not disclose which cost lines drove the margin gain. What can be said with confidence is that profit grew faster than revenue, and that is the main positive of the report.
Cash flow of USD 25.7 bn covered capital expenditures of USD 7.2 bn with room to spare
Operating cash flow for the third quarter of 2026 was USD 25.7 bn, capital expenditures were USD 7.2 bn. Free cash flow before dividends exceeded USD 18 bn.
Such a cushion means the company funds investment from its own resources and still leaves a substantial amount for shareholder payouts and debt reduction.
For an oil and gas company this is a sustainable picture: cash flow covers capital expenditures with room to spare, not the other way round.
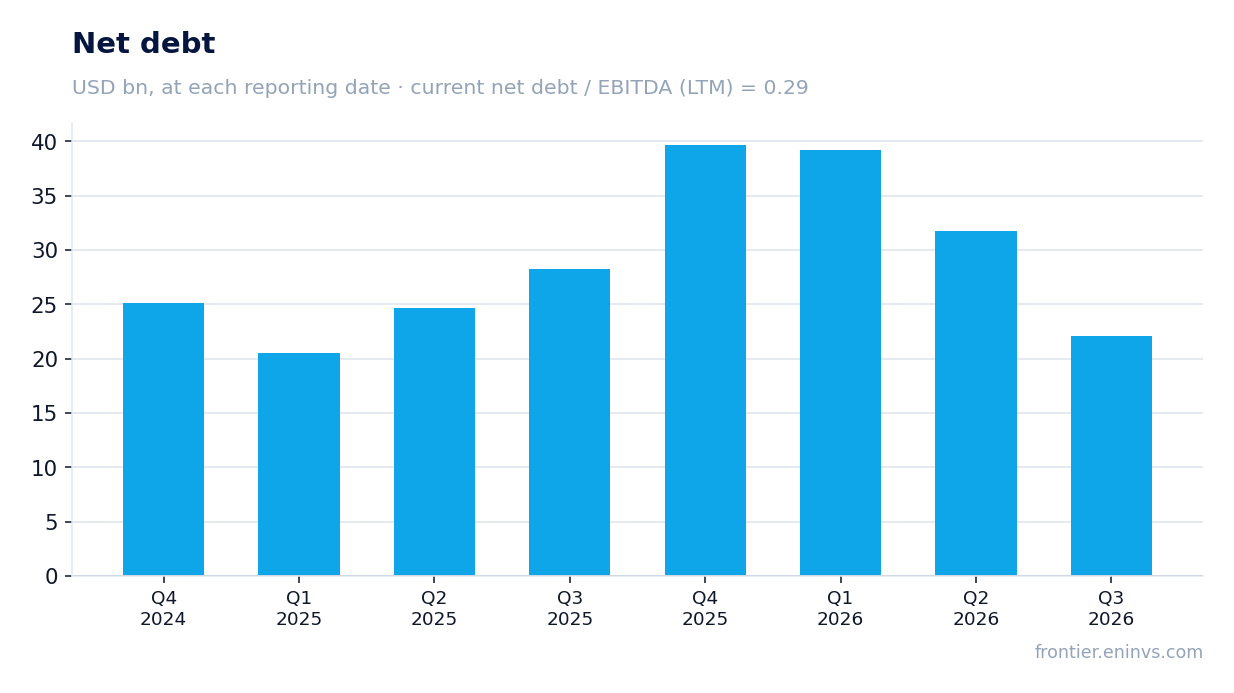
Net debt fell to USD 22.1 bn from USD 31.8 bn at the end of June
Net debt at 30 September 2026 was USD 22.1 bn, down from USD 31.8 bn at 30 June 2026 – a reduction of USD 9.7 bn over the quarter.
Over twelve months net debt fell from USD 28.2 bn at 30 September 2025 to USD 22.1 bn at 30 September 2026 – a reduction of USD 6.1 bn.
The ratio of net debt to EBITDA LTM stands at 0.29, a low level for the sector. The direction of change in this ratio is not disclosed in the facts, so only its current level can be stated.
A dividend yield of 2.3% is modest against the share price
Exxon Mobil's dividend yield over the last twelve months is 2.3%. With a market capitalisation of USD 755.7 bn, that is about USD 17.3 bn of payouts.
Our estimate for the current year's dividend assumes the current per-share payout is maintained. It rests on LTM profit of USD 40.6 bn and cash flow that covers capital expenditures with room to spare.
A yield of 2.3% is lower than one might expect from an oil and gas company with such cash flow. The reason is the high valuation: the market pays dearly for earnings, and the yield compresses.
A fall in profit or a rise in capital expenditures could reduce the payout. For now, quarterly cash flow of USD 25.7 bn gives the company room to manoeuvre.
EV/EBITDA LTM of 10.5 is 54% above its own three-year average of 6.8
The EV/EBITDA LTM multiple stands at 10.5 against its own three-year average of 6.8. The share trades 54% above its average over the last three years.
P/E LTM is 18.6. With a return on equity of 23.5% the company earns well, but the market has already priced that in.
The portal's model, repriced to current commodity prices at the target EV/EBITDA, implies 39% downside to fair value. This is our own estimate, not a market consensus.
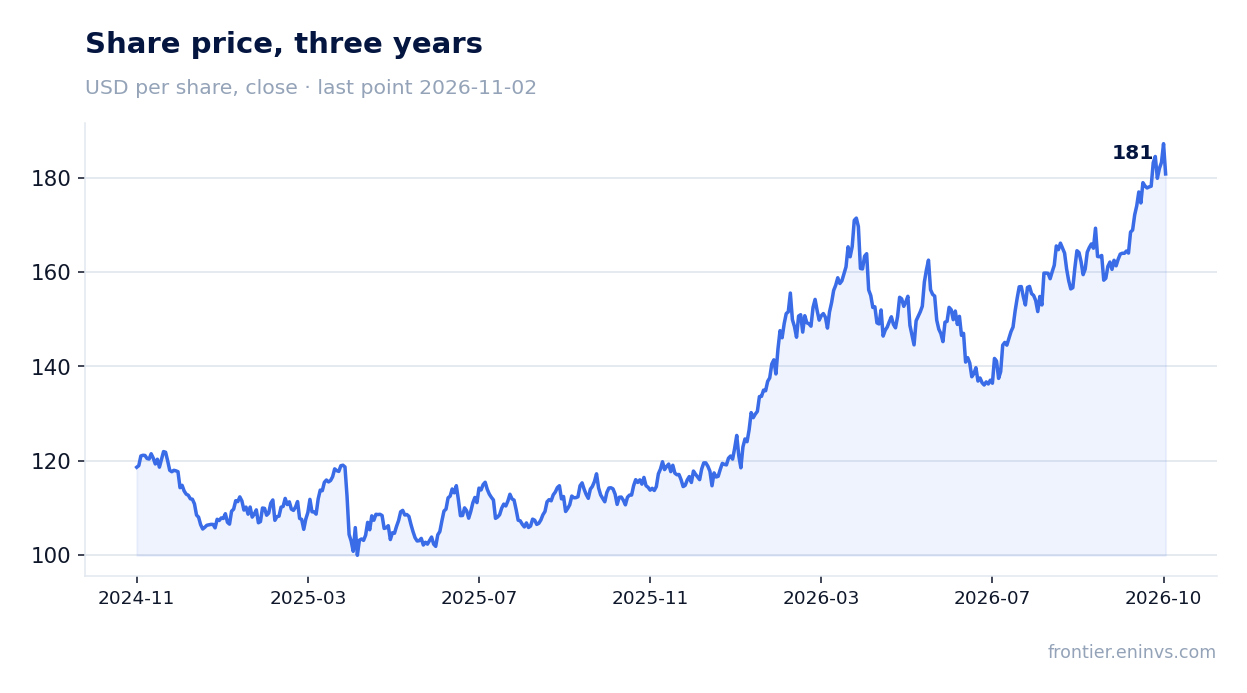
The share closed up 2.2% on the day of the report but has lost 1.3% from the release to 2 November. The market's reaction to the strong results was muted.
The portal's model implies 39% downside for the share
The portal's model reprices EBITDA at current commodity prices and applies the target EV/EBITDA. With a market capitalisation of USD 755.7 bn, that implies fair value 39% below the current price.
The gap is explained by the market valuing Exxon Mobil well above its own history. If commodity prices do not rise, the multiple has room to fall.
The next report will show whether revenue and margin growth persist. The deceleration from 42.3% to 32.7% is the first signal that the growth peak may have passed.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 756 bn USD |
| P/E (LTM) | 18.6 |
| EV/EBITDA (LTM) | 10.5 |
| P/B | 2.91 |
| Net debt / EBITDA (LTM) | 0.29 |
| Operating cash flow (LTM) | 70.6 bn |
| ROE | 23.5% |
| Dividend yield (12m) | 2.3% |
| EV/EBITDA, 3-year average | 6.8 |
Bottom line
The strong side of the report is profit: USD 15.4 bn for the quarter, double the prior year, with a margin of 13.6% against 8.8%. Cash flow of USD 25.7 bn covers capital expenditures of USD 7.2 bn with room to spare, and net debt fell to USD 22.1 bn from USD 31.8 bn at the end of June. But revenue growth decelerated from 42.3% to 32.7%, and the EV/EBITDA multiple of 10.5 is 54% above its own three-year average. With a dividend yield of 2.3% and 39% downside on the portal's model, the share looks rather unattractive at the current price.
Open the company's financial profile XOM →
See also: market overview · valuation map · stock screeners