ID_BYAN: $179.4m profit on $694.1m revenue – margin holds, but cash flow is not disclosed
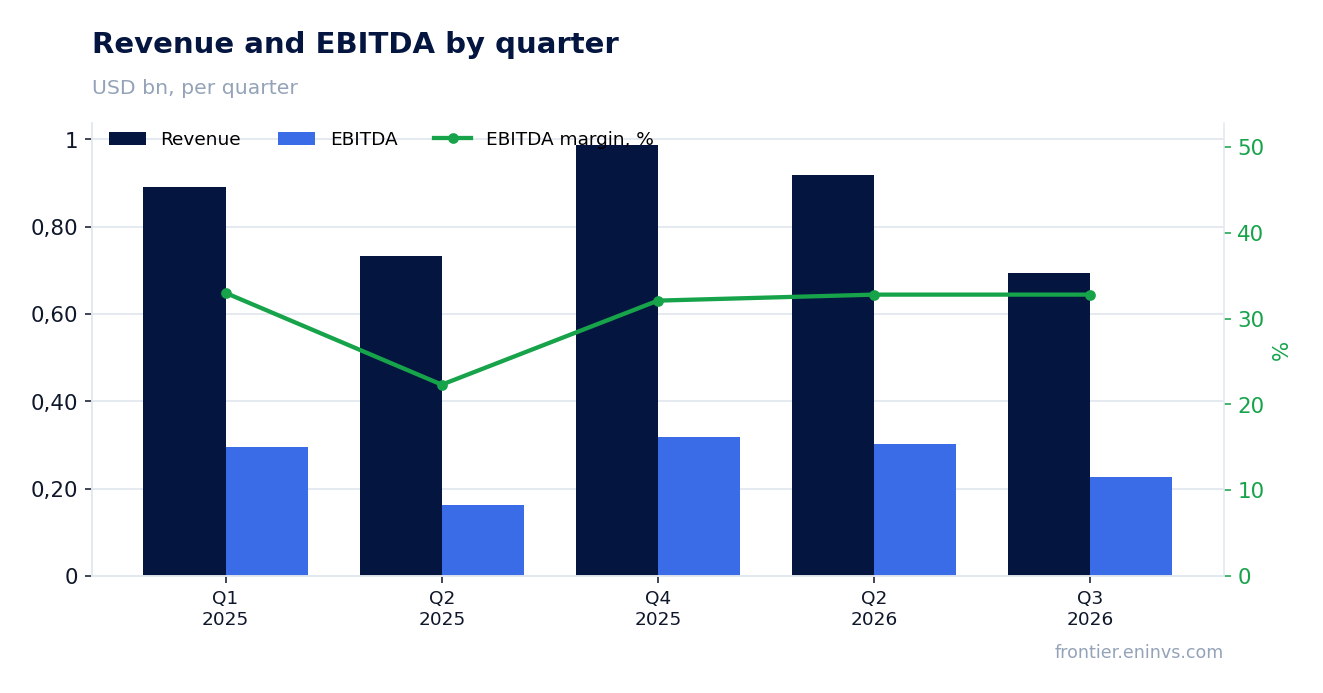
On 30 September 2026 ID_BYAN reported third-quarter 2026 results: revenue of $694.1m, EBITDA of $233.4m and net profit of $179.4m. The EBITDA margin was 33.6% and the net margin 25.8%, while net debt at period end remains negative at -$620.4m. The share looks attractive at the current price: the portal's model puts upside to fair value at +24%, with a 2.9% dividend yield and a 27.4% return on equity.
Key takeaways
— Revenue of $694.1m against EBITDA of $233.4m – the 33.6% margin holds at the level the company has shown for several quarters
— Net profit of $179.4m is 25.8% of revenue, and the gap to EBITDA is small, so interest and taxes take little away
— Negative net debt of -$620.4m at 30 September 2026 – the company sits on a cash cushion rather than servicing borrowings
— Return on equity of 27.4% on a $16.8bn market cap – the business earns on equity above the cost of money
— A 2.9% trailing dividend yield – the payout is modest relative to profit but steady
— On the portal's model the share trades at a 24% discount to fair value recalculated at current commodity prices
Attractiveness
Key figures, USD bn
| Metric | — | Q3 2026 | Change |
|---|---|---|---|
| Revenue | — | 0.69 | — |
| EBITDA | — | 0.23 | — |
| Operating profit | — | 0.23 | — |
| Net profit | — | 0.18 | — |
| EBITDA margin | — | 33.6% | — |
| Net margin | — | 25.8% | — |
Revenue of $694.1m against EBITDA of $233.4m – the 33.6% margin holds at the level the company has shown for several quarters
In the third quarter of 2026 ID_BYAN generated revenue of $694.1m and EBITDA of $233.4m. Operating profit almost matched EBITDA at $227.0m, so depreciation is small this period and most costs already sit in cost of sales.
The 33.6% EBITDA margin is not a one-off spike: the company has held such profitability over recent quarters, pointing to a stable cost structure. Revenue is lower than in the second quarter of 2026 ($918.5m), but quarters within a year cannot be compared – seasonality and one-off conditions distort the picture.
What matters for an investor is that the margin does not erode when revenue falls: variable costs are small and fixed costs are already covered. That gives the company a cushion even in a weak quarter.
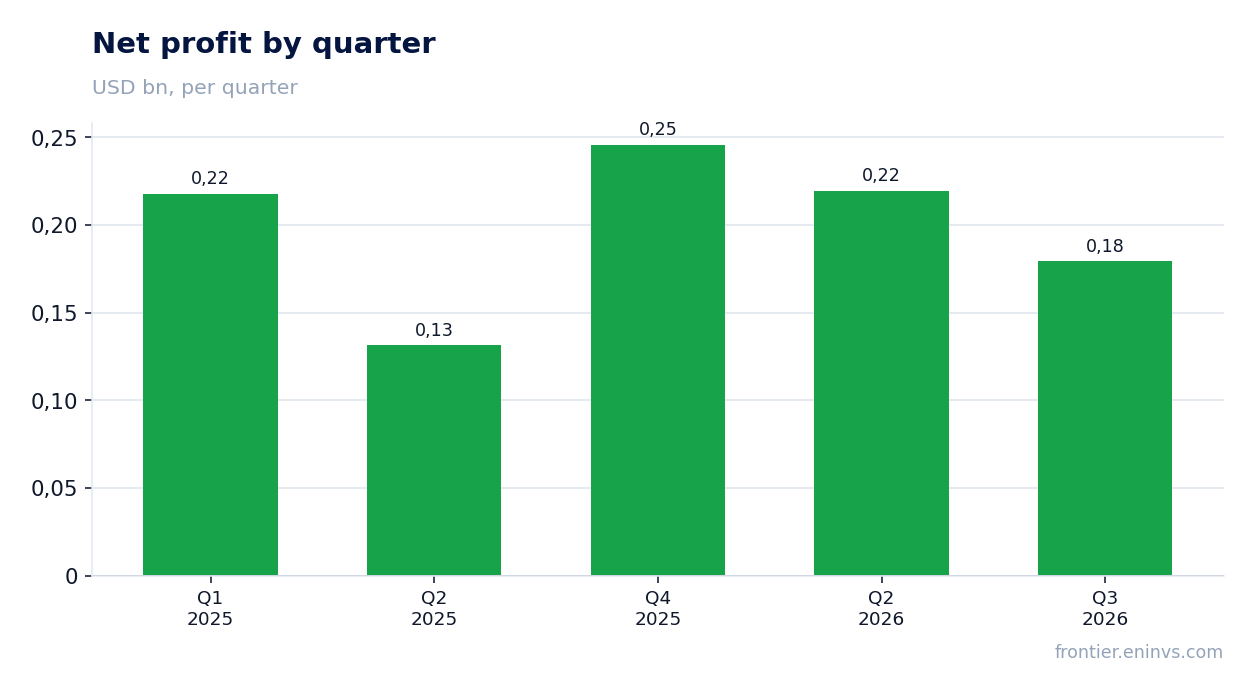
Net profit of $179.4m is 25.8% of revenue, and the gap to EBITDA is small, so interest and taxes take little away
Net profit for the third quarter of 2026 was $179.4m on revenue of $694.1m – a 25.8% net margin. Most of the $233.4m EBITDA reaches net profit: the $54.0m gap covers taxes and interest but does not create a loss.
This ratio is explained by negative net debt: the company pays no meaningful interest on borrowings and rather earns income on its cash cushion. Net profit therefore almost mirrors operating dynamics.
Return on equity of 27.4% on a $16.8bn market cap confirms the business earns above its cost of capital. For a shareholder this means profit is not eaten by interest and taxes.
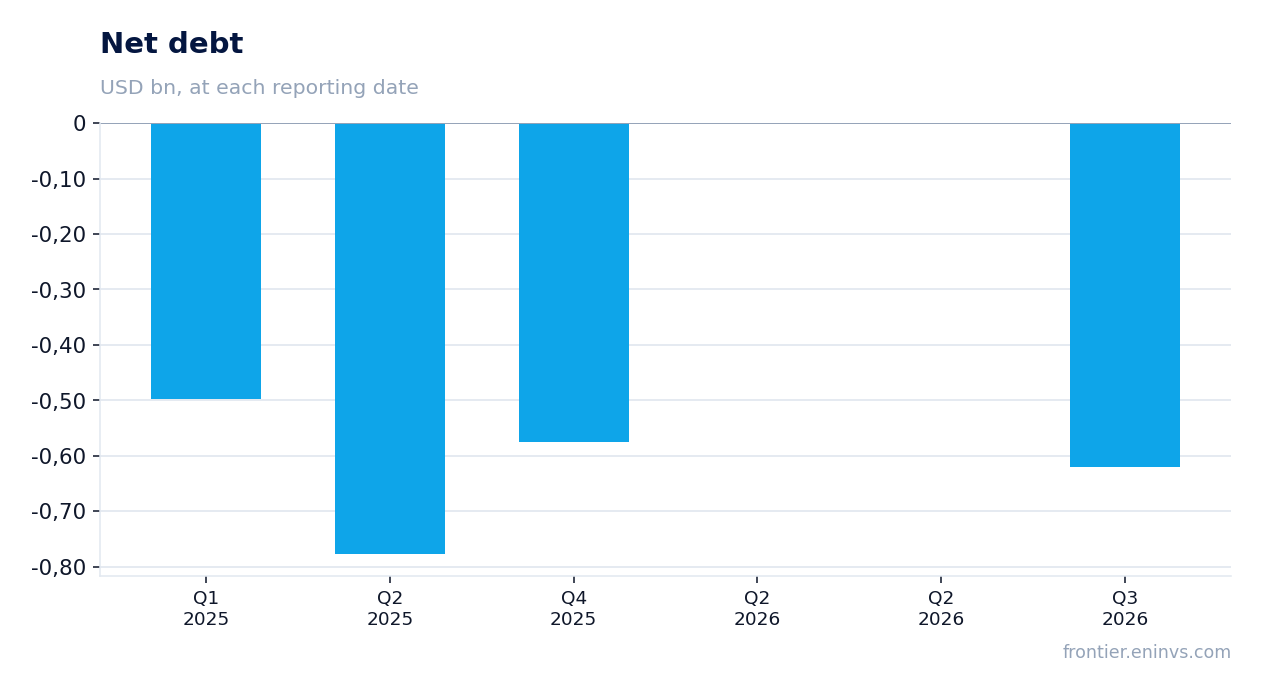
Negative net debt of -$620.4m at 30 September 2026 – the company sits on a cash cushion rather than servicing borrowings
At 30 September 2026 ID_BYAN's net debt was -$620.4m. A year earlier, at 30 June 2025, it was -$777.98m, so over 12 months the cash cushion shrank by $0.2bn – from -$0.8bn to -$0.6bn.
A smaller cushion does not mean higher leverage: the company still has negative net debt, meaning more cash than liabilities. Over the quarter from 30 June 2026 net debt moved from $0.0bn to -$0.6bn, so the company increased its cash position.
For an investor this means interest costs are minimal and financial flexibility is preserved. Even with lower revenue the company can cover expenses from accumulated funds.
Return on equity of 27.4% on a $16.8bn market cap – the business earns on equity above the cost of money
ID_BYAN's return on equity is 27.4% – a high figure showing the company uses shareholder capital efficiently. With a market cap of $16.8bn, trailing twelve-month revenue is $2.0bn, but the exact LTM profit is not disclosed in the facts.
High return on equity is supported by negative net debt: the company carries no interest burden, so all operating profit works for shareholders. This creates room for dividends and buybacks.
It is worth remembering that return on equity can be inflated by balance-sheet structure – with negative debt the denominator (equity) is smaller than it would be with borrowings. Still, 27.4% is a strong figure for any industry.
A 2.9% trailing dividend yield – the payout is modest relative to profit but steady
ID_BYAN's trailing twelve-month dividend yield is 2.9%. That is modest relative to the 25.8% net margin and 27.4% return on equity – the company retains most of its profit.
Our estimate for the current year's dividend assumes the payout ratio stays at prior levels: with quarterly net profit of $179.4m, annual profit could be around $700m, and at a payout ratio near 40% the dividend per share would correspond to a yield of about 2.9% on the current price. This is our estimate, not company guidance.
A 2.9% yield is below the key rate, but for a company with negative debt and high return on equity that is normal: the investor gets return through capitalisation growth. A smaller payout could come from lower profit or higher capex, which the report does not disclose.
On the portal's model the share trades at a 24% discount to fair value recalculated at current commodity prices
On the portal's model, which recalculates EBITDA at current commodity prices and a target EV/EBITDA multiple, ID_BYAN's fair value is 24% above the current market price. This is our own estimate, not a market consensus or a target price.
The model relies on the stable 33.6% EBITDA margin and negative net debt, which support the valuation. With a market cap of $16.8bn and trailing twelve-month EBITDA not fully disclosed in the facts, the EV/EBITDA multiple looks moderate.
The +24% upside makes the share attractive for an investor who believes current commodity prices will hold. If commodity prices fall, the model will revise fair value lower and the discount may disappear.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 16.8 bn USD |
| P/B | 6.50 |
| ROE | 27.4% |
| Dividend yield (12m) | 2.9% |
Bottom line
The report's strength is the stable 33.6% EBITDA margin and 25.8% net margin, which the company holds even as revenue falls to $694.1m. Negative net debt of -$620.4m and a 27.4% return on equity confirm financial stability. The weak spot is the lack of cash flow and capex disclosure, plus a modest 2.9% dividend yield. On the portal's model the share trades at a 24% discount to fair value, making it attractive at the current price.
Open the company's financial profile BYAN →
See also: market overview · valuation map · stock screeners