Profit rose 6.9%, but a 3.3% dividend yield and a discount to its own history make the share interesting
On 25 November ID_MIKA released results for the nine months of 2026: revenue grew 7.2% year on year, net profit rose 6.9%, and the net margin stayed essentially flat at 27.1%. The company keeps a negative net debt of –2,508.8 bn IDR as of 30 September 2026, while the EV/EBITDA LTM multiple of 7.7x is well below its own three-year average of 16.4x. With a 3.3% dividend yield and a +9% upside on the portal's model, the share looks attractive at the current price.
Key takeaways
— Revenue for the nine months of 2026 grew 7.2% year on year to 4,267.5 bn IDR
— Net profit added 6.9% year on year, while the margin stayed at 27.1%
— Operating cash flow for the nine months of 2026 reached 1,338.1 bn IDR, with capex of 237.7 bn IDR in the first quarter
— A 3.3% dividend yield provides a steady return of capital with a payout ratio the company keeps stable
— EV/EBITDA LTM of 7.7x is 53% below its own three-year average of 16.4x, pointing to undervaluation
— The portal's model puts the upside to fair value at +9%
Attractiveness
Key figures, IDR bn
| Metric | 9M 2025 | 9M 2026 | Change |
|---|---|---|---|
| Revenue | 3 981 | 4 267 | +7.2% |
| EBITDA | 1 535 | — | — |
| Operating profit | 1 282 | — | — |
| Net profit | 1 082 | 1 156 | +6.9% |
| Operating cash flow | 1 333 | 1 338 | +0.4% |
| EBITDA margin | 38.6% | — | — |
| Net margin | 27.2% | 27.1% | -0.1 pp |
Revenue for the nine months of 2026 grew 7.2% year on year to 4,267.5 bn IDR
Revenue for the nine months of 2026 reached 4,267.5 bn IDR, 7.2% above the same period last year. Growth remains moderate but steady: the company is expanding without sharp jumps.
In the first quarter of 2026 revenue was 1,356.5 bn IDR, up 6.6% year on year. This sets the tone for the whole report: revenue dynamics stay in positive territory, though they are not accelerating.
The main contribution to growth, given the scale of the business, comes from current operations. Segment detail is not disclosed in the facts, so we limit ourselves to stating the overall trend.
Net profit added 6.9% year on year, while the margin stayed at 27.1%
Net profit for the nine months of 2026 reached 1,156.4 bn IDR, up 6.9% year on year. The net margin stayed essentially flat – 27.1% versus 27.2% a year earlier.
Margin stability suggests that revenue growth is not accompanied by a deterioration in cost control. The company keeps profitability at a high level, which is a positive signal in a market with rising costs.
The gap between revenue and profit growth is minimal, confirming the absence of one-off items distorting the result. Profit grows with the business, not through asset sales or other non-operating items.
Net debt as of 30 September 2026 stood at –2,508.8 bn IDR, meaning the company has a net cash position. Since the end of June 2026 the figure moved from –2,843.2 bn IDR to –2,508.8 bn IDR, a change of +334.4 bn IDR.
Over the year, from 30 September 2025, net debt moved from –1,921.5 bn IDR to –2,508.8 bn IDR, a change of –587.3 bn IDR. The negative value means cash and equivalents exceed debt obligations.
The net debt to EBITDA LTM ratio is –1.18, confirming the absence of leverage. The company does not depend on borrowed funds and retains a cushion for investment or shareholder payouts.
Operating cash flow for the nine months of 2026 reached 1,338.1 bn IDR, with capex of 237.7 bn IDR in the first quarter
Operating cash flow for the nine months of 2026 reached 1,338.1 bn IDR, exceeding net profit for the same period. This indicates high earnings quality: the company not only reports profit but converts it into real cash.
Capex in the first quarter of 2026 was 237.7 bn IDR, roughly 17.5% of operating cash flow for the nine months. This level of investment does not pressure liquidity.
Free cash flow remains positive, allowing the company to fund dividends and maintain negative net debt. Combined with the absence of leverage, this provides a stable base for returning capital to shareholders.
A 3.3% dividend yield provides a steady return of capital with a payout ratio the company keeps stable
The dividend yield over the last 12 months is 3.3%. This is a moderate but stable level that the company can sustain thanks to strong cash flow and the absence of leverage.
Our estimate for the current year's dividend assumes the current payout ratio and profit at the level of the nine months of 2026. With net profit of 1,156.4 bn IDR for the nine months and a stable payout policy, the dividend should stay near the current level.
The 3.3% yield is comparable to the key rate, but given the business growth potential and the discount to its own history, the share offers an attractive combination of current income and capital growth. A decline in profit or a rise in capex could reduce the payout.
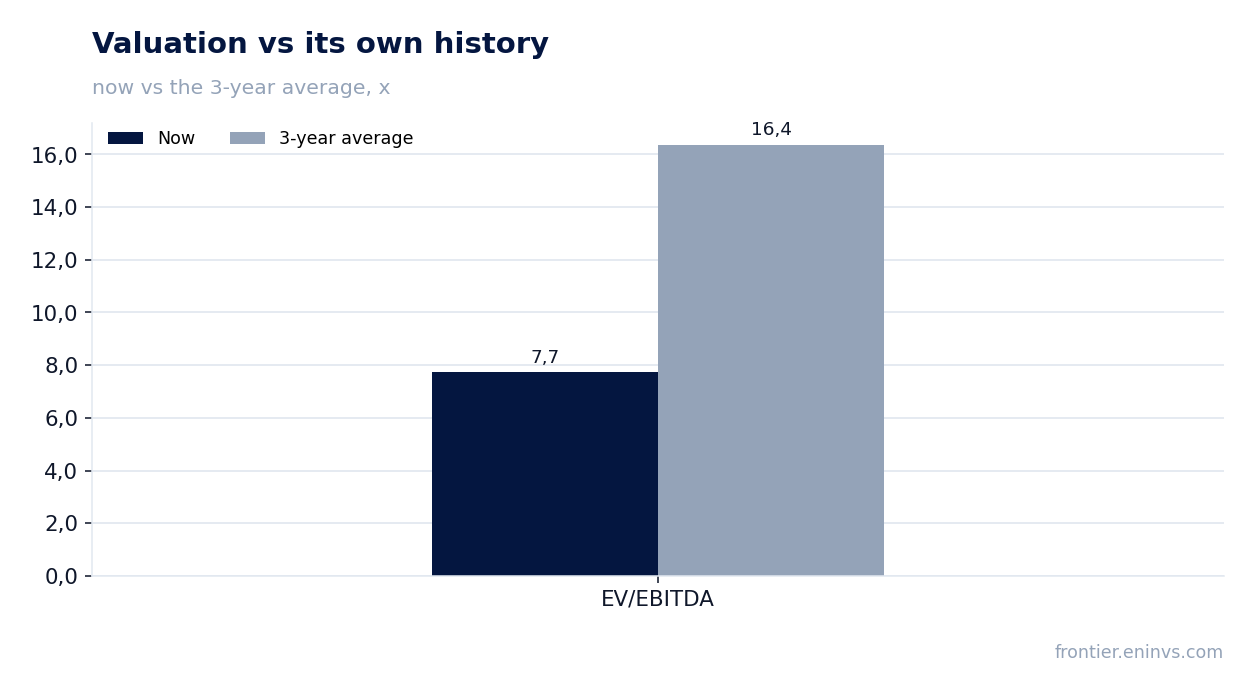
EV/EBITDA LTM of 7.7x is 53% below its own three-year average of 16.4x, pointing to undervaluation
The EV/EBITDA LTM multiple is 7.7x, 53% below its own three-year average of 16.4x. The share trades significantly cheaper than historically, creating room for re-rating.
P/E LTM is 12.6x, which also looks moderate against the profitability and growth rates. The market capitalisation of 19.0 bn IDR against a net cash position of 2,508.8 bn IDR reflects a conservative valuation of the business.
The portal's model puts the upside to fair value at +9%. This is our own calculation based on EBITDA growth and the target multiple, and it is not a market consensus.
The portal's model puts the upside to fair value at +9%
On the portal's model, the fair value of the share implies +9% upside to the current price. The calculation is based on EBITDA growth and the target multiple we apply to the company.
This estimate is not a target price and does not reflect market consensus. It shows how far the current price is from what we consider justified by fundamentals.
The share is held in live model strategies on the portal, in particular ID FVC (quality). This is a fact, not an argument for the verdict: inclusion in a strategy reflects meeting the selection criteria, not an assessment of attractiveness.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 19 030 bn IDR |
| P/E (LTM) | 12.6 |
| EV/EBITDA (LTM) | 7.7 |
| P/B | 2.62 |
| Net debt / EBITDA (LTM) | -1.18 |
| Operating cash flow (LTM) | 1 940 bn |
| ROE | 20.5% |
| Dividend yield (12m) | 3.3% |
| EV/EBITDA, 3-year average | 16.4 |
Bottom line
The report for the nine months of 2026 showed steady revenue growth of 7.2% and profit growth of 6.9% while maintaining a high margin of 27.1%. The company retains negative net debt of –2,508.8 bn IDR and generates strong operating cash flow of 1,338.1 bn IDR. A 3.3% dividend yield and an EV/EBITDA discount of 53% to its own three-year history make the share attractive for income- and growth-oriented investors. The key question for a holder is whether current profit dynamics and payout policy will hold amid a possible economic slowdown.
Open the company's financial profile MIKA →
See also: market overview · valuation map · stock screeners