Infosys: revenue barely grows while margin gains come from costs
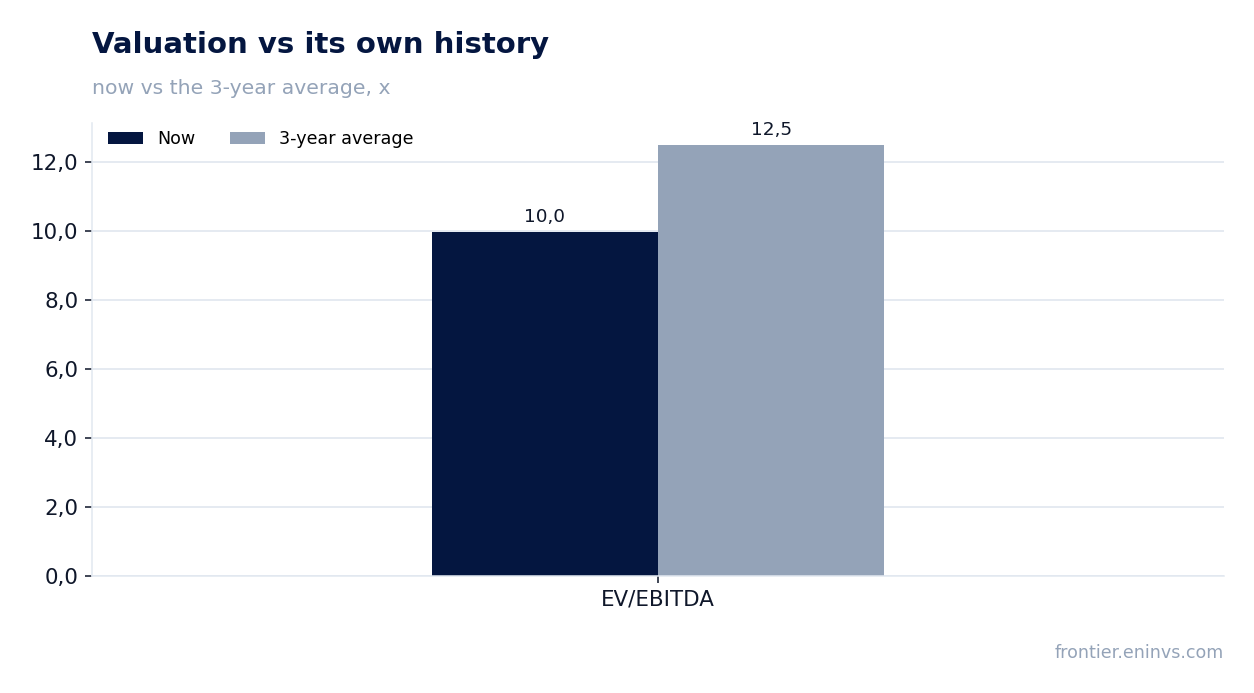
Infosys reported revenue of USD 5,145 mn for the quarter ended September 2026, up just 1.4% year on year. EBITDA rose 9.2% to USD 1,227 mn and the margin improved to 25.5% from 23.6%, but net profit fell 2.6% to USD 817 mn. At an EV/EBITDA of 10.0 against its own three-year average of 12.5 the share looks cheaper than its history, yet weak revenue growth and falling net profit leave little room for optimism – the verdict is neutral.
Key takeaways
— Revenue grew only 1.4% year on year, a deceleration from 2.9% a quarter earlier
— EBITDA rose 9.2% on nearly flat revenue, lifting the margin to 25.5%
— Net profit fell 2.6% to USD 817 mn even as EBITDA grew
— Free cash flow for the quarter was USD 1,100 mn on capital expenditure of USD 86 mn
— Net debt is negative at USD 1,605 mn, or minus 0.34 times LTM EBITDA
— Dividend yield is 2.1%, with payouts covered by LTM profit of USD 3,301 mn
— EV/EBITDA of 10.0 is 20% below its own three-year average of 12.5
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 5.08 | 5.14 | +1.4% |
| EBITDA | 1.20 | 1.31 | +9.2% |
| Operating profit | 1.06 | 1.08 | +1.9% |
| Net profit | 0.84 | 0.82 | -2.6% |
| Operating cash flow | 1.16 | 1.01 | -12.4% |
| Capex | 0.06 | -0.09 | -253.6% |
| EBITDA margin | 23.6% | 25.5% | +1.9 pp |
| Net margin | 16.5% | 15.9% | -0.6 pp |
Revenue grew only 1.4% year on year, a deceleration from 2.9% a quarter earlier
Infosys revenue for the quarter ended September 2026 was USD 5,145 mn, up 1.4% year on year. That is well below the 2.9% growth of the previous quarter: the pace decelerated. Sequentially, revenue rose just USD 63 mn from USD 5,082 mn in June.
Over the trailing twelve months revenue reached USD 20,400 mn. The company is expanding slowly, with year-on-year quarterly growth holding in a 1.4–2.9% range over recent periods. This points to a mature business where the main growth phase is behind it.
EBITDA rose 9.2% on nearly flat revenue, lifting the margin to 25.5%
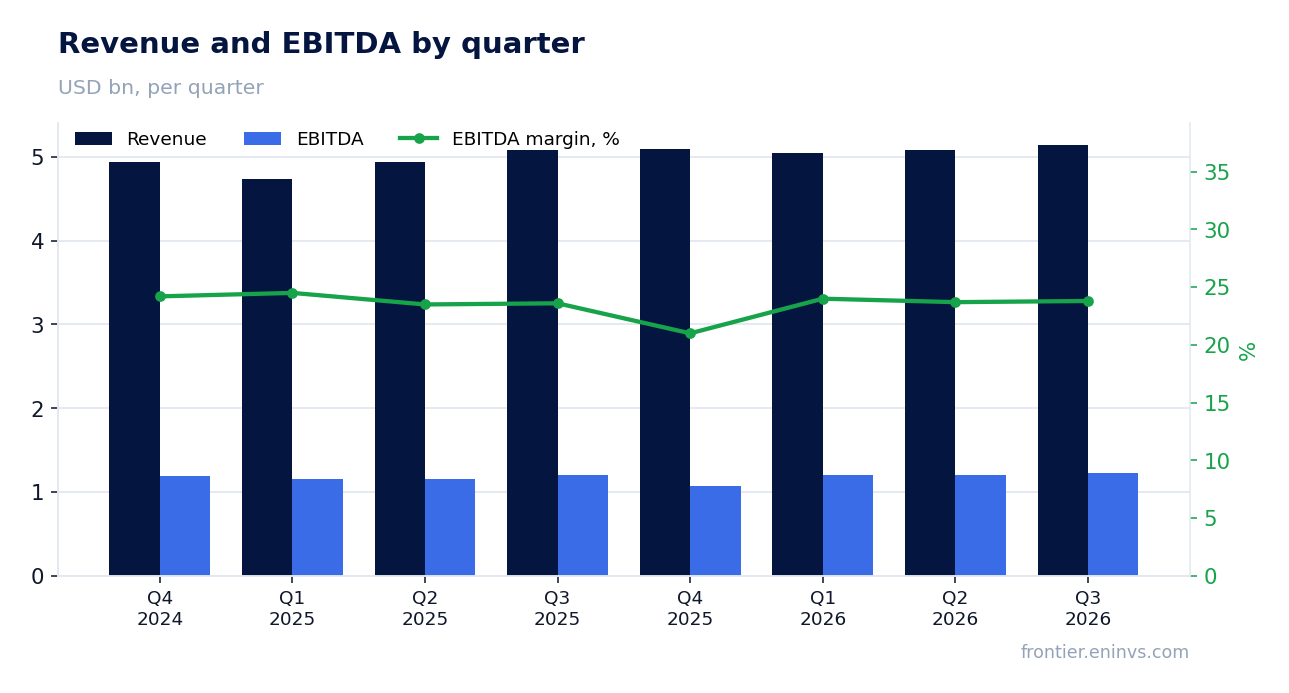
EBITDA for the quarter was USD 1,227 mn, up 9.2% year on year. With revenue growing just 1.4%, this implies the company cut costs or improved its expense mix. The EBITDA margin rose to 25.5% from 23.6% a year earlier.
Operating profit was USD 1,085 mn, or about 21.1% of revenue. Margin expansion on weak revenue is the main positive of the report, but its durability depends on whether it stems from one-off measures rather than a fundamental cost reduction.
Net profit fell 2.6% to USD 817 mn even as EBITDA grew
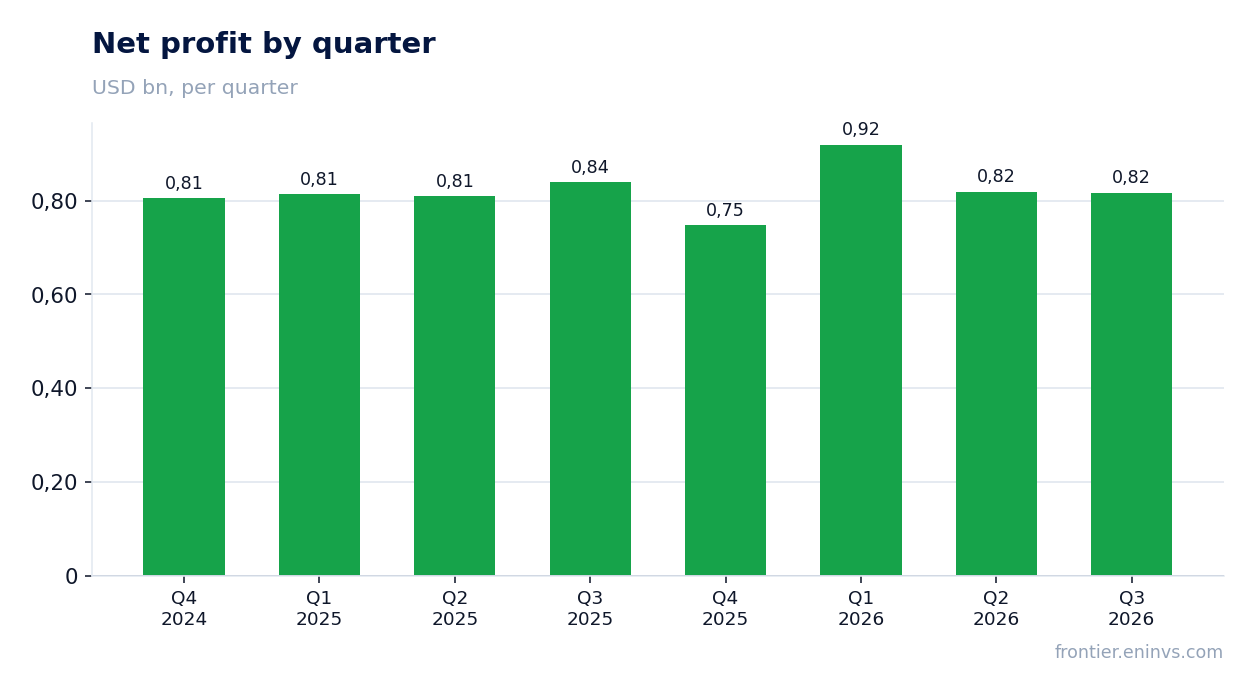
Net profit for the quarter was USD 817 mn versus USD 839 mn a year earlier, down 2.6%. The net margin fell to 15.9% from 16.5%. The gap versus EBITDA growth points to additional charges below the operating line – likely financial or tax-related.
Over the trailing twelve months net profit was USD 3,301 mn. Earnings per share and the dividend base rest on this figure, and its trajectory matters more than quarterly swings. Falling net profit alongside rising EBITDA signals that not all of the operating improvement reaches shareholders.
Free cash flow for the quarter was USD 1,100 mn on capital expenditure of USD 86 mn
Operating cash flow for the quarter was USD 1,014 mn. Capital expenditure was negative at minus USD 86 mn, meaning a release of funds rather than a spend. As a result free cash flow reached USD 1,100 mn, exceeding net profit for the quarter.
Over the trailing twelve months operating cash flow was USD 3,949 mn. The business generates cash steadily, and capital expenditure is small relative to revenue. This supports the ability to pay dividends and maintain a net cash position.
Net debt is negative at USD 1,605 mn, or minus 0.34 times LTM EBITDA
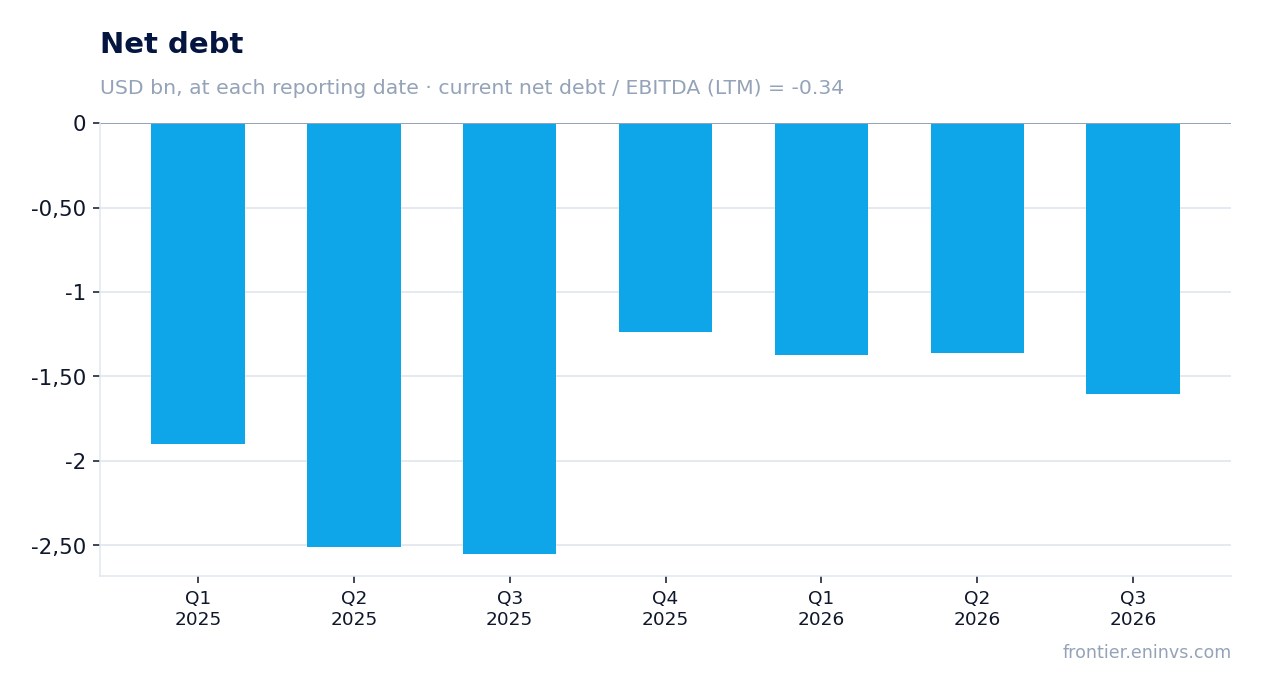
As of 30 September 2026 Infosys had negative net debt of USD 1,605 mn, meaning cash exceeded debt. The ratio of net debt to trailing-twelve-month EBITDA was minus 0.34. The company carries no debt burden.
During the quarter net debt moved from minus USD 1,364 mn on 30 June to minus USD 1,605 mn on 30 September, so the cash cushion grew by USD 241 mn. Over twelve months net debt moved from minus USD 2,553 mn on 30 September 2025 to minus USD 1,605 mn, a reduction of USD 948 mn. This reflects use of cash, but the level remains comfortable.
Dividend yield is 2.1%, with payouts covered by LTM profit of USD 3,301 mn
Infosys trailing-twelve-month dividend yield is 2.1%. Payouts rest on LTM profit of USD 3,301 mn, and the payout ratio remains moderate. The company pays dividends consistently, and negative net debt supports this.
Our estimate for the current-year dividend assumes the current payout ratio and LTM profit are maintained. The risk of a cut is tied to falling net profit – down 2.6% in the quarter. If profit continues to shrink the dividend could be revised, but coverage is sufficient for now.
EV/EBITDA of 10.0 is 20% below its own three-year average of 12.5
The trailing-twelve-month EV/EBITDA multiple is 10.0. That is 20% below its own three-year average of 12.5. The share trades cheaper than its history, partly reflecting weak revenue growth and falling net profit.
P/E LTM is 14.7, also moderate. On the portal's model the upside to fair value is 0%. This means the current price is close to the model's estimate, and room for gains is limited. A re-rating would require either a return to revenue growth or a sustained margin improvement.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 48.5 bn USD |
| P/E (LTM) | 14.7 |
| EV/EBITDA (LTM) | 10.0 |
| P/B | 4.96 |
| Net debt / EBITDA (LTM) | -0.34 |
| Operating cash flow (LTM) | 3.95 bn |
| ROE | 32.8% |
| Dividend yield (12m) | 2.1% |
| EV/EBITDA, 3-year average | 12.5 |
Bottom line
The strong side of the report is 9.2% EBITDA growth and a margin of 25.5% on nearly flat revenue, plus steady cash flow and negative net debt. The weak side is revenue deceleration to 1.4% and a 2.6% decline in net profit. The EV/EBITDA multiple of 10.0 is below its own three-year average of 12.5, but the portal's model sees no upside. For a holder the key question is whether the company can restore revenue growth rather than just cut costs.
Open the company's financial profile INFY →
See also: market overview · valuation map · stock screeners