ALSEA: revenue up just 1.7% while EBITDA jumped a third – the margin did all the work
In its third-quarter 2026 report, ended 30 September, ALSEA posted revenue of 21,396.8 mn MXN (+1.7% YoY), EBITDA of 4,195.3 mn MXN (+33.5%) and net profit of 544.8 mn MXN (+6.4%). The EBITDA gain came almost entirely from margin: it rose to 19.6% from 14.9% a year earlier, while revenue accelerated from -1.8% in the second quarter to +1.7% in the third. Leverage is moderate at 1.65 net debt to trailing-twelve-month EBITDA, and on EV/EBITDA the stock trades below its own three-year history. At the current price the share looks attractive: margin and cash flow are growing faster than revenue, and the multiple sits below its historical level.
Key takeaways
— EBITDA rose 33.5% on revenue growth of 1.7% – almost all of the gain came from margin, which rose to 19.6% from 14.9%
— Net profit added only 6.4% because interest and depreciation absorbed the EBITDA gain
— Operating cash flow for the quarter was 13,529.8 mn MXN – many times over EBITDA
— Net debt of 29.0 bn MXN at 1.65 times EBITDA – moderate leverage
— Dividend yield of 1.9% rests on profit rather than one-off items
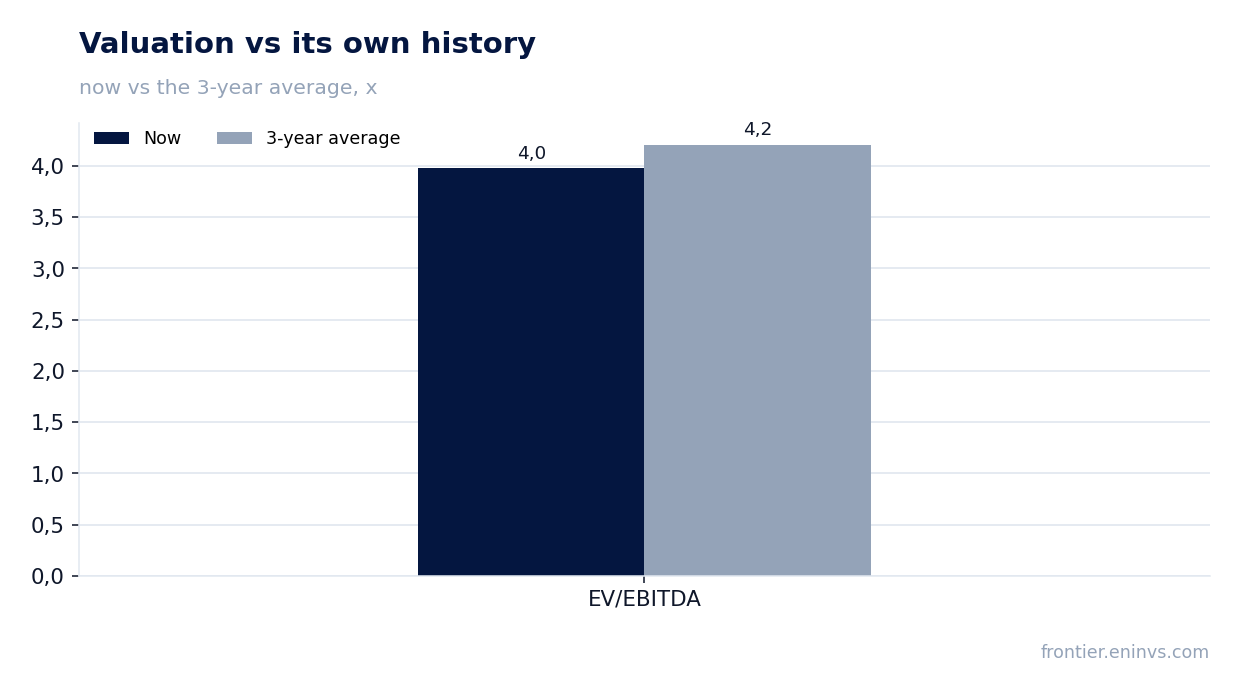
— EV/EBITDA of 4.0 is below its own three-year average of 4.2 – the stock is cheaper than its history
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 21.0 | 21.4 | +1.7% |
| EBITDA | 3.14 | 4.20 | +33.5% |
| Operating profit | 1.78 | 2.14 | +20.1% |
| Net profit | 0.51 | 0.54 | +6.4% |
| Operating cash flow | 3.71 | 13.5 | +264.9% |
| Capex | 1.21 | — | — |
| EBITDA margin | 14.9% | 19.6% | +4.7 pp |
| Net margin | 2.4% | 2.5% | +0.1 pp |
In the third quarter of 2026 revenue was 21,396.8 mn MXN, up 1.7% from a year earlier. In the second quarter the trend was negative at -1.8%, so the quarter marked an acceleration. In the first quarter growth was symbolic at +0.3%, making the third quarter the best pace since the start of the year.
The absolute increase over the year is about 368 mn MXN, small against a base of 21 bn. The facts do not disclose which segment or channel produced it, so we limit ourselves to the observation: revenue has returned to growth, but the pace remains below inflation. For a restaurant business that means traffic and average ticket together barely cover cost growth.
For further revenue growth what matters is not the quarter itself but whether the positive trend holds in the fourth quarter, which is traditionally stronger. If the pace stays at 1–2%, the entire burden of improving the result falls on margin, and its reserves are not endless.
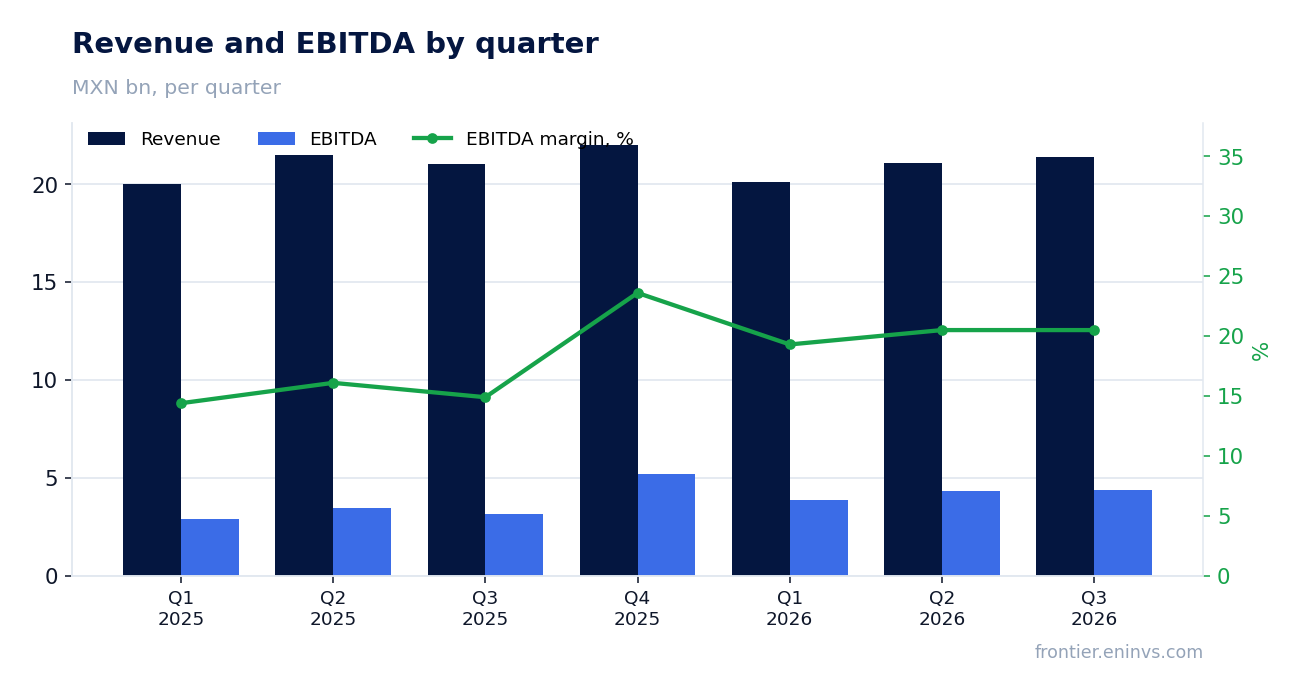
EBITDA rose 33.5% on revenue growth of 1.7% – almost all of the gain came from margin, which rose to 19.6% from 14.9%
EBITDA for the third quarter of 2026 was 4,195.3 mn MXN against 3,142.0 mn a year earlier – growth of 33.5%. With revenue up only 1.7%, such a jump means the EBITDA margin rose to 19.6% from 14.9%. That is an expansion of 4.7 percentage points – the central fact of the report.
The 1,053 mn MXN increase in EBITDA is almost unrelated to volume: had the margin stayed at 14.9%, EBITDA would have grown by roughly 55 mn. The rest is the effect of costs that did not keep pace with revenue. The facts do not disclose which cost line produced the saving, so naming a specific cause would be a guess.
The durability of this margin is the key question. One-off savings on staff or rent may not repeat, and EBITDA would then return to earlier levels. But even partial retention of a margin above 18% would deliver annual EBITDA noticeably above last year's.
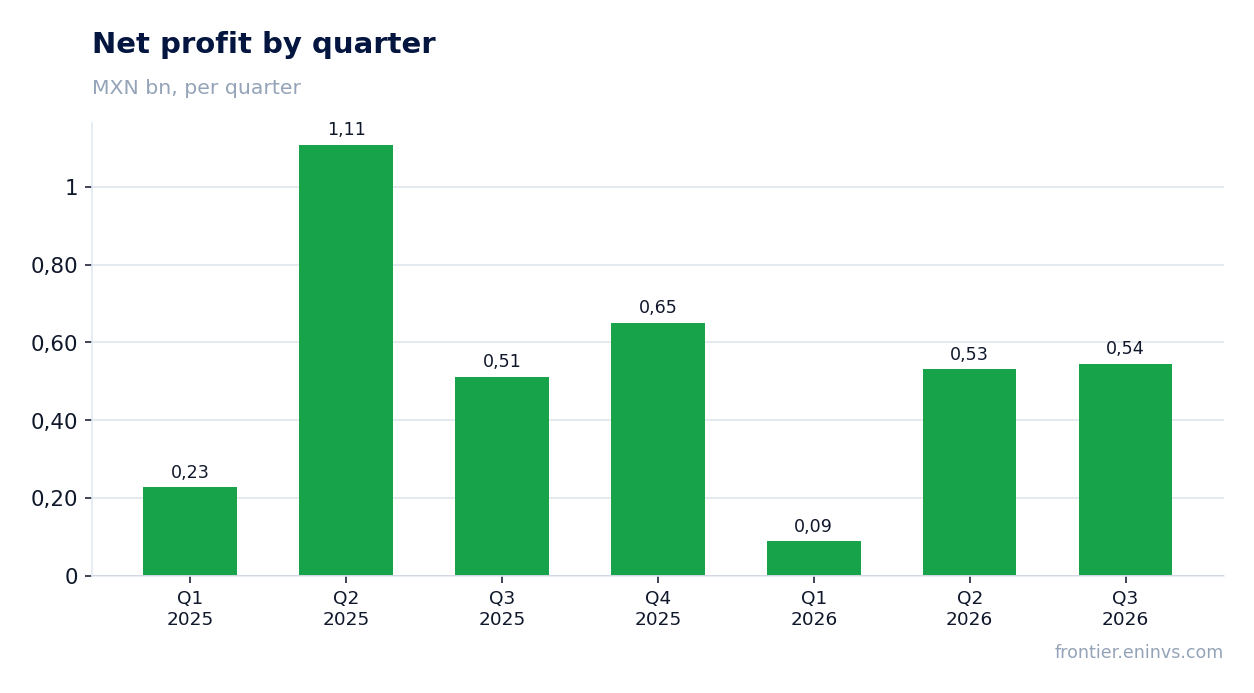
Net profit added only 6.4% because interest and depreciation absorbed the EBITDA gain
Net profit for the third quarter of 2026 was 544.8 mn MXN against 512.0 mn a year earlier, growth of 6.4%. The gap with EBITDA dynamics is huge: operating profit rose to 2,135.4 mn from 1,778.0 mn, or 20.1%, and only a small part reached net profit.
The reason lies below operating profit. Interest on debt and depreciation are growing faster than the operating result, and the facts give no breakdown of which contributed more. The net margin rose only to 2.5% from 2.4% – a move within the margin of error.
For a shareholder this means the improvement in operating efficiency is not yet translating into multiple growth in earnings per share. While debt is serviced at a high cost, each percentage point of EBITDA margin yields less and less net profit.
Operating cash flow for the quarter was 13,529.8 mn MXN – many times over EBITDA
Operating cash flow for the third quarter of 2026 was 13,529.8 mn MXN, three times EBITDA for the same quarter. Such a gap is atypical and points to working-capital release or a seasonal inflow rather than operating excess profit. The facts do not disclose the cause.
For comparison: in the second quarter the flow was only 452.5 mn, in the first 2,287.5 mn. The sharp jump in the third quarter is one-off in nature, and an annual forecast cannot be built on it. Over the last twelve months operating flow was 26,235.5 mn MXN – a more stable figure.
The facts contain no capital expenditure data for the third quarter, so free cash flow cannot be correctly calculated. But with quarterly EBITDA of 4.2 bn and moderate leverage, the company has the means both to service debt and to pay dividends.
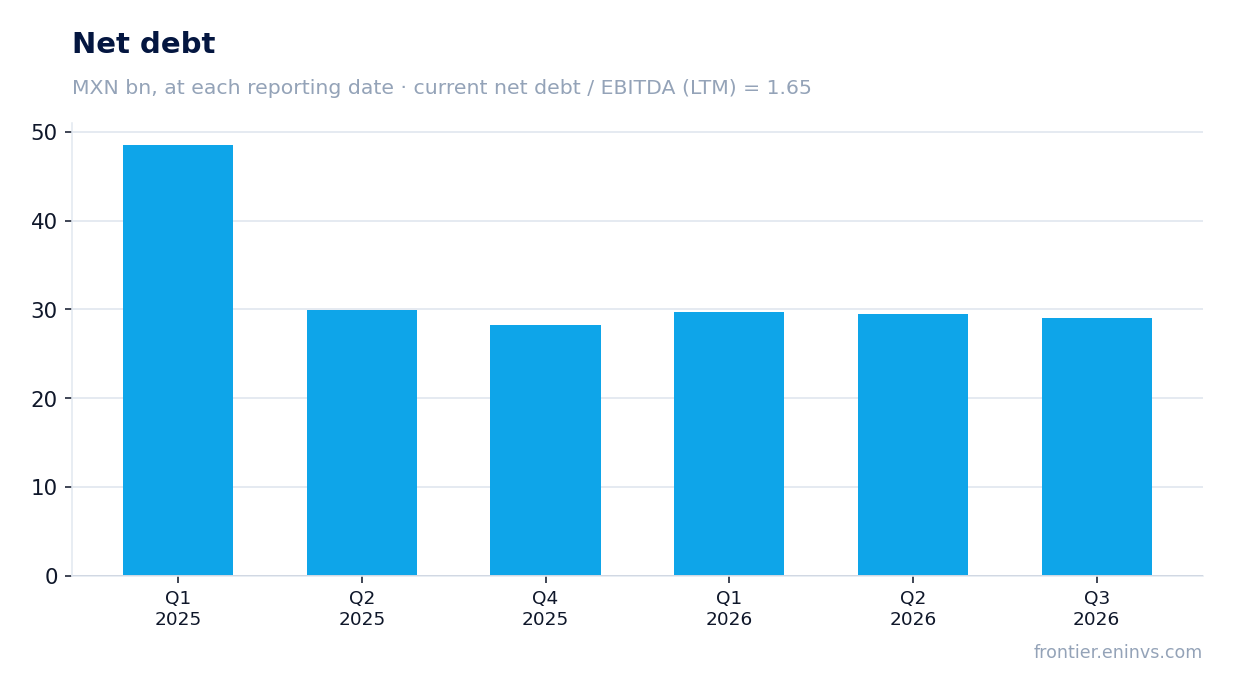
Net debt of 29.0 bn MXN at 1.65 times EBITDA – moderate leverage
Net debt at 30 September 2026 was 29,027.4 mn MXN, or 29.0 bn. The ratio of net debt to trailing-twelve-month EBITDA is 1.65, which looks comfortable for a restaurant business with leases and seasonality. More than half of annual EBITDA would go to debt service only at very high rates, and the facts contain no such data.
Debt dynamics are moderate: from 30 June 2026 net debt fell from 29.5 bn to 29.0 bn, and over the year from 30.0 bn on 30 June 2025 to 29.0 bn. A decline of 0.9 bn over the year against EBITDA of 17.6 bn is small but steady.
The level of 1.65 creates no risk for dividends and does not constrain investment. The direction of change in the ratio is not disclosed in the facts, so one cannot speak of leverage rising or falling – only of its current level.
Dividend yield of 1.9% rests on profit rather than one-off items
Dividend yield over the last twelve months is 1.9% on the current price. The payout rests on net profit: over the last twelve months it was 1,815.9 mn MXN, and the dividend is covered by it. The facts list no one-off items that would distort the base.
Our estimate of the dividend for the current year proceeds from the same profit and established payout practice. If profit stays near 1.8 bn and the payout ratio is unchanged, the dividend will remain close to last year's level. The key risk to the payout is not profit but rising interest expense, which eats it faster than EBITDA grows.
A yield of 1.9% is modest against the risk-free rate, but for a company with EBITDA growth of a third and a multiple below its history it looks fair. The payout could be reduced by a fall in net profit due to interest or by higher capital expenditure, data on which for the quarter is absent from the facts.
EV/EBITDA of 4.0 is below its own three-year average of 4.2 – the stock is cheaper than its history
On the trailing-twelve-month EV/EBITDA multiple the stock trades at 4.0 against its own three-year average of 4.2 – 6% below. This is the only valid comparison: we do not compare it with a sector or peers, as no such data is in the facts. The trailing P/E is 23.0, which looks high for a company with a 2.5% net margin but reflects the low profit base.
The gap between low EV/EBITDA and high P/E is explained by debt and interest: EV includes debt, while profit after interest is small. That makes EV/EBITDA more informative for valuing the business here. On the portal's model the upside to fair value is +95%, and this is our own estimate, not a market consensus.
The stock is held in live model strategies on the portal, including MX FVC (quality), but that is a membership fact, not an argument for the verdict. Re-rating requires either sustained revenue growth or confirmation of the margin in the next quarter.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 41.7 bn MXN |
| P/E (LTM) | 23.0 |
| EV/EBITDA (LTM) | 4.0 |
| P/B | 4.77 |
| Net debt / EBITDA (LTM) | 1.65 |
| Operating cash flow (LTM) | 26.2 bn |
| ROE | 24.6% |
| Dividend yield (12m) | 1.9% |
| EV/EBITDA, 3-year average | 4.2 |
Bottom line
The quarter's strength was margin: EBITDA rose 33.5% on revenue growth of 1.7%, and the EBITDA margin climbed to 19.6% from 14.9%. The weakness was the conversion of that growth into profit: net profit added only 6.4% because interest and depreciation took most of the gain. Quarterly cash flow of 13,529.8 mn MXN looks one-off and should not be treated as a new norm. Leverage is moderate at 1.65 net debt to EBITDA, and the EV/EBITDA multiple of 4.0 is below its own three-year average of 4.2. At the current price the share looks attractive, but the verdict rests on margin durability and on whether revenue accelerates in the next report.
Open the company's financial profile ALSEA →
See also: market overview · valuation map · stock screeners