Revenue accelerated to +7.6%, but EBITDA fell: growth was paid for with margin
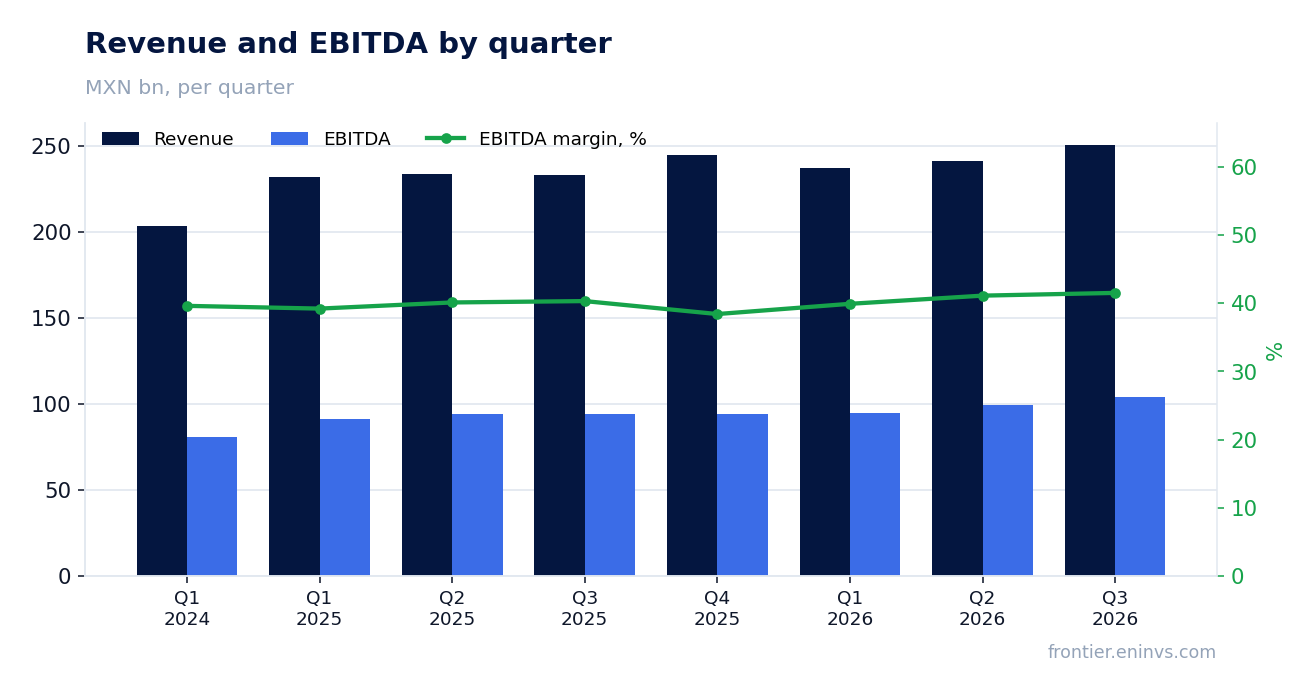
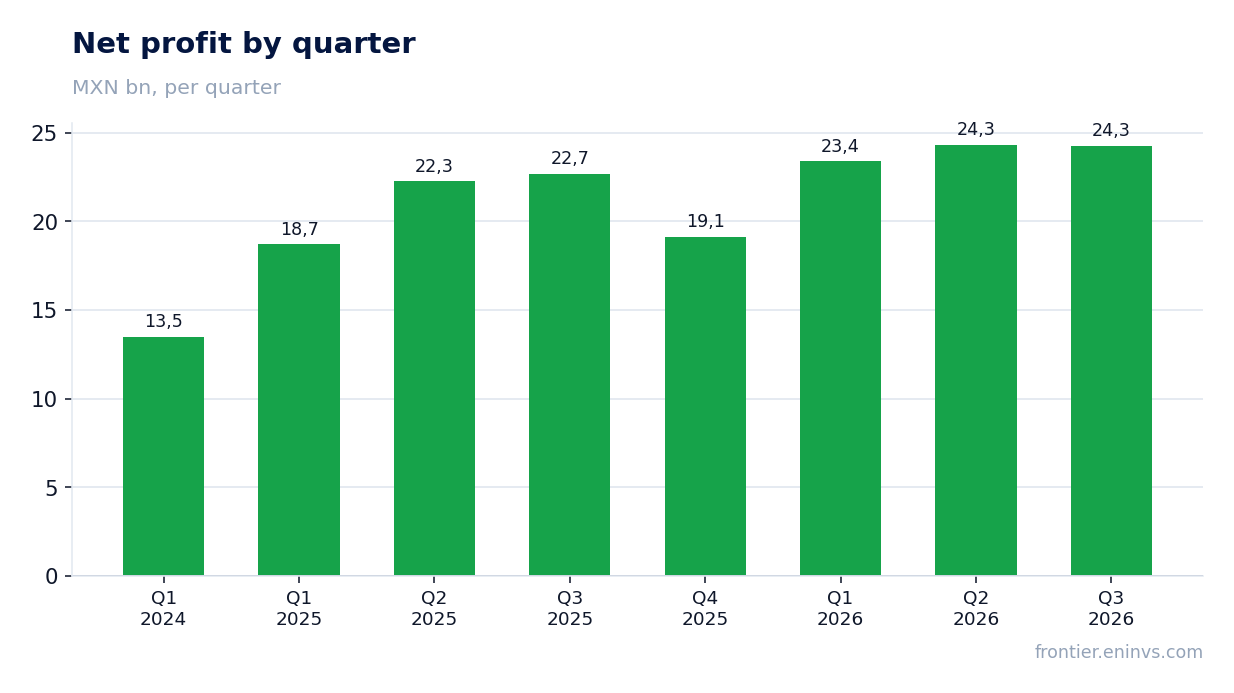
MX_AMX's Q3 2026 results showed revenue of MXN 250.6 bn, up 7.6% year on year – faster than the 3.1% growth in Q2. EBITDA, however, fell 2.6% to MXN 91.4 bn and the margin compressed from 40.3% to 36.5%; net profit rose 7.0% to MXN 24.3 bn. With P/E LTM at 16.3 and the portal model pointing to +12% upside, the share looks rather attractive, but only if the margin decline proves one-off rather than a new level.
Key takeaways
— Revenue accelerated to +7.6% year on year – twice the +3.1% of the prior quarter
— EBITDA fell 2.6% while revenue rose 7.6%: the margin dropped from 40.3% to 36.5%
— Net profit rose 7.0% to MXN 24.3 bn, with the margin held at 9.7%
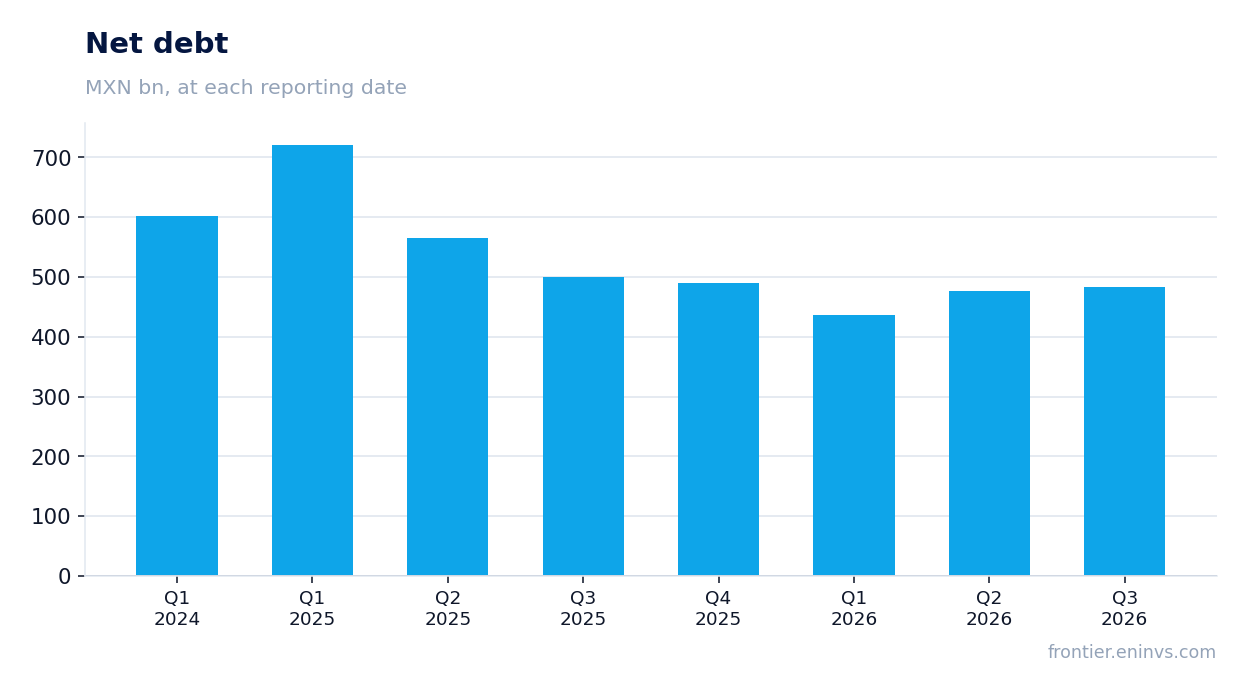
— Net debt fell over the year from MXN 500.4 bn to 483.9 bn, but rose MXN 7.0 bn in the quarter
— P/E LTM of 16.3 against ROE of 21.5% – the valuation does not look stretched
— The 2.4% dividend yield is modest, and the payout depends on retaining profit
— The portal model implies +12% upside to fair value
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 233 | 251 | +7.6% |
| EBITDA | 93.8 | 91.4 | -2.6% |
| Operating profit | 50.1 | 59.0 | +17.8% |
| Net profit | 22.7 | 24.3 | +7.0% |
| EBITDA margin | 40.3% | 36.5% | -3.8 pp |
| Net margin | 9.7% | 9.7% | +0.0 pp |
Revenue accelerated to +7.6% year on year – twice the +3.1% of the prior quarter
In Q3 2026 revenue reached MXN 250.6 bn, 7.6% more than a year earlier. This is a marked acceleration from Q2's 3.1% growth and Q1's +2.1%. The company has been gaining momentum for three consecutive quarters.
The acceleration matters because it dispels concerns about revenue stagnation earlier in the year. However, the growth rate has not yet recovered to a level that would offset the decline in profitability.
EBITDA fell 2.6% while revenue rose 7.6%: the margin dropped from 40.3% to 36.5%
Q3 2026 EBITDA came in at MXN 91.4 bn, 2.6% lower than a year earlier. With revenue up 7.6%, this means costs grew faster than income. The EBITDA margin fell from 40.3% to 36.5%.
The 3.8 percentage point margin compression is the main negative of the report. Operating profit still rose to MXN 59.0 bn, so the pressure on EBITDA did not fully translate into the operating result, but the gap between revenue and EBITDA is evident.
The facts do not disclose the cause of the margin decline. It could be a one-off factor or the start of a new cost level; for an investor, the key question is what exactly eroded profitability.
Net profit rose 7.0% to MXN 24.3 bn, with the margin held at 9.7%
Q3 2026 net profit was MXN 24.3 bn, up 7.0% year on year. The net margin held at 9.7%, the same as a year earlier, despite the fall in the EBITDA margin.
The resilience of the net margin while EBITDA compressed means that below the operating line profit was supported by other factors – possibly lower interest expenses or one-off items. Without the report's detail, the source of support is not established.
Over the trailing twelve months net profit was MXN 82.8 bn. This level forms the base for dividends and valuation.
Net debt fell over the year from MXN 500.4 bn to 483.9 bn, but rose MXN 7.0 bn in the quarter
Net debt at 30 September 2026 was MXN 483.9 bn. Over the quarter it rose from MXN 476.9 bn at 30 June, an increase of MXN 7.0 bn. Over the year debt declined: at 30 September 2025 it stood at MXN 500.4 bn, a reduction of MXN 16.5 bn.
The annual decline in debt alongside profit growth is a positive signal, but the quarterly increase shows debt is not falling monotonically. The debt-to-EBITDA ratio is not given in the facts, so leverage can only be judged by the absolute level.
Operating cash flow was MXN 24.9 bn in Q1 2026 and MXN 85.7 bn in Q4 2025. These data are incomplete for a full-year picture but confirm the ability to generate cash.
P/E LTM of 16.3 against ROE of 21.5% – the valuation does not look stretched
With a market capitalisation of MXN 1,348.9 bn and trailing twelve-month profit of MXN 82.8 bn, the P/E LTM is 16.3. Return on equity is 21.5%, which looks balanced for such a valuation.
The three-year average EV/EBITDA is 4.23. The current EV/EBITDA is not given in the facts, so a comparison with history cannot be made. But a P/E of 16.3 with ROE of 21.5% does not indicate overvaluation.
The portal model estimates upside to fair value at +12%. This is the portal's own estimate, not a market consensus.
The 2.4% dividend yield is modest, and the payout depends on retaining profit
The trailing twelve-month dividend yield is 2.4%. With trailing twelve-month net profit of MXN 82.8 bn and a market capitalisation of MXN 1,348.9 bn, payments over the year amounted to about MXN 32 bn, or roughly 39% of profit.
Our estimate for the current year's dividend assumes a payout ratio of about 39% and profit at the LTM level. That implies payments of about MXN 32 bn, which at the current price corresponds to a yield of about 2.4%. The estimate hinges on profit staying at MXN 82.8 bn and on the company not needing more funds for investment.
A 2.4% yield is modest and unlikely to be the main argument for buying. The payout could be reduced by a fall in profit or higher capital expenditure: capex in Q4 2025 was MXN 45.9 bn.
The portal model implies +12% upside to fair value
On the portal's model, which compares EBITDA growth with a target multiple and market capitalisation, the upside to fair value is +12%. This is our own estimate, not a market consensus or a target price.
The upside is moderate and depends on whether the EBITDA margin recovers. If the margin compression proves persistent, the model will need a downward revision.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 349 bn MXN |
| P/E (LTM) | 16.3 |
| P/B | 3.73 |
| ROE | 21.5% |
| Dividend yield (12m) | 2.4% |
Bottom line
The report's strength is the acceleration of revenue to +7.6% and the net margin held at 9.7%. The weakness is the 2.6% fall in EBITDA and the 3.8 pp margin compression, the cause of which is not disclosed. Net debt declined over the year but rose over the quarter. A P/E of 16.3 with ROE of 21.5% and +12% upside on the portal model support a rather attractive view, but it rests on the assumption that the margin recovers. Verdict – rather attractive.
Open the company's financial profile AMX →
See also: market overview · valuation map · stock screeners