ASUR: revenue fell 60.3% but profit rose — one-offs and newly consolidated assets did the work
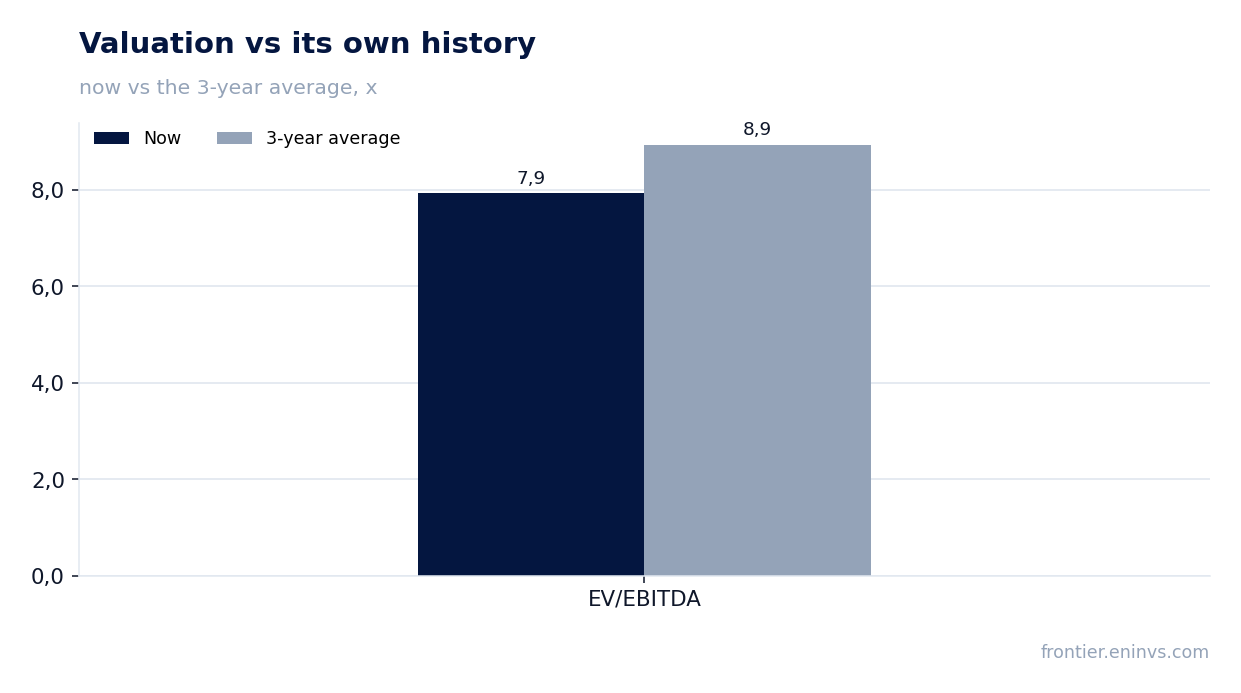
On October 22 ASUR reported third-quarter 2026 results. Revenue came in at MXN 10,420.5 million, down 60.3% year on year, while EBITDA reached MXN 4,719.3 million (+27.7%) and net profit MXN 2,307.9 million (+4.4%). The revenue decline reflects an exceptionally high construction-services base a year earlier, while profit growth was driven by the consolidation of Brazilian and U.S. assets and a one-off gain on FX forwards. At an EV/EBITDA of 7.9 versus its own three-year average of 8.9 and a dividend yield of 5.3%, the share looks rather attractive, though weak Mexican traffic and leverage call for caution.
Key takeaways
— Revenue fell 60.3% on a high construction-services base; excluding construction, the decline was only 12.6%
— EBITDA rose 27.7% on consolidation of Brazilian and U.S. assets, but the margin compressed to 45.3%
— Net profit was supported by a one-off MXN 719.2 million gain on FX forwards
— Debt rose to MXN 69,970.0 million, with net debt to LTM EBITDA at 2.6x
— The 5.3% dividend yield is backed by announced extraordinary payouts of MXN 10.00 per share
— EV/EBITDA of 7.9 is below its own three-year average of 8.9, pointing to undervaluation
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 26.3 | 10.4 | -60.3% |
| EBITDA | 3.70 | 4.72 | +27.7% |
| Operating profit | 3.69 | 3.89 | +5.3% |
| Net profit | 2.21 | 2.31 | +4.4% |
| Operating cash flow | 4.52 | — | — |
| Capex | 1.87 | — | — |
| EBITDA margin | 14.1% | 45.3% | +31.2 pp |
| Net margin | 8.4% | 22.1% | +13.7 pp |
Revenue fell 60.3% on a high construction-services base; excluding construction, the decline was only 12.6%
Third-quarter 2026 revenue came in at MXN 10,420.5 million, down 60.3% from the third quarter of 2025. The sharp decline reflects an exceptionally high base a year earlier, when construction-services revenue was unusually large, while in the current quarter it amounted to MXN 2,591.1 million. Excluding construction services, revenue fell 12.6% to MXN 7,829.4 million.
The main drag came from Mexico, where revenue excluding construction dropped 6.8% on a 4.6% decline in passenger traffic. International traffic in Mexico fell 11.8%, partly offset by a 1.6% increase in domestic traffic. Puerto Rico revenue declined 4.1%, Colombia grew 22.0%, and the newly acquired assets in Brazil and the U.S. added MXN 841.2 million and MXN 456.4 million respectively.
The deceleration from 9.9% growth in the second quarter of 2026 reflects both the base effect and a genuine weakening in the Mexican business. The consolidation of CPC Aeroportos from September 1, 2026, contributed MXN 841.2 million in revenue for one month, partly offsetting the organic decline.
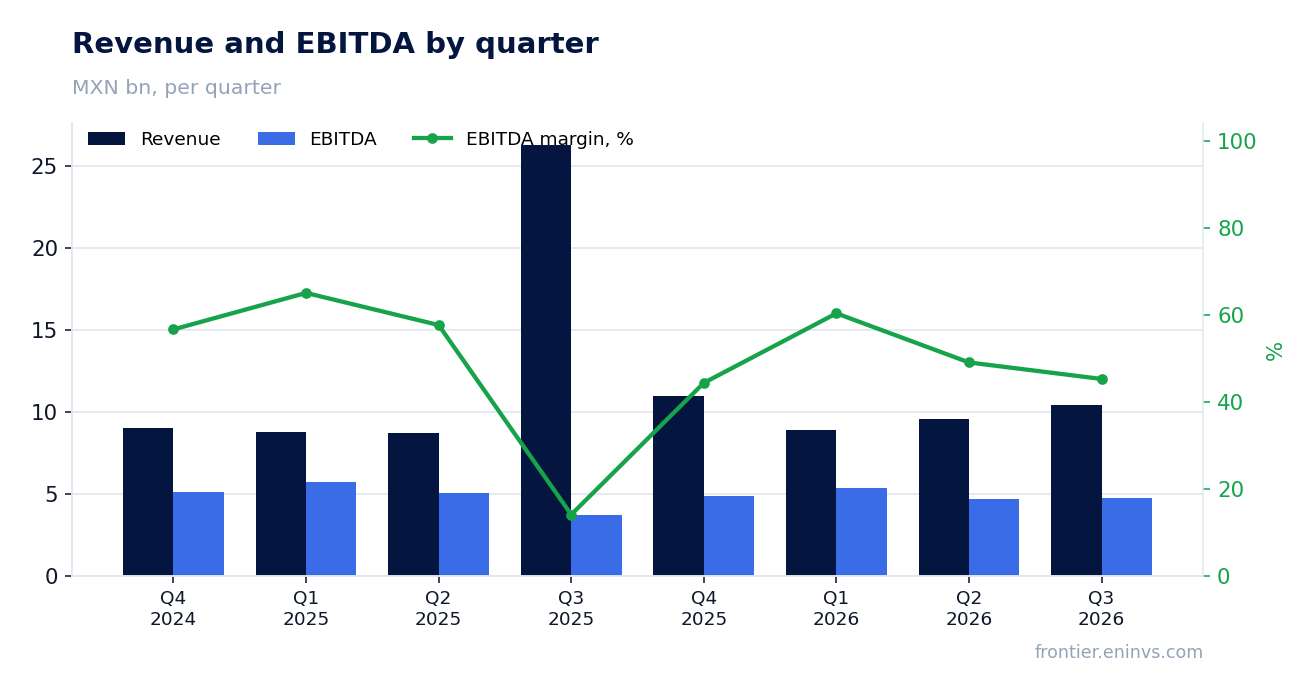
EBITDA rose 27.7% on consolidation of Brazilian and U.S. assets, but the margin compressed to 45.3%
EBITDA in the third quarter of 2026 rose 27.7% to MXN 4,719.3 million. However, the EBITDA margin declined to 45.3% from 52.9% a year earlier. The adjusted EBITDA margin, excluding the IFRIC 12 effect, was 60.3% versus 66.7% in the third quarter of 2025.
EBITDA growth was driven by new assets: Brazil & Others contributed MXN 313.2 million, U.S. operations MXN 49.0 million. Puerto Rico increased EBITDA by 7.1% to MXN 602.4 million, Colombia by 1.6% to MXN 590.0 million. These gains were partly offset by a 9.5% decline in Mexico EBITDA to MXN 3,164.7 million.
The margin compression reflects a shift in revenue mix: the share of low-margin construction services increased, and the consolidation of Brazilian assets with lower profitability also weighed. In addition, operating expenses excluding construction rose 20.9%, outpacing the 12.6% growth in revenue excluding construction.
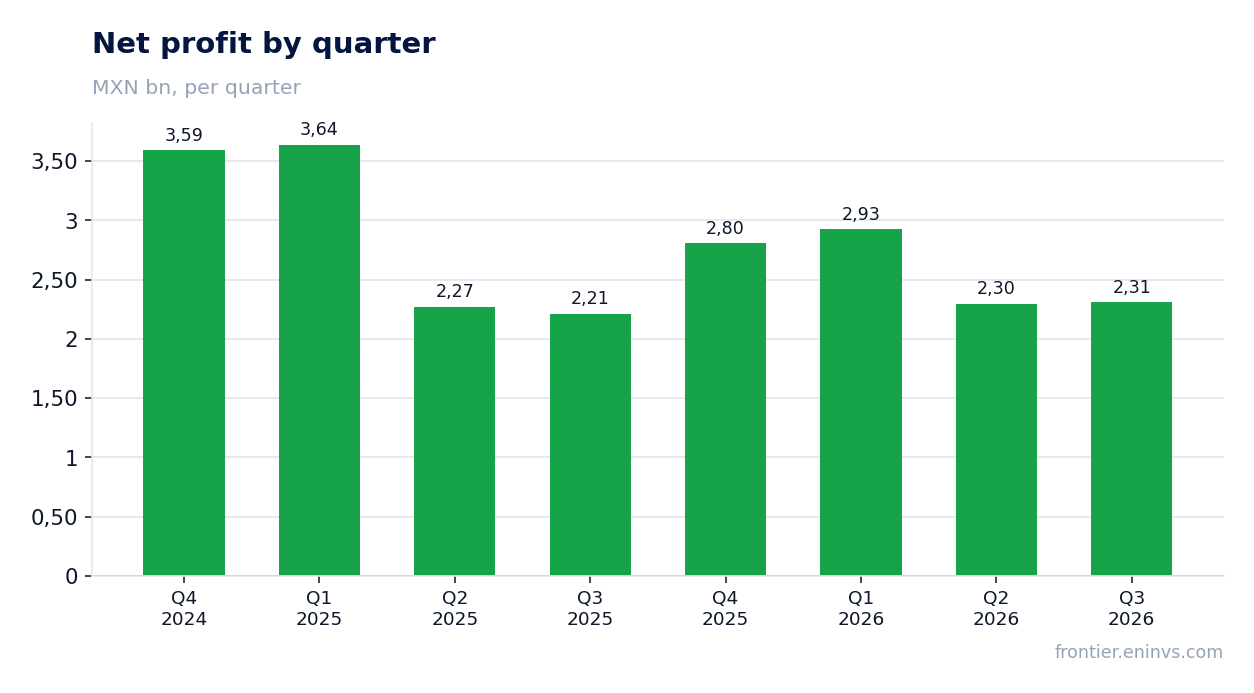
Net profit was supported by a one-off MXN 719.2 million gain on FX forwards
Net profit in the third quarter of 2026 was MXN 2,307.9 million, up 4.4% year on year. However, this growth would not have been possible without a one-off gain of MXN 719.2 million on three FX forward contracts entered into for hedging purposes. Excluding this gain, profit would have declined.
Interest expense rose 95.6% to MXN 871.7 million due to two loans raised in Mexico in December 2025 and August 2026, as well as lease liabilities in the U.S. and debt from Brazilian assets. Interest income fell 32.6% to MXN 237.3 million. Foreign exchange losses increased 112.1% to MXN 803.5 million.
Operating profit rose 5.3% to MXN 3,889.8 million, but the operating margin declined to 37.3% from 42.2%. The adjusted operating margin was 49.7% versus 53.1% a year earlier. The margin decline is explained by the change in the concession amortization method in Colombia introduced in the third quarter of 2025.
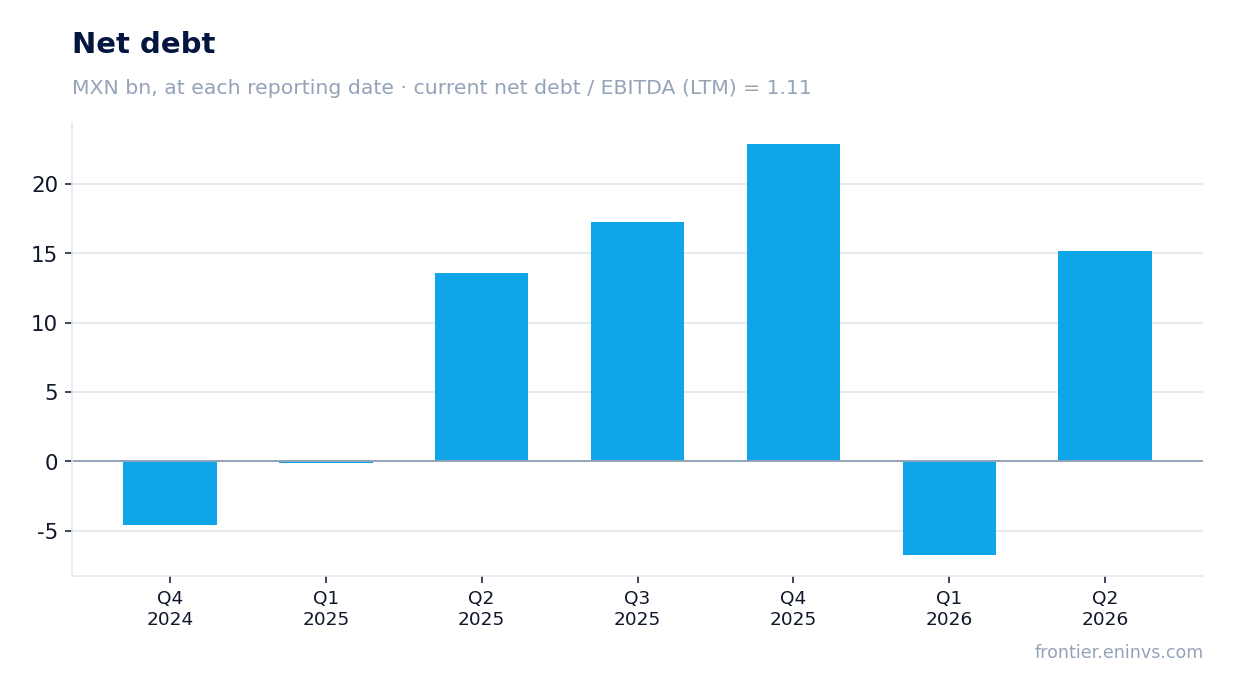
Debt rose to MXN 69,970.0 million, with net debt to LTM EBITDA at 2.6x
Total debt at the end of the third quarter of 2026 was MXN 69,969.9 million, up 154.6% from MXN 27,486.6 million at the end of 2025. The increase was driven by the addition of MXN 21,009.2 million in debt from Brazilian assets and a MXN 22,225.1 million bridge loan raised in Mexico on August 14, 2026. Net debt reached MXN 49,878.1 million.
The net debt to LTM EBITDA ratio stands at 2.6x. For comparison, at the end of the third quarter of 2025 this ratio was 0.2x. The interest coverage ratio declined to 5.2x from 12.8x. Cash and cash equivalents totaled MXN 20,091.8 million.
On October 8, 2026, ASUR placed senior notes for USD 900 million at 6.711% maturing in 2031 and another USD 900 million at 7.491% maturing in 2036. The proceeds were used to fully repay the bridge loans related to the acquisitions of ASUR US Airports and CPC Aeroportos, as well as to partially prepay the BBVA Mexico loan.
The 5.3% dividend yield is backed by announced extraordinary payouts of MXN 10.00 per share
The dividend yield over the last 12 months is 5.3%. On August 20, 2026, the shareholders' meeting approved the payment of two extraordinary cash dividends from the share buyback reserve of MXN 10.00 per share each, payable on November 30, 2026, and December 23, 2026. Thus, a total of MXN 20.00 per share may be paid for 2026.
Our estimate for the 2026 dividend is based on the announced payments and the current dividend policy. The payout depends on profit and cash flow, which in turn are affected by one-off items such as the gain on FX forwards and exchange rate differences. A decline in profit could lead to a smaller dividend.
The 5.3% yield exceeds the key rate, making the share attractive for income-oriented investors. However, the sustainability of payments depends on the company's ability to generate free cash flow, which came under pressure in the third quarter due to capex rising to MXN 2,716.6 million.
EV/EBITDA of 7.9 is below its own three-year average of 8.9, pointing to undervaluation
The EV/EBITDA LTM multiple is 7.9, which is 11% below its own three-year average of 8.9. This indicates that the share is trading cheaper than its average over the past three years. The P/E LTM is 13.6. Market capitalization stands at MXN 140,568.0 million.
According to the portal's model, which compares EBITDA growth with the target multiple and market capitalization, the upside to fair value is estimated at +28%. This is our own estimate, not a market consensus.
However, the current undervaluation may be justified by risks related to the decline in Mexican passenger traffic and rising debt. The net debt to LTM EBITDA ratio of 2.6x limits financial flexibility, while rising interest expenses weigh on profit.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 141 bn MXN |
| P/E (LTM) | 13.6 |
| EV/EBITDA (LTM) | 7.9 |
| P/B | 3.03 |
| Net debt / EBITDA (LTM) | 1.11 |
| ROE | 21.9% |
| Dividend yield (12m) | 5.3% |
| EV/EBITDA, 3-year average | 8.9 |
Bottom line
ASUR's third-quarter 2026 report presents a mixed picture. On the one hand, revenue fell 60.3% due to the base effect, but excluding construction services the decline was only 12.6%. EBITDA rose 27.7% on consolidation of new assets, yet the margin compressed. Net profit increased 4.4%, but was supported by a one-off gain on FX forwards. Leverage rose, with net debt to LTM EBITDA at 2.6x. At an EV/EBITDA of 7.9 versus a three-year average of 8.9 and a dividend yield of 5.3%, the share looks rather attractive, but risks from declining traffic and one-off items call for caution.
Open the company's financial profile ASUR →
See also: market overview · valuation map · stock screeners