FEMSA: profit nearly tripled, but a 9.1% margin still sits below what the market pays for this growth
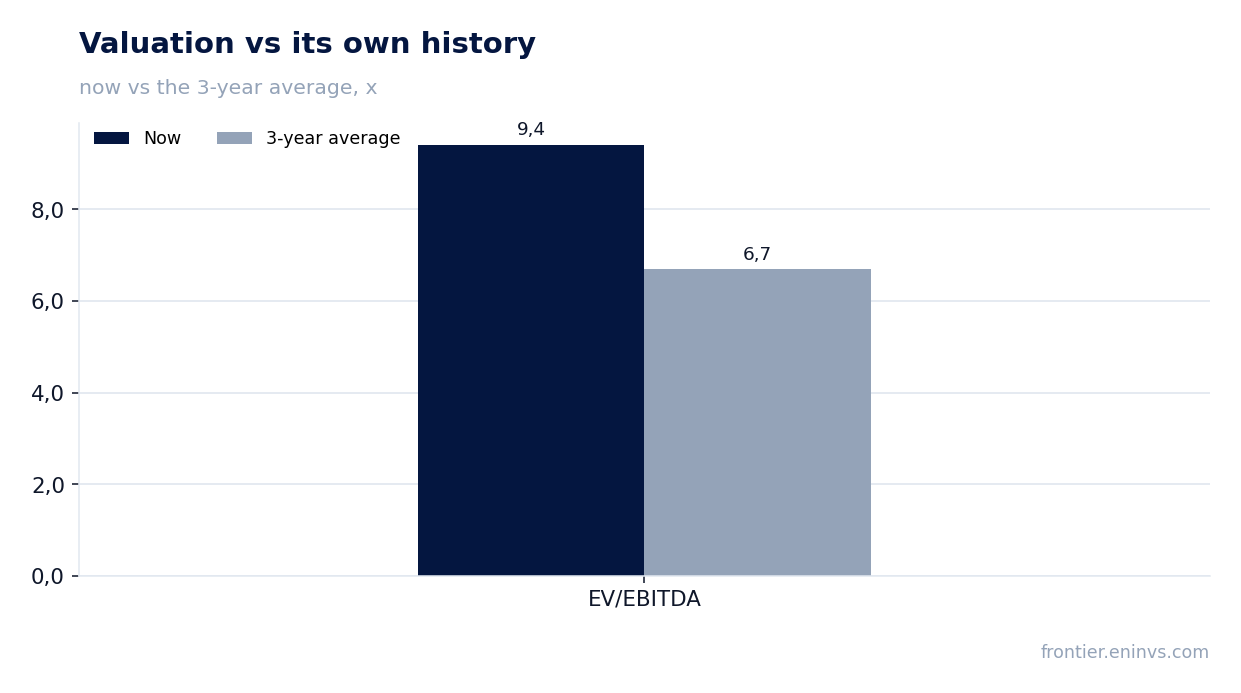
On 25 November FEMSA released its third-quarter 2026 results. Revenue rose 9.8% year on year to MXN 235.6 bn, EBITDA by 17.2% to MXN 21.6 bn and net profit by 182.0% to MXN 6.8 bn. The EBITDA margin improved to 9.1% from 8.6%, and the net margin to 2.9% from 1.1%. The share looks neutral: top-line growth is steady, but EV/EBITDA of 9.4 is 41% above its own three-year average of 6.7, and with a 5.7% dividend yield the portal's model implies only +3% upside.
Key takeaways
— Revenue has grown for nine straight quarters, but the pace barely changed: +9.8% versus +9.3% a quarter earlier
— EBITDA rose 17.2%, and the 9.1% margin added 0.5 pp – growth is outpacing revenue
— Net profit rose 182.0% to MXN 6.8 bn, but the base was low – MXN 2.4 bn a year earlier
— Net debt fell to MXN 28.1 bn from MXN 34.8 bn on 30 June, and net debt/EBITDA LTM stands at 0.31
— The 5.7% dividend yield rests on a payout backed by LTM profit of MXN 35.7 bn
— EV/EBITDA of 9.4 versus its own three-year average of 6.7 – the stock is 41% more expensive than its history
— The portal's model implies only +3% to fair value – growth is already in the price
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 215 | 236 | +9.8% |
| EBITDA | 18.4 | 21.6 | +17.2% |
| Operating profit | 18.1 | 19.9 | +9.9% |
| Net profit | 2.42 | 6.81 | +182.0% |
| EBITDA margin | 8.6% | 9.1% | +0.5 pp |
| Net margin | 1.1% | 2.9% | +1.8 pp |
Revenue has grown for nine straight quarters, but the pace barely changed: +9.8% versus +9.3% a quarter earlier
In the third quarter of 2026 revenue reached MXN 235.6 bn, 9.8% more than a year earlier. A quarter earlier growth was 9.3%, and in the first quarter 6.1%. The pace barely changed: the company is holding high single-digit momentum without jumps.
Growth comes off a low base: third-quarter 2025 revenue was MXN 214.6 bn. Over the trailing twelve months revenue was MXN 894.5 bn – nearly four times the quarterly level, confirming the steadiness of the revenue stream.
For a holder the pace matters less than its durability: growth has accelerated for three straight quarters from 6.1% to 9.3% and 9.8%, but the step between the last two is minimal. The next report will show whether this trajectory holds.
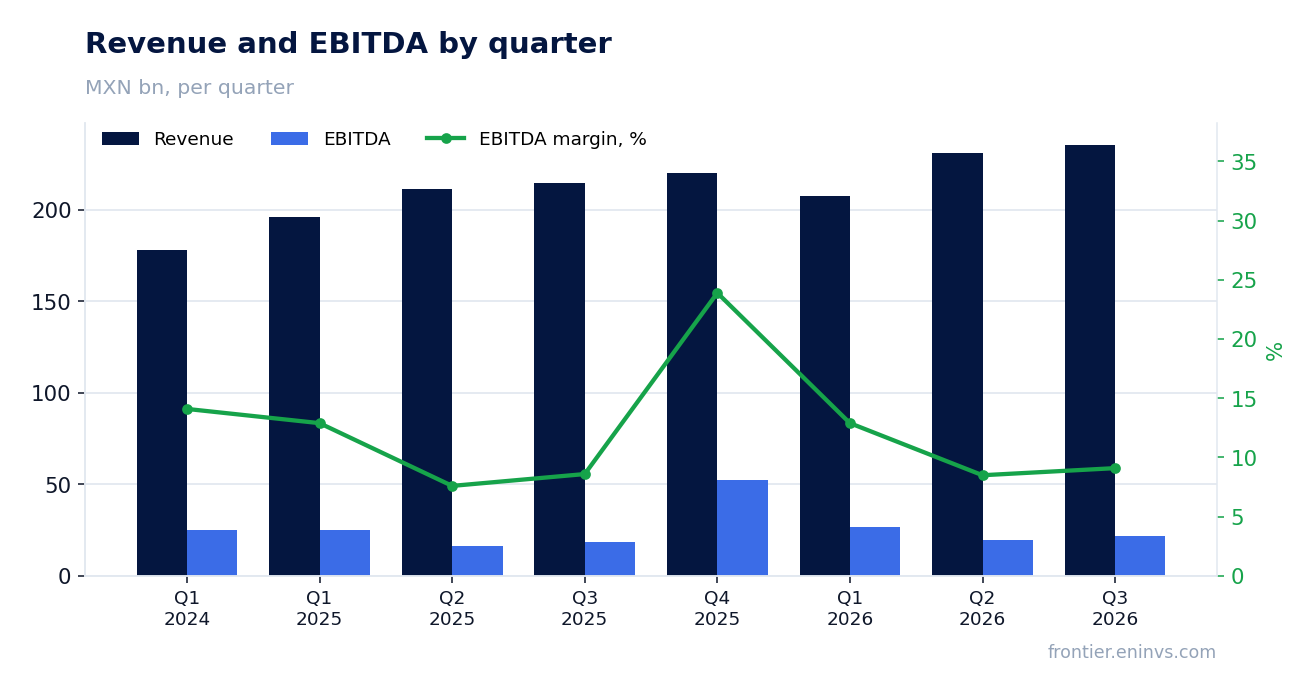
EBITDA rose 17.2%, and the 9.1% margin added 0.5 pp – growth is outpacing revenue
EBITDA in the third quarter of 2026 was MXN 21.6 bn, 17.2% more than a year earlier. That is faster than the 9.8% revenue growth, so the EBITDA margin rose to 9.1% from 8.6% a year earlier.
Operating profit was MXN 19.9 bn – it is growing more slowly than EBITDA, which suggests part of the improvement comes from lines below the operating line. The gap between EBITDA and operating profit – MXN 1.6 bn – is depreciation, and it did not rise proportionally with revenue.
A 9.1% margin is still low for a company with nearly MXN 900 bn of trailing revenue. The 0.5 pp improvement is a positive signal, but it does not yet change the profitability profile.
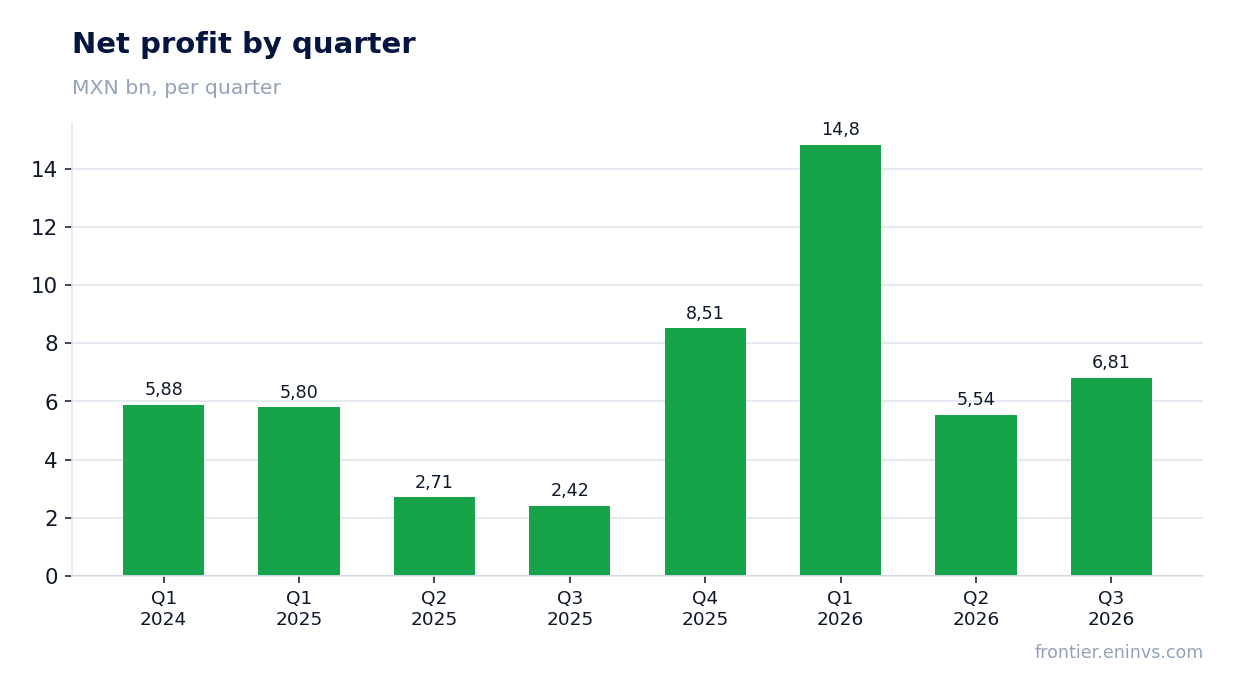
Net profit rose 182.0% to MXN 6.8 bn, but the base was low – MXN 2.4 bn a year earlier
Net profit in the third quarter of 2026 was MXN 6.8 bn versus MXN 2.4 bn a year earlier – growth of 182.0%. That percentage reflects a low base: third-quarter 2025 profit was the lowest in two years.
The net margin rose to 2.9% from 1.1%. With revenue of MXN 235.6 bn, each percentage point of margin is MXN 2.4 bn of profit, so the 1.8 pp improvement drove most of the absolute profit growth.
LTM profit is MXN 35.7 bn. That is the level the dividend rests on, and it is well above the quarterly figure, smoothing out one-off swings.
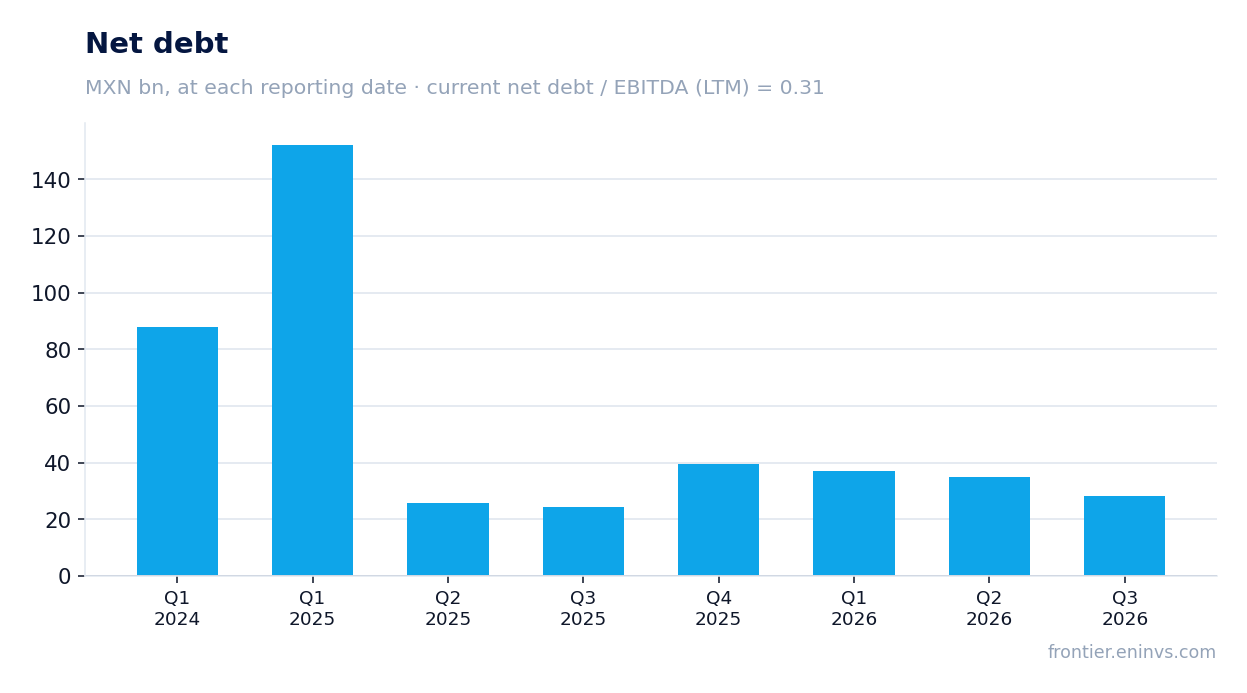
Net debt fell to MXN 28.1 bn from MXN 34.8 bn on 30 June, and net debt/EBITDA LTM stands at 0.31
Net debt on 30 September 2026 was MXN 28.1 bn versus MXN 34.8 bn on 30 June – a MXN 6.7 bn reduction over the quarter. A year earlier, on 30 September 2025, debt was MXN 24.5 bn, so over twelve months it rose by MXN 3.6 bn.
The ratio of net debt to LTM EBITDA is 0.31. That is a low level: the company services its debt without strain, and even if EBITDA halved the burden would remain comfortable.
The quarterly debt reduction alongside positive profit shows the company generates enough cash to service its obligations. Interest expense is not disclosed in the facts, but at this debt level it is not the main risk.
The 5.7% dividend yield rests on a payout backed by LTM profit of MXN 35.7 bn
The trailing twelve-month dividend yield is 5.7%. The payout rests on LTM profit of MXN 35.7 bn, more than five times the quarterly profit of MXN 6.8 bn.
Our estimate for the current year's dividend is based on LTM profit and the current yield: if the payout ratio holds, the payment will stay close to last year's level. The key factor is the payout-to-profit ratio, which the company does not disclose in the facts.
A 5.7% yield is comparable to the key rate but does not significantly exceed it. For a dividend stock this is a moderate level: attractive if profit is stable, but it leaves no cushion if the payout is cut.
EV/EBITDA of 9.4 versus its own three-year average of 6.7 – the stock is 41% more expensive than its history
EV/EBITDA LTM is 9.4 against its own three-year average of 6.7 – the stock trades 41% above its history. P/E LTM is 22.5, which with a 2.9% net margin reflects growth expectations rather than current returns.
Market capitalisation is MXN 803.6 bn. At EV/EBITDA of 9.4 and LTM EBITDA of MXN 89.6 bn, enterprise value is about MXN 842 bn, close to market cap plus net debt of MXN 28.1 bn.
A multiple above its historical level means the market has already priced in continued revenue and margin growth. If the growth pace slows, the valuation could compress toward the average.
The portal's model implies only +3% to fair value – growth is already in the price
On the portal's model, which compares EBITDA growth with the target multiple and market capitalisation, the upside to fair value is +3%. This is our own calculation, not a market consensus.
Such a small upside means the current price is close to the model's valuation. Further gains would require either stronger EBITDA growth, a lower multiple, or a larger dividend.
With EV/EBITDA at 9.4 against an average of 6.7, room for upward re-rating is limited. The main contributor to a holder's return will be the dividend, not capital appreciation.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 804 bn MXN |
| P/E (LTM) | 22.5 |
| EV/EBITDA (LTM) | 9.4 |
| P/B | 2.89 |
| Net debt / EBITDA (LTM) | 0.31 |
| ROE | 12.3% |
| Dividend yield (12m) | 5.7% |
| EV/EBITDA, 3-year average | 6.7 |
Bottom line
The quarter's strength was EBITDA growth of 17.2% and a margin of 9.1% – the company is growing faster than revenue. Net profit rose 182.0%, but from a low base of MXN 2.4 bn, and that pace should not be read as sustainable. Net debt fell to MXN 28.1 bn from MXN 34.8 bn over the quarter, with net debt/EBITDA LTM at 0.31, which is comfortable. The main question for a holder is valuation: EV/EBITDA of 9.4 against its own average of 6.7, while the portal's model implies only +3%. The 5.7% dividend yield remains the main argument, but it does not outweigh the rich valuation. Verdict – neutral.
Open the company's financial profile FEMSA →
See also: market overview · valuation map · stock screeners