MX_GAP: revenue accelerated to 21.8%, but profit lagged on margin
MX_GAP reported results for the third quarter of 2026, ended 30 September. Revenue reached 11,667.8 million MXN, up 21.8% year on year, EBITDA was 6,064.6 million MXN (+19.2%), and net profit was 2,914.1 million MXN (+8.1%). Revenue growth accelerated from 3.7% in the second quarter, but margin and profit lag the top line. At an EV/EBITDA of 11.0 versus its own three-year average of 12.8 the share looks cheaper than its history, and on the portal's model the upside to fair value is +7% – verdict: rather attractive.
Key takeaways
— Revenue grew 21.8% year on year, an acceleration from 3.7% in the second quarter
— EBITDA rose 19.2%, but the margin fell to 52.0% from 53.1% a year earlier
— Net profit grew only 8.1%, and the net margin dropped to 25.0% from 28.2%
— Operating cash flow for the quarter was 5,499.1 million MXN against capex of 4,218.5 million a year earlier
— Net debt fell to 43.8 billion MXN from 45.9 billion on 30 June, while over 12 months it rose from 42.5 billion
— Leverage at 1.91x EBITDA LTM is moderate, and EV/EBITDA of 11.0 is below its own three-year average of 12.8
— On the portal's model the share trades at a discount to fair value, with +7% upside
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 9.58 | 11.7 | +21.8% |
| EBITDA | 5.09 | 6.06 | +19.2% |
| Operating profit | 4.15 | 5.05 | +21.6% |
| Net profit | 2.70 | 2.91 | +8.1% |
| Operating cash flow | 4.26 | 5.50 | +29.0% |
| Capex | 4.22 | — | — |
| EBITDA margin | 53.1% | 52.0% | -1.1 pp |
| Net margin | 28.2% | 25.0% | -3.2 pp |
Revenue grew 21.8% year on year, an acceleration from 3.7% in the second quarter
In the third quarter of 2026 revenue reached 11,667.8 million MXN, up 21.8% from a year earlier. In the second quarter growth was a more modest 3.7%, so the dynamics accelerated noticeably. Quarter on quarter revenue also increased, from 11,289.7 million MXN in the second quarter to 11,667.8 million in the third.
The acceleration rests on a low base in the third quarter of 2025, when revenue was 9,576.6 million MXN. The sequential gain over the previous quarter was small, about 3.3%, so the annual jump reflects a recovery from a weak period a year earlier rather than a sharp surge in demand.
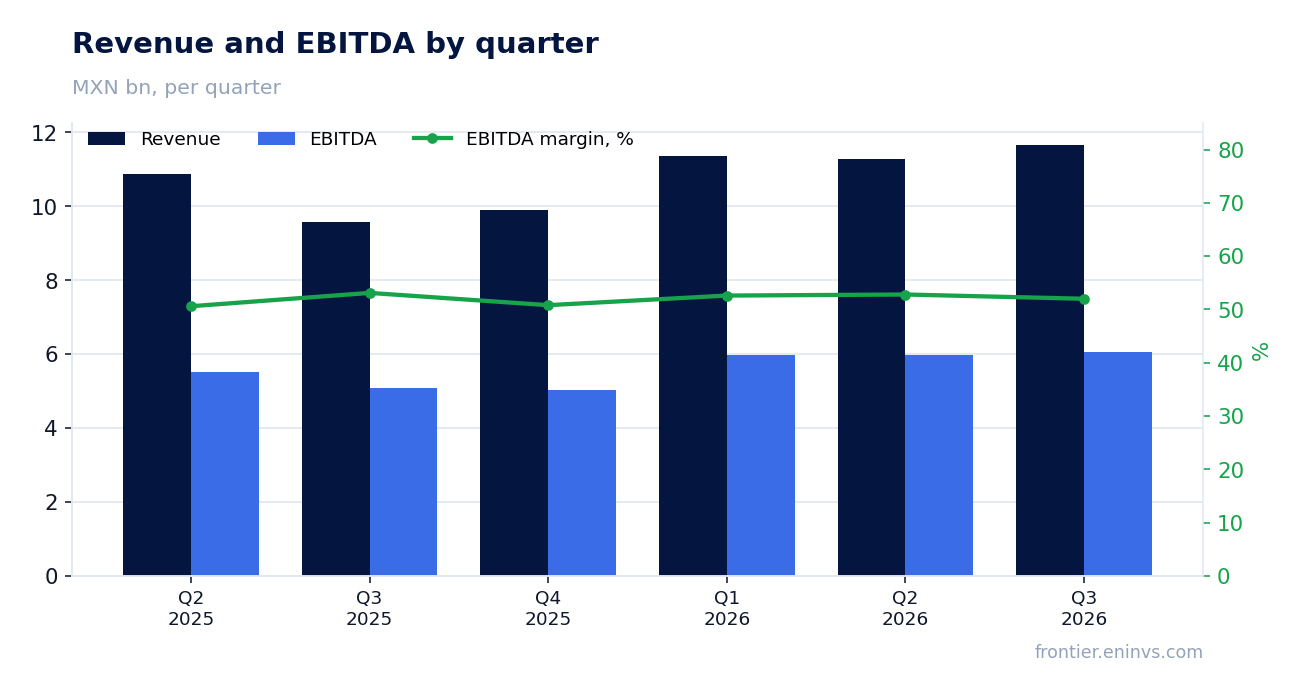
EBITDA rose 19.2%, but the margin fell to 52.0% from 53.1% a year earlier
EBITDA for the third quarter was 6,064.6 million MXN, up 19.2% from a year earlier. The growth slightly trails revenue, and this showed up in profitability: the EBITDA margin fell to 52.0% from 53.1% in the third quarter of 2025.
Operating profit was 5,047.7 million MXN, up 21.6% year on year. That is slightly faster than revenue but slower than one might expect given the top-line dynamics. The gap between revenue and EBITDA growth suggests part of the extra income went into costs rather than reaching operating profit.
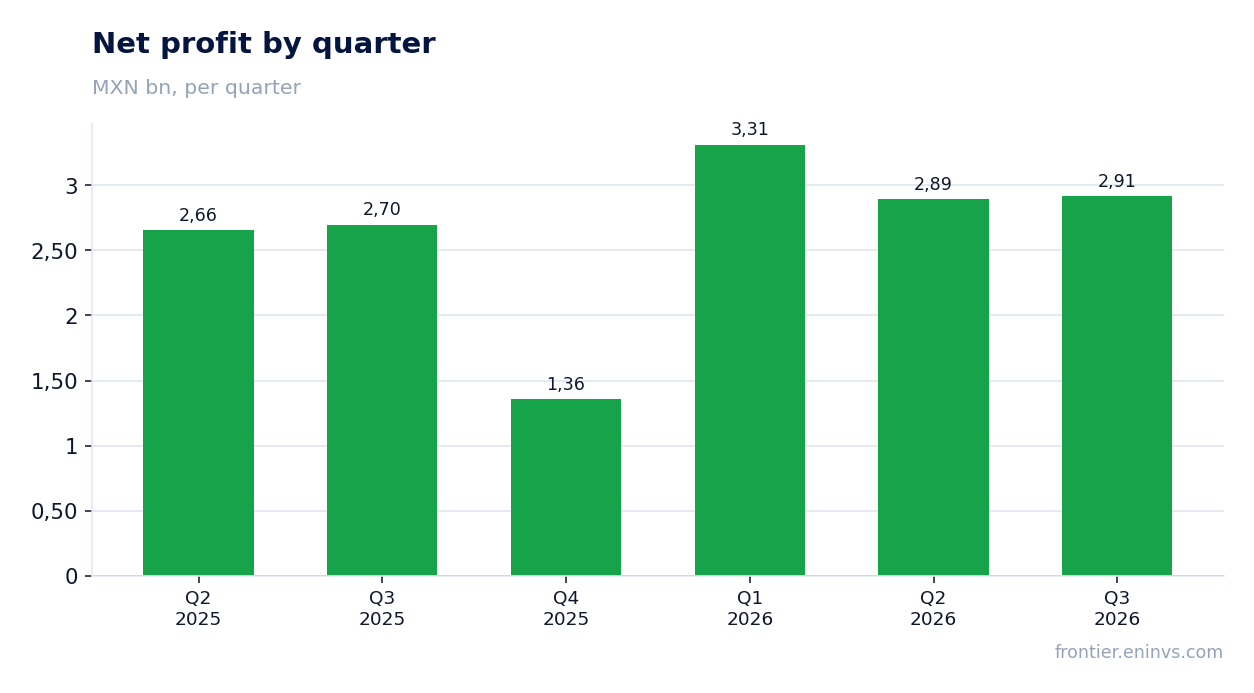
Net profit grew only 8.1%, and the net margin dropped to 25.0% from 28.2%
Net profit for the third quarter was 2,914.1 million MXN, up 8.1% year on year. That is considerably slower than revenue and EBITDA growth. The net margin fell to 25.0% from 28.2% a year earlier.
The gap between operating and net profit points to higher costs below the operating line – likely interest or other items. With revenue of 11,667.8 million MXN and operating profit of 5,047.7 million MXN, net profit of 2,914.1 million MXN means about 2.1 billion MXN was absorbed between operating and net profit.
Operating cash flow for the quarter was 5,499.1 million MXN against capex of 4,218.5 million a year earlier
Operating cash flow in the third quarter was 5,499.1 million MXN, above the second-quarter figure of 2,637.0 million and close to the first-quarter level of 7,571.8 million. Cash flow covers capital expenditure, which a year earlier was 4,218.5 million MXN.
Over the last twelve months operating cash flow reached 20,837.9 million MXN on revenue of 44,200.0 million MXN. That is a solid conversion – about 47% of revenue turns into operating cash flow. Capital expenditure for the third quarter of 2026 is not disclosed in the facts, but a year earlier it was significant.
Net debt fell to 43.8 billion MXN from 45.9 billion on 30 June, while over 12 months it rose from 42.5 billion
Net debt on 30 September 2026 was 43.8 billion MXN, down from 45.9 billion on 30 June. Over 12 months debt rose: from 42.5 billion on 31 December 2025 to 43.8 billion on 30 September 2026, an increase of 1.2 billion MXN.
The ratio of net debt to EBITDA over the last twelve months is 1.91. That is a moderate level, leaving room for manoeuvre. Interest costs likely absorb part of profit: with operating profit of 5,047.7 million MXN and net profit of 2,914.1 million MXN, the difference is substantial.
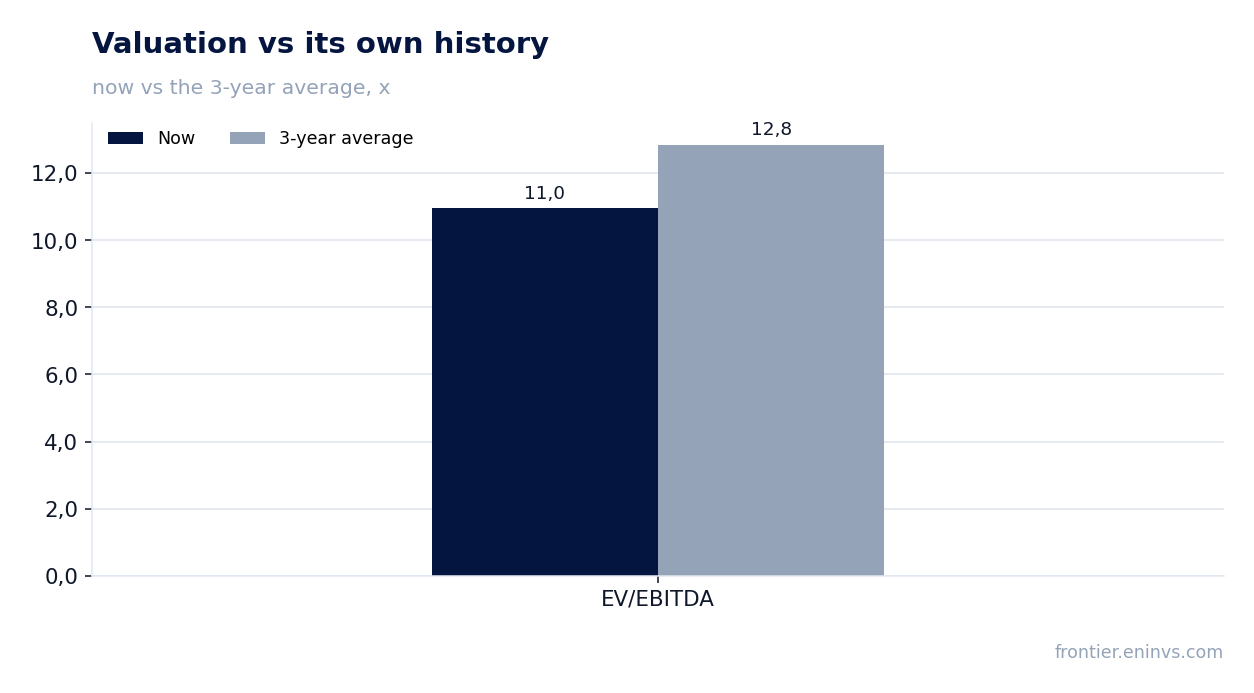
Leverage at 1.91x EBITDA LTM is moderate, and EV/EBITDA of 11.0 is below its own three-year average of 12.8
The EV/EBITDA multiple over the last twelve months is 11.0, 15% below its own three-year average of 12.8. The share trades cheaper than its history on this multiple. P/E LTM is 19.9, and market capitalisation is 208.5 billion MXN.
On the portal's model the fair value implies +7% upside to the current price. This is the portal's own estimate, not market consensus. The combination of moderate debt, stable cash flow and a discount to the historical multiple makes the valuation attractive.
On the portal's model the share trades at a discount to fair value, with +7% upside
Our valuation model, based on EBITDA growth and a target multiple, shows +7% upside to the current market price. That is a moderate but positive signal. The model incorporates current revenue and profit dynamics as well as the debt level.
Revenue growth has accelerated, cash flow remains strong, and leverage is moderate. The main risk to the valuation is a further decline in margin, which could slow profit growth and limit re-rating potential.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 208 bn MXN |
| P/E (LTM) | 19.9 |
| EV/EBITDA (LTM) | 11.0 |
| P/B | 9.28 |
| Net debt / EBITDA (LTM) | 1.91 |
| Operating cash flow (LTM) | 20.8 bn |
| ROE | 21.5% |
| EV/EBITDA, 3-year average | 12.8 |
Bottom line
The strong side of the report is the acceleration in revenue to 21.8% and solid operating cash flow of 5,499.1 million MXN. The weak side is the margin decline and slow net profit growth of 8.1%. Leverage is moderate, and the EV/EBITDA multiple of 11.0 is below its own three-year average of 12.8. On the portal's model the upside is +7%, which, combined with stable cash flow, makes the share rather attractive. The key question for a holder is whether the company can halt the margin decline and return profit to growth faster than revenue.
Open the company's financial profile GAP →
See also: market overview · valuation map · stock screeners