MX_INBURSA: quarterly profit fell by a quarter as net interest income stopped growing
In its Q3 2026 report, MX_INBURSA posted net profit of 5,226.4 million MXN and net interest income of 19,552.3 million MXN. Profit fell roughly 12% versus Q2, while year-on-year growth in net interest income decelerated: -1.0% in Q2 after +10.9% in Q1. With a P/E LTM of 8.7 and a return on equity of 7.3%, the share looks neutral: a 2.5% dividend yield and the portal model's +7% upside do not outweigh the weak profit trend.
Key takeaways
— Q3 2026 net profit was 5,226.4 million MXN, down 12% from Q2
— Net interest income fell to 19,552.3 million MXN in Q3, and year-on-year growth decelerated from +10.9% to -1.0%
— Trailing twelve-month profit of 30,931.2 million MXN against a market cap of 270,191.9 million MXN gives a P/E of 8.7
— A return on equity of 7.3% is below what the current valuation requires
— A 2.5% dividend yield is thinner than risk-free instruments and does not offset weak profit growth
— The portal model puts the share's upside at +7% to the current price
Attractiveness
Key figures, MXN bn
| Metric | — | Q3 2026 | Change |
|---|---|---|---|
| Net profit | — | 5.23 | — |
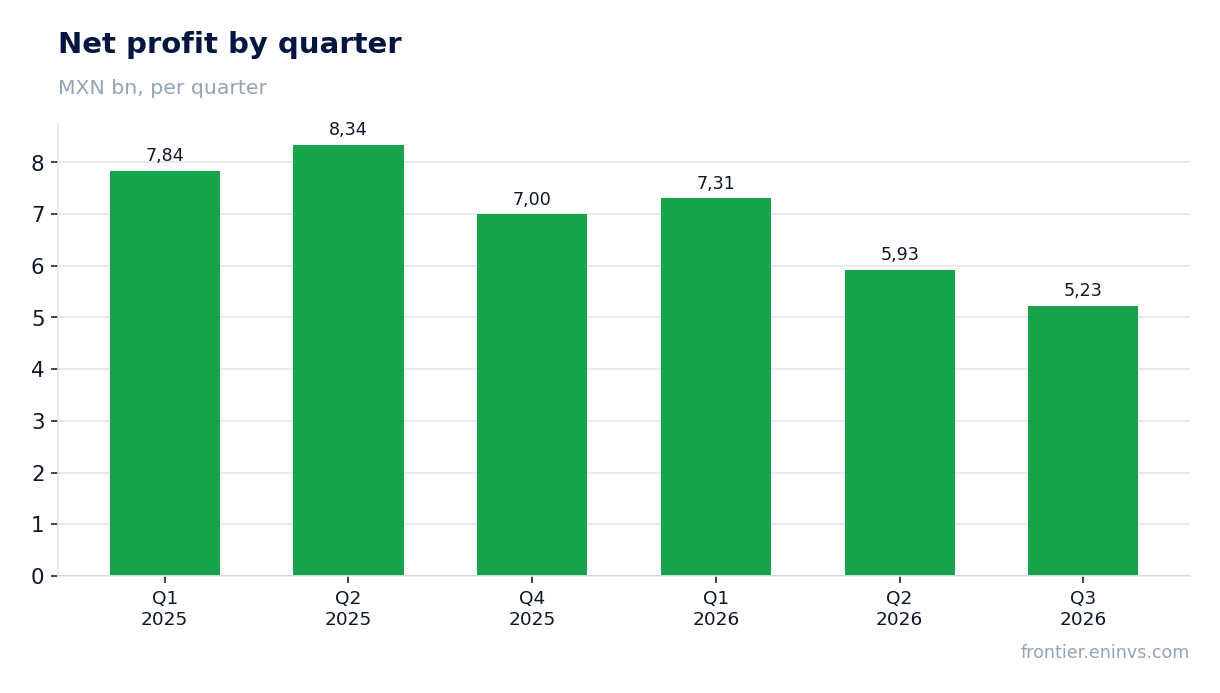
Q3 2026 net profit was 5,226.4 million MXN, down 12% from Q2
MX_INBURSA's net profit in Q3 2026 was 5,226.4 million MXN. It was 5,926.4 million MXN in Q2 and 7,306.5 million MXN in Q1. The decline has now run for three consecutive quarters: profit is down almost 28% from the Q1 peak.
Trailing twelve-month profit stands at 30,931.2 million MXN. That figure includes strong Q1 and Q2 2026 and even stronger quarters in 2025, so the current quarterly level is well below the annual average.
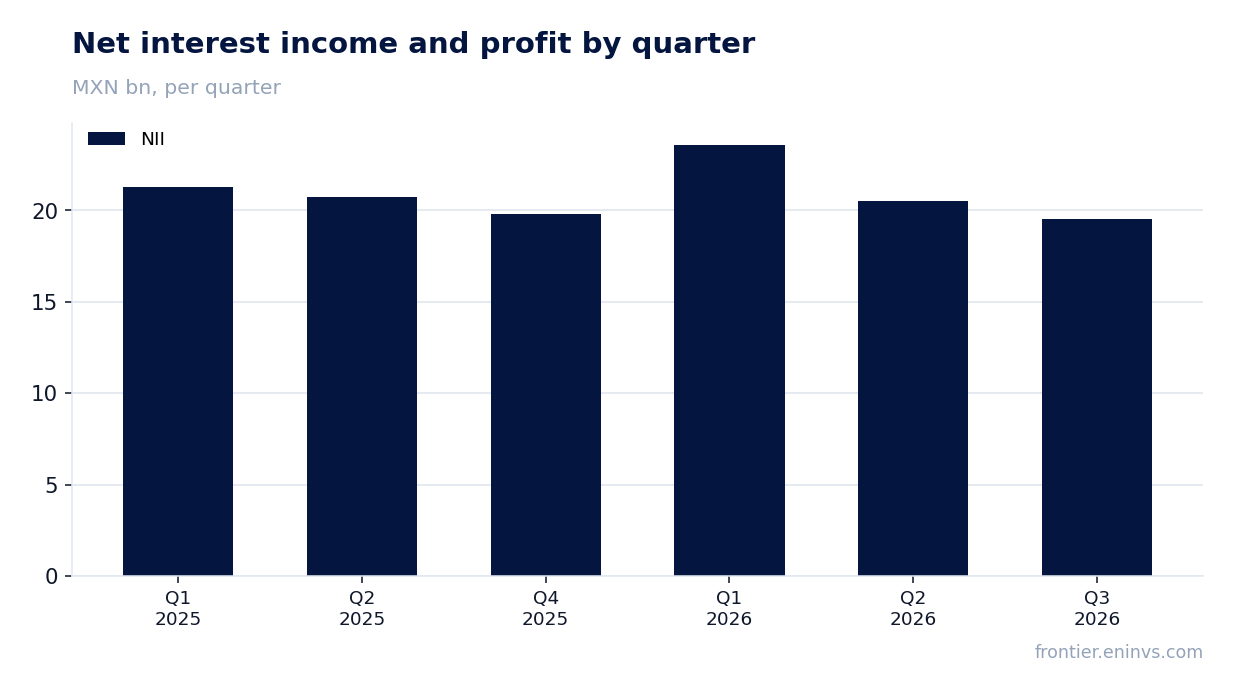
The profit decline coincided with a decline in net interest income. It was 19,552.3 million MXN in Q3 versus 20,515.5 million MXN in Q2 and 23,594.7 million MXN in Q1. Interest income is the bank's main revenue source, and its compression feeds straight through to profit.
Net interest income fell to 19,552.3 million MXN in Q3, and year-on-year growth decelerated from +10.9% to -1.0%
Net interest income in Q3 2026 was 19,552.3 million MXN. That is 4.7% below Q2 and 17% below Q1. The decline has run for two consecutive quarters.
Year-on-year dynamics deteriorated: in Q1 2026 income grew 10.9%, in Q2 it fell 1.0%. This is deceleration, not a reversal: the 2025 comparison base was high, while income has been shrinking sequentially through 2026.
Compression of net interest income is the main risk to profit. If it continues, quarterly profit could fall below 5,000 million MXN, and annual profit would then come in well below the 30,931.2 million MXN the current valuation rests on.
Trailing twelve-month profit of 30,931.2 million MXN against a market cap of 270,191.9 million MXN gives a P/E of 8.7
With a market cap of 270,191.9 million MXN and trailing twelve-month profit of 30,931.2 million MXN, the P/E LTM is 8.7. That is a moderate valuation for a bank, but it rests on profit that has been declining for three quarters.
If profit stays at the Q3 level, annual profit would be about 20,900 million MXN, and the P/E on that would rise to 12.9. The current multiple is therefore low relative to sustainable earnings, but only because it includes historical quarters that will not repeat.
A comparison with the stock's own three-year history is not possible: the facts contain neither an average nor past values of the multiple. The valuation therefore rests only on the current level and on the profit trajectory.
A return on equity of 7.3% is below what the current valuation requires
MX_INBURSA's return on equity is 7.3%. At a P/E of 8.7 the market pays about 11.5 kopecks of profit for every rouble of capital, meaning it demands a return above the current one.
For a bank, 7.3% is a modest level. It means capital is working at a low return, and growing profit without adding capital or widening the interest margin is difficult.
The portal model, which compares return on equity with the price-to-book ratio, puts the share's upside at +7% to the current price. That is a thin cushion, and it rests on the assumption that profit will not keep falling.
A 2.5% dividend yield is thinner than risk-free instruments and does not offset weak profit growth
MX_INBURSA's trailing twelve-month dividend yield is 2.5%. That is below the yield on risk-free instruments and gives the holder no margin of safety.
Trailing twelve-month profit of 30,931.2 million MXN and a market cap of 270,191.9 million MXN imply that only a small share of profit goes to dividends. If profit keeps falling, the dividend could be cut.
The dividend is not the main argument in this story. The key question is whether the bank can stop the decline in net interest income and return profit to Q1 levels.
The portal model puts the share's upside at +7% to the current price
The portal model, which compares a 7.3% return on equity with the price-to-book ratio, puts the upside at +7% to the current price. This is not a market consensus or a target price, but a model estimate.
The upside is small and depends entirely on profit holding up. If profit stays at the Q3 level, the P/E would rise to 12.9 and the model would show a decline rather than growth.
For a holder this means the share's growth cushion is limited. The main contribution to return comes from the 2.5% dividend, and that too is in question with falling profit.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 270 bn MXN |
| P/E (LTM) | 8.7 |
| P/B | 0.97 |
| ROE | 7.3% |
| Dividend yield (12m) | 2.5% |
Bottom line
There is little strength in the report: Q3 profit of 5,226.4 million MXN remains positive, and the 2.5% dividend yield offers some return. But profit has fallen for three consecutive quarters, net interest income has compressed to 19,552.3 million MXN, and year-on-year growth decelerated from +10.9% to -1.0%. The P/E of 8.7 looks moderate only because it rests on trailing twelve-month profit of 30,931.2 million MXN, which includes strong quarters that will not repeat. The verdict is neutral: the share looks neither cheap nor expensive, but growth requires a reversal in interest income that is not yet visible.
Open the company's financial profile INBURSA →
See also: market overview · valuation map · stock screeners