MX_KOF: revenue accelerated to 10.9%, but profit grows half as fast and net debt added 41.6 bn pesos in a year
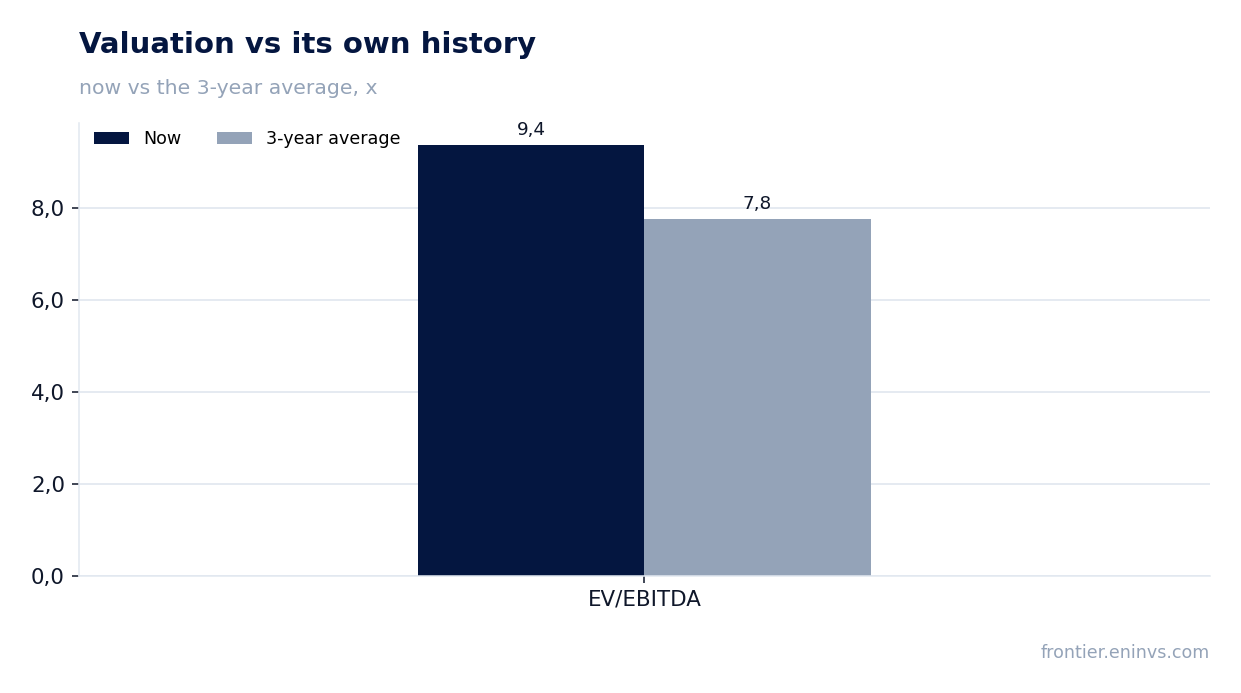
MX_KOF's third-quarter 2026 results showed revenue of 79,718 mn pesos (+10.9% YoY), EBITDA of 12,296 mn (+14.1%) and net profit of 6,223 mn (+5.5%). The acceleration in revenue from +4.7% in the second quarter kept the EBITDA margin at 15.4%, but the net margin narrowed to 7.8% from 8.2% a year earlier, and net debt at end-September stood at 84,370 mn pesos versus 42,759 mn a year before. At an EV/EBITDA of 9.4 against its own three-year average of 7.8 the share looks more expensive than its history, so the verdict is neutral.
Key takeaways
— Revenue accelerated to 10.9% YoY from 4.7% in the second quarter, the best pace since the start of 2026
— EBITDA rose 14.1%, outpacing revenue and holding the margin at 15.4% versus 15.0% a year earlier
— Net profit grew only 5.5%, and the margin narrowed to 7.8% from 8.2% – below the operating dynamic
— Net debt rose over the year from 42.8 bn to 84.4 bn pesos, and its ratio to LTM EBITDA stands at 1.57
— Trailing twelve-month dividend yield is 3.56%, below the yield we consider fair for this story
— EV/EBITDA of 9.4 is 21% above its own three-year average of 7.8 – the market has already priced in continued acceleration
— On the portal's model the upside to fair value is +5%, which does not cover execution risk
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 71.9 | 79.7 | +10.9% |
| EBITDA | 10.8 | 12.3 | +14.1% |
| Operating profit | 10.2 | 11.8 | +15.3% |
| Net profit | 5.90 | 6.22 | +5.5% |
| EBITDA margin | 15.0% | 15.4% | +0.4 pp |
| Net margin | 8.2% | 7.8% | -0.4 pp |
Revenue accelerated to 10.9% YoY from 4.7% in the second quarter, the best pace since the start of 2026
In the third quarter of 2026 revenue reached 79,718 mn pesos, 10.9% more than a year earlier. That is a marked acceleration from +4.7% in the second quarter and +1.1% in the first: the growth rate gathered pace through the year.
The acceleration lifted quarterly revenue to its highest level in the presented history – above 77,762 mn in the fourth quarter of 2025. Over the trailing twelve months revenue was 304,700 mn pesos, with the third quarter contributing the largest share among the 2026 quarters.
For valuation it matters that the acceleration was not a one-off: it confirms the company can build momentum after a weak start to the year. The next report will show whether the pace holds or the third quarter proves a local peak.
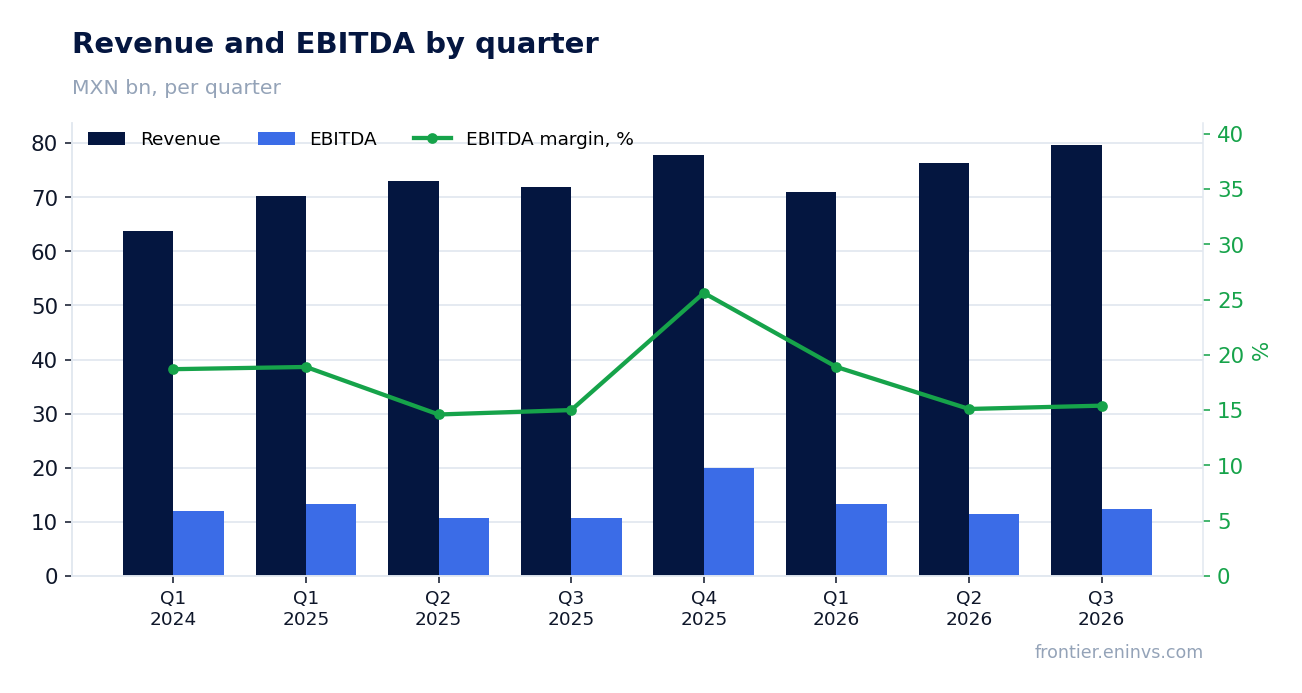
EBITDA rose 14.1%, outpacing revenue and holding the margin at 15.4% versus 15.0% a year earlier
EBITDA for the third quarter of 2026 was 12,296 mn pesos, 14.1% more than a year earlier. Growth outpaced revenue, and the EBITDA margin widened to 15.4% from 15.0% in the third quarter of 2025.
Operating profit rose to 11,756 mn pesos from 10,194 mn a year earlier. The gap between EBITDA and operating profit is small, indicating that operating activity, not one-off items below that line, drives the result.
Margin expansion alongside accelerating revenue is a strong signal: the company did not buy growth through discounts or extra costs. Over the trailing twelve months EBITDA was 53,815.3 mn pesos, and the third quarter supported that base.
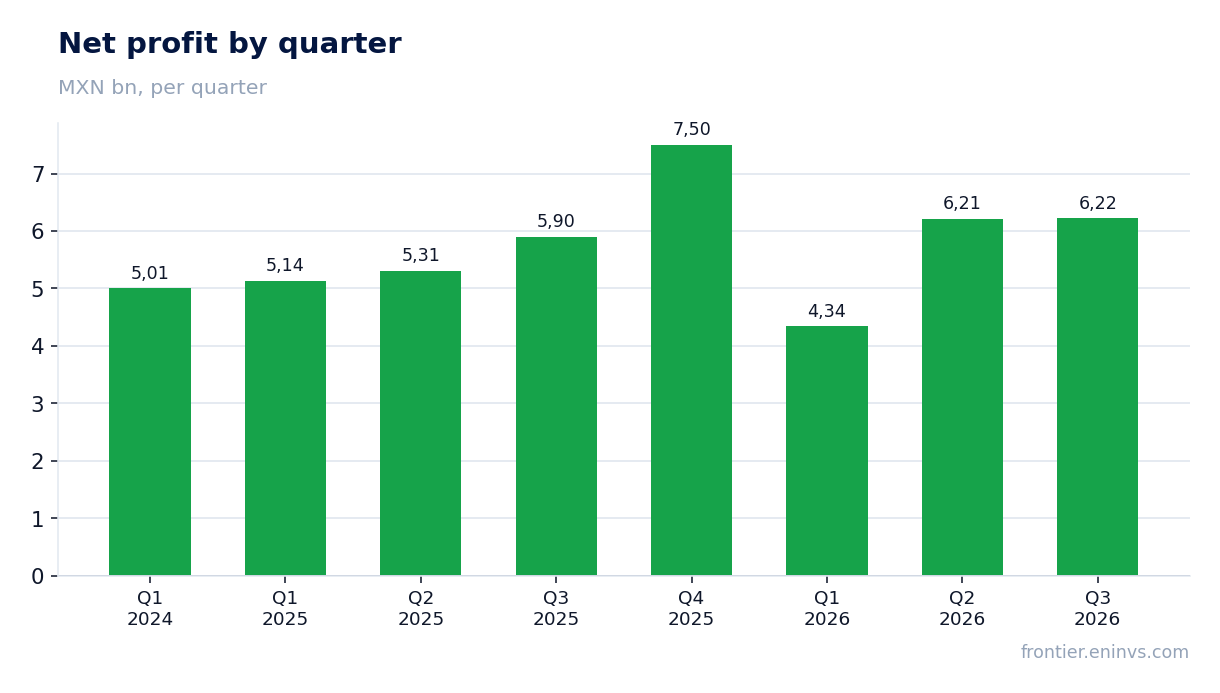
Net profit grew only 5.5%, and the margin narrowed to 7.8% from 8.2% – below the operating dynamic
Net profit for the third quarter of 2026 was 6,223 mn pesos, only 5.5% more than a year earlier. With EBITDA up 14.1%, the gap means additional costs or a changed tax burden appeared below the operating line.
The net margin narrowed to 7.8% from 8.2% in the third quarter of 2025. The operating dynamic was strong, but it did not fully reach net profit – the key question of the report.
Over the trailing twelve months net profit was 24,278 mn pesos. If the gap between EBITDA and net profit persists, accelerating revenue will deliver ever less earnings-per-share growth, and that is what ultimately drives valuation.
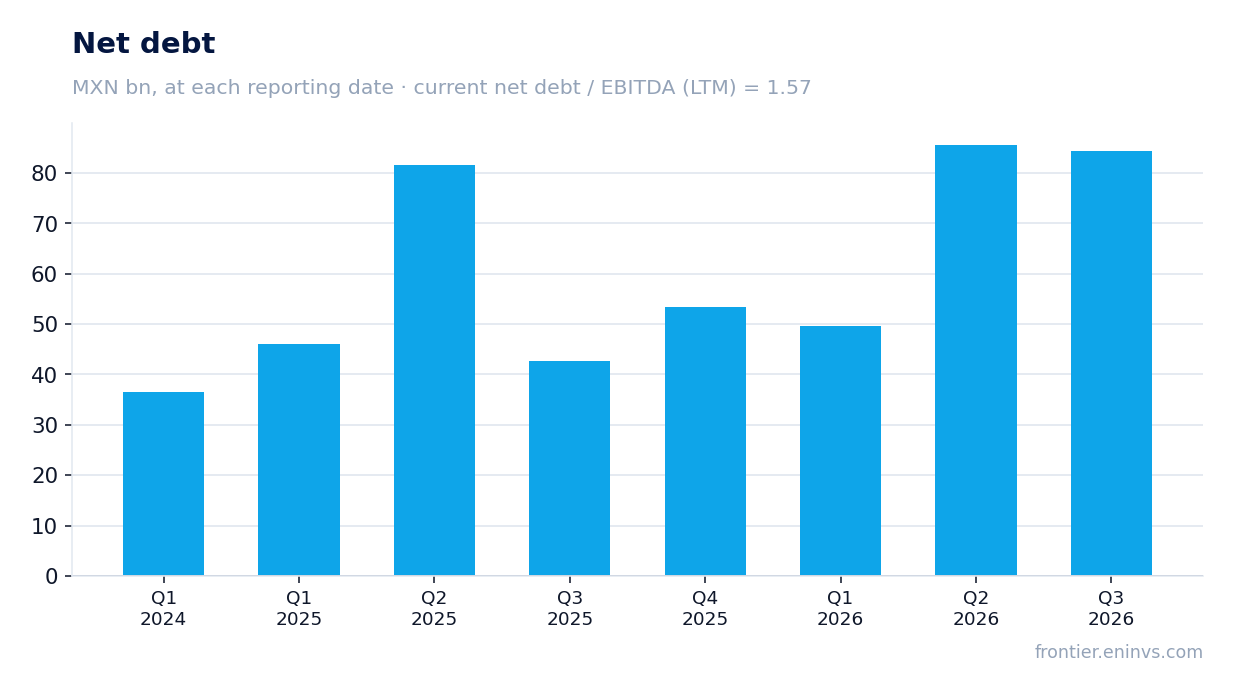
Net debt rose over the year from 42.8 bn to 84.4 bn pesos, and its ratio to LTM EBITDA stands at 1.57
Net debt at 30 September 2026 was 84,370 mn pesos versus 42,759 mn at 30 September 2025 – an increase of 41.6 bn over the year. In the third quarter debt was almost flat: from 85,625 mn at 30 June it fell by 1.3 bn.
The ratio of net debt to trailing twelve-month EBITDA is 1.57. That is a moderate level, but it is double the year-earlier figure, when debt was 42.8 bn against comparable EBITDA.
Rising debt means part of the revenue acceleration was financed with borrowed money. At the rate the market demands from Mexican issuers, servicing that debt will be a notable cost line and one explanation for weak net profit growth.
Trailing twelve-month dividend yield is 3.56%, below the yield we consider fair for this story
The trailing twelve-month dividend yield is 3.56%. At a market capitalisation of 451,007 mn pesos that corresponds to payouts of roughly 16 bn pesos a year.
Our estimate for the current year's dividend starts from LTM profit of 24,278 mn pesos and the payout ratio the company has maintained in recent years. If the current policy holds, the payout will stay close to last year's level and will depend on whether net profit holds at the LTM level.
A yield of 3.56% is modest for a market where the risk-free rate is high. If profit does not accelerate, the dividend is unlikely to become the main argument for the share – it will support the valuation rather than create it.
EV/EBITDA of 9.4 is 21% above its own three-year average of 7.8 – the market has already priced in continued acceleration
On the trailing twelve-month EV/EBITDA the share trades at 9.4 against its own three-year average of 7.8 – 21% above. That means the market values the company more dearly than it did on average over the past three years.
The trailing P/E is 18.6 and return on equity is 17.0%. The return on capital is decent, but it is already in the price: at current profit the market pays more for each peso of earnings than it is used to.
On the portal's model the upside to fair value is +5%. That is modest: to justify the current price the company needs not merely to hold revenue acceleration but to carry it through to net profit.
On the portal's model the upside to fair value is +5%, which does not cover execution risk
Our model puts fair value 5% above the current price. This is our own calculation, based on EBITDA growth and a target multiple, not a market consensus.
An upside of 5% is small compensation for uncertainty: the gap between EBITDA and net profit growth, rising debt and a multiple above its historical average create an asymmetry that does not favour the buyer.
If the next report shows net profit catching up with EBITDA and debt stops rising, the model will revise upwards. For now it says the share is fairly valued, but without a margin of safety.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 451 bn MXN |
| P/E (LTM) | 18.6 |
| EV/EBITDA (LTM) | 9.4 |
| P/B | 3.08 |
| Net debt / EBITDA (LTM) | 1.57 |
| ROE | 17.0% |
| Dividend yield (12m) | 3.6% |
| EV/EBITDA, 3-year average | 7.8 |
Bottom line
The strong side of the report is revenue acceleration to 10.9% and EBITDA margin expansion to 15.4%: the company is growing faster than a year ago, and not through discounts. The weak side is net profit up only 5.5%, while debt rose over the year from 42.8 bn to 84.4 bn pesos, which at 1.57 times EBITDA warrants attention. A dividend yield of 3.56% and portal-model upside of +5% leave no cushion, and an EV/EBITDA of 9.4 against a three-year average of 7.8 says the market already believes in continued acceleration. The verdict is neutral: the share is fairly valued but has no room for error, and an upgrade requires seeing revenue acceleration reach net profit with stable debt.
Open the company's financial profile KOF →
See also: market overview · valuation map · stock screeners