Genomma Lab: net income up 18.6% on financing lines while EBITDA fell 10.3%
On October 21, Genomma Lab Internacional reported third-quarter 2026 results. Revenue rose 1.3% to MXN 4,497.6 million, EBITDA fell 10.3% to MXN 944.9 million at a 21.0% margin, and net income added 18.6% to MXN 514.9 million. The profit gain came not from operations but from lower interest expense and a one-off favourable FX result, while operating profit dropped 10.8%. With a P/E of 9.3 against a historical EV/EBITDA of 5.6 and a 5.5% dividend yield, the share looks rather attractive, but weak operating momentum and rising debt call for caution.
Key takeaways
— Revenue rose only 1.3%, with all the growth coming from Latin America and beverages
— EBITDA fell 10.3% on promotions and destruction of returned products in the U.S.
— Net income rose 18.6% on lower interest expense and a one-off FX result
— Operating cash flow grew 12.5%, but free cash flow covered dividends only partly
— Net debt rose from MXN 2.1 billion on June 30 to MXN 4.1 billion on September 30
— Dividend yield of 5.5% on a quarterly payout of MXN 0.20 per share
— P/E of 9.3 and EV/EBITDA below the 3-year average point to undervaluation
Attractiveness
Key figures, MXN bn
| Metric | — | Q3 2026 | Change |
|---|---|---|---|
| Revenue | — | 4.50 | — |
| EBITDA | — | 0.94 | — |
| Operating profit | — | 0.86 | — |
| Net profit | — | 0.51 | — |
| Operating cash flow | — | 0.50 | — |
| EBITDA margin | — | 21.0% | — |
| Net margin | — | 11.4% | — |
Revenue rose only 1.3%, with all the growth coming from Latin America and beverages
Consolidated revenue for the third quarter of 2026 was MXN 4,497.6 million, up 1.3% year on year. Growth came from Latin America, where sales rose 12.2%, and from beverages, up 58.8%. Mexico declined 2.4% and the U.S. fell 30.5%.
Mexico improved for the third consecutive quarter: from a low of -22.1% in Q4 2025, the decline slowed to -2.4%. Sell-out returned to growth, and the innovation launched in late June drove 39% sell-out growth at customers carrying it. Suerox reached a record 12.6% value share at the leading retailer.
Latin America's 12.2% growth combined strong results in Central America and the Andean region with 39.2% growth in Argentina. Brazil reduced purchases ahead of tax reform, and the company expects sell-in to normalise in Q1 2027. The U.S. decline of 30.5% reflects distribution gaps amid weakness in the Hispanic retail market.
The revenue mix is shifting toward faster-growing but lower-margin categories. Beverages and infant nutrition are growing at double-digit rates, while OTC and personal care, the largest segments, are contracting 5.0% and 9.7% respectively. This limits the scope for margin recovery in the coming quarters.
EBITDA fell 10.3% on promotions and destruction of returned products in the U.S.
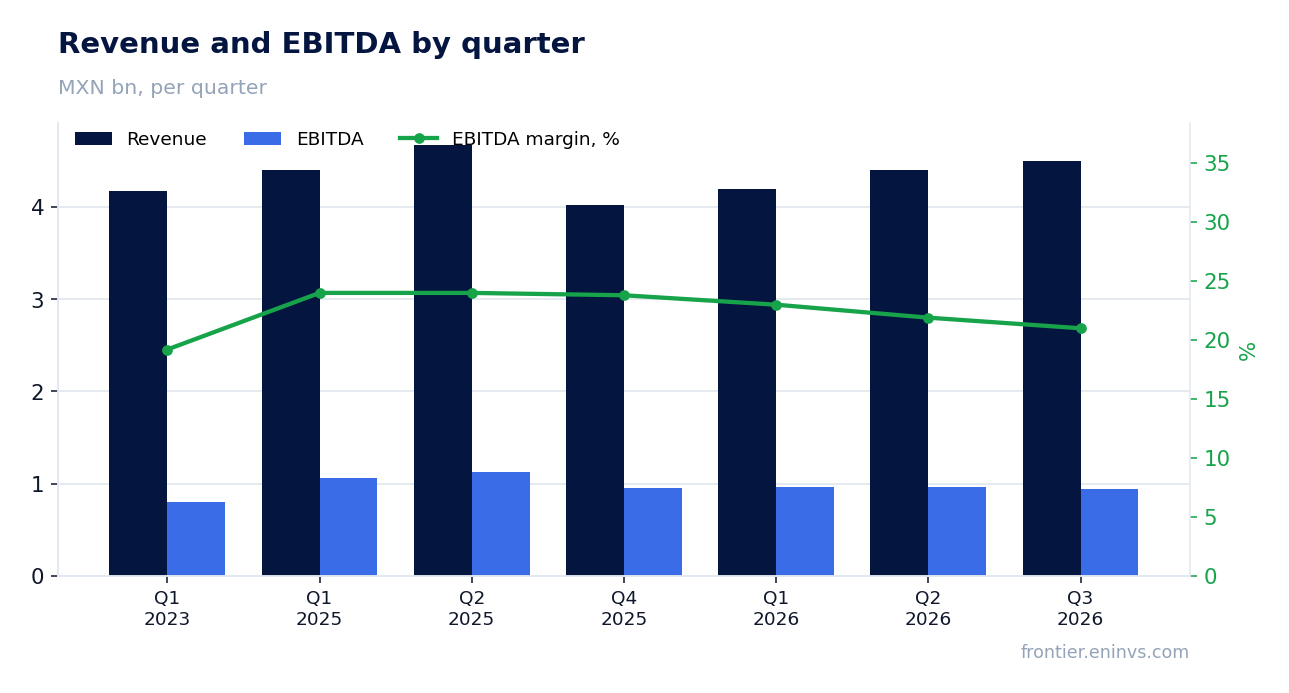
EBITDA for the third quarter was MXN 944.9 million, down 10.3% year on year. The EBITDA margin compressed to 21.0% from 23.7% a year earlier. The main pressure came from higher promotional spending and the destruction of returned products in the U.S., as well as the fully absorbed impact of Mexico's new tax on non-caloric sweetened beverages.
Gross margin fell to 61.4% from 63.9%, losing 244 basis points. The company offset part of the pressure with a 1.1% reduction in SG&A expenses, but this was not enough to hold operating profit. Operating profit fell 10.8% to MXN 863.6 million.
By region, the margin in Mexico was 20.0%, down 705 basis points on upfront investment in promotions and commercial spending. In Latin America, the margin expanded 190 basis points to 23.7% on operating leverage. In the U.S., the margin fell 492 basis points to 8.6% on deleverage and write-offs.
The company describes the investment in promotions and commercial spending as a deliberate decision to accelerate growth. So far, however, this decision has not produced revenue growth outpacing costs: revenue rose 1.3% while EBITDA fell 10.3%. Margin recovery depends on how quickly new products and promotions begin to generate sales.
Net income rose 18.6% on lower interest expense and a one-off FX result
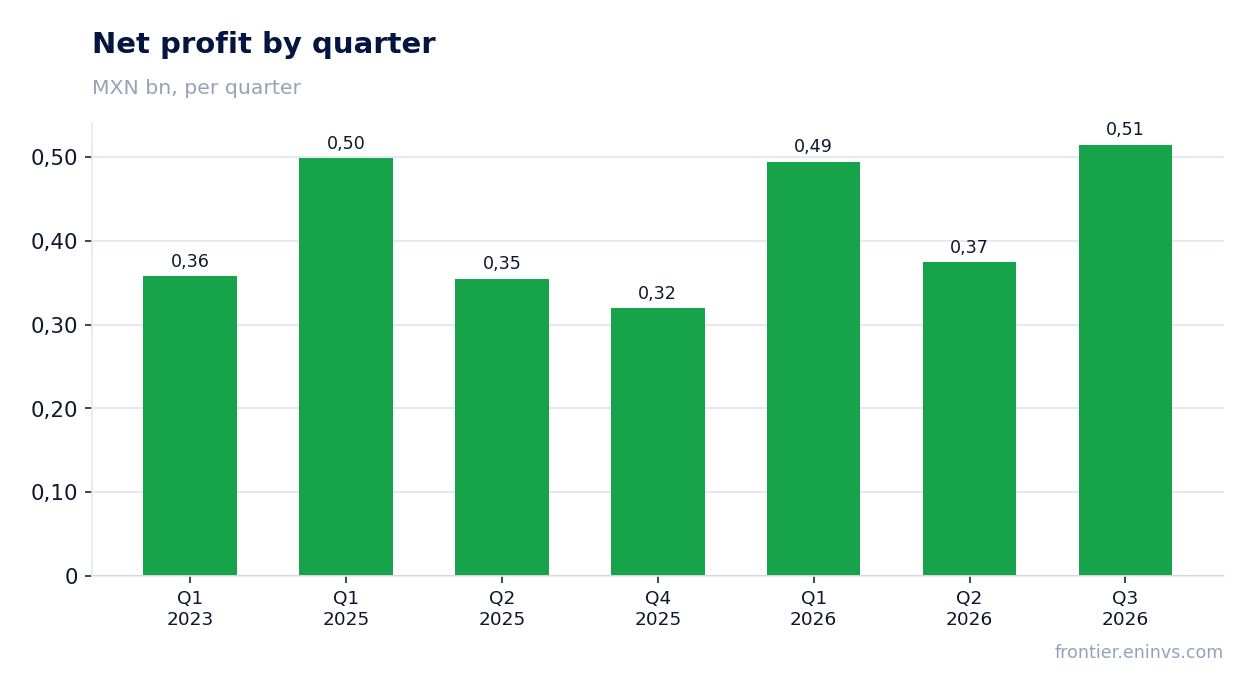
Net income for the third quarter was MXN 514.9 million, up 18.6% year on year. The profit growth is not linked to operating results: operating profit fell 10.8%. The main contribution came from a 32.1% reduction in interest expense to MXN 130.2 million and a positive FX result of MXN 41.1 million versus a negative MXN 122.7 million a year earlier.
The decline in interest expense reflects debt refinancing: short-term debt fell 63% to MXN 1,185.2 million and is covered 2.3 times by cash of MXN 2.76 billion. However, total debt has risen, and interest expense could return to growth.
The FX result of MXN 41.1 million is a one-off factor unlikely to repeat next quarter. Without it, net income would have been lower. The inflationary result from the monetary position increased 37.2% to a negative MXN 103.6 million, partially offsetting the positive effect.
Thus, the quality of earnings in the reported quarter is lower than the headline suggests. The sustainability of net income will depend on operating recovery and the trajectory of interest expense, not on FX differences.
Operating cash flow grew 12.5%, but free cash flow covered dividends only partly
Operating cash flow for the third quarter grew 12.5% to MXN 495.6 million. The increase came despite a planned MXN 476 million investment in working capital ahead of the winter season. Free cash flow rose 52% to MXN 470 million from MXN 309 million a year earlier.
Working capital increased: receivables rose 12 days and inventories 21 days. The company attributes this to preparation for the winter season and cough-and-cold launches in Q4 2026 and Q1 2027, as well as purchases ahead of expected price increases. Part of the receivables increase reflects a non-cash hyperinflationary accounting effect in Argentina.
The company expects the cash conversion cycle to decline to approximately 140 days in Q4 2026, a reduction of about 25 days. This should support cash flow, but free cash flow of MXN 470 million does not fully cover the MXN 194.7 million in dividends paid in the quarter and capital expenditure.
Capital expenditure in the third quarter was MXN 24.8 million, well below MXN 130.7 million a year earlier. Lower capex helped free cash flow but may constrain future growth.
Net debt rose from MXN 2.1 billion on June 30 to MXN 4.1 billion on September 30
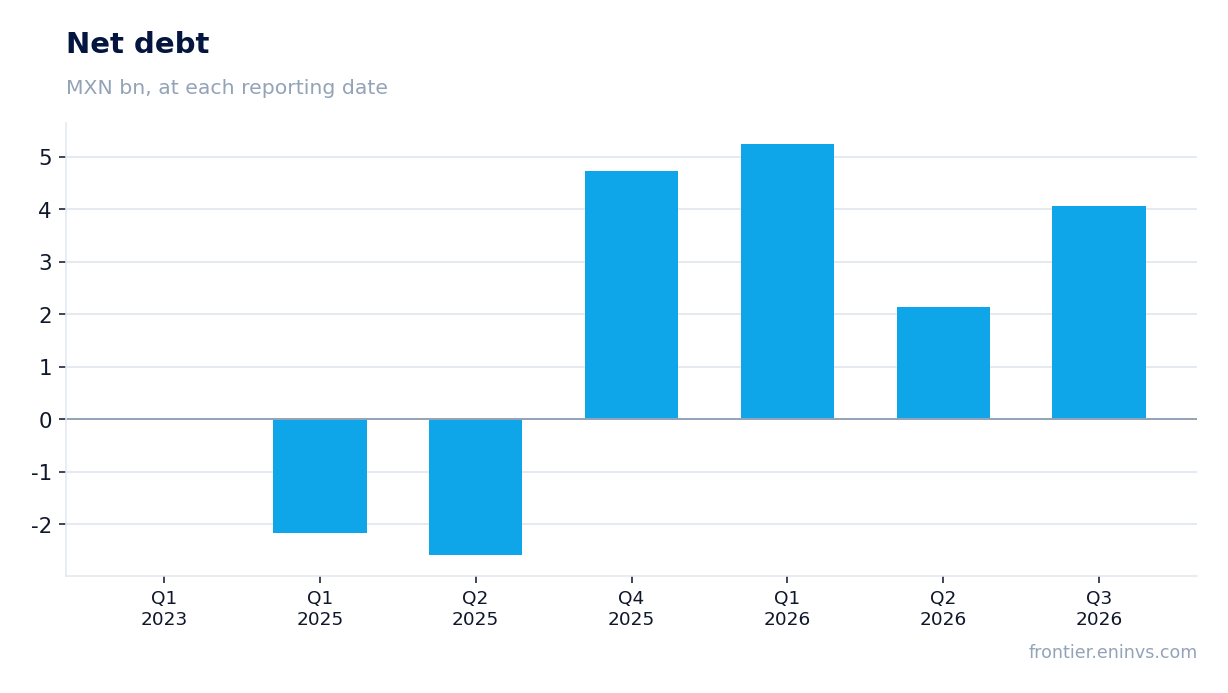
Net debt as of September 30, 2026 was MXN 4,057.3 million. From June 30, 2026, it rose from MXN 2.1 billion to MXN 4.1 billion, an increase of MXN 1.9 billion. Over twelve months, net debt rose from negative MXN 2.6 billion on June 30, 2025 to MXN 4.1 billion on September 30, 2026, a change of +MXN 6.6 billion.
The debt increase is partly linked to refinancing: short-term debt fell 63% to MXN 1,185.2 million, but long-term loans from financial institutions rose 123.1% to MXN 3,426.7 million. The company also paid MXN 194.7 million in dividends and spent on working capital.
The net debt / EBITDA ratio is 1.4x, which is moderate. However, rising absolute debt against falling EBITDA increases leverage. The debt service coverage ratio is 5.5x, providing a cushion, but if current EBITDA dynamics persist, the cushion will shrink.
The company reports that after long-term refinancing, short-term debt is covered 2.3 times by cash. This reduces short-term refinancing risk, but total debt remains significant.
Dividend yield of 5.5% on a quarterly payout of MXN 0.20 per share
On September 30, 2026, the company paid a cash dividend of MXN 0.20 per share, totalling MXN 194.7 million. The company intends to continue paying quarterly dividends. The trailing twelve-month dividend yield is 5.5%.
Our estimate for the current year's dividend assumes the quarterly payout remains at MXN 0.20 per share, which at the current price gives a yield of about 5.5%. The payout depends on profit and cash flow: trailing twelve-month net income was MXN 1,614.0 million, and trailing twelve-month free cash flow was MXN 1,420 million. Quarterly dividend payments of MXN 194.7 million correspond to about 12% of trailing twelve-month profit.
The 5.5% yield exceeds the yield on Mexican government bonds, making the dividend attractive to investors. However, rising debt and falling EBITDA could limit the company's ability to sustain payments. If operating profit continues to decline, the company may revise the dividend.
The risk of a dividend cut is linked to the need to fund working capital and service the increased debt. The company has already cut capital expenditure to support cash flow, but further margin pressure could require a more conservative approach to profit distribution.
P/E of 9.3 and EV/EBITDA below the 3-year average point to undervaluation
The trailing twelve-month P/E is 9.3. The trailing twelve-month EV/EBITDA is not provided, but the 3-year average is 5.6. The current multiple is below the historical average, which may indicate undervaluation. However, the comparison with the historical average is limited because the current EV/EBITDA is not in the facts.
According to the portal's model, which estimates fair value through EBITDA growth and a target multiple, the upside to fair value is +9%. This is the portal's own estimate, not market consensus.
Return on equity is 17.2%, a high figure. However, falling EBITDA and rising debt could pressure future profit. The 5.5% dividend yield provides support for the share price.
The share trades at a discount to its historical EV/EBITDA average, but operating risks and rising debt justify some discount. A re-rating requires sustained revenue growth and margin recovery.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 15.1 bn MXN |
| P/E (LTM) | 9.3 |
| P/B | 1.36 |
| ROE | 17.2% |
| Dividend yield (12m) | 5.5% |
Bottom line
The report's strengths were 12.2% revenue growth in Latin America, a recovery in Mexican sell-out, and a 52% increase in free cash flow. However, net income rose 18.6% mainly on a one-off FX result and lower interest expense, not on operations. EBITDA fell 10.3%, the margin compressed to 21.0%, and net debt rose to MXN 4.1 billion. With a P/E of 9.3 and a 5.5% dividend yield, the share looks rather attractive, but confirmation of sustainability requires operating profit growth and debt control.
Open the company's financial profile LAB →
See also: market overview · valuation map · stock screeners