PH_MBT: Q3 2026 profit fell 7.3% even as net interest income rose to PHP 41.8 bn
PH_MBT reported Q3 2026 results: operating profit of PHP 19,371 mn, net profit of PHP 11,524 mn, down 7.3% year on year. Net interest income rose to PHP 41,757 mn, while top-line growth decelerated to 5.5% YoY from 13.3% in Q2. With a trailing P/E of 5.55 and a dividend yield of 8.29%, the share looks rather attractive, though weaker profit and slowing revenue keep the rating from being higher.
Key takeaways
— Q3 2026 net profit fell 7.3% to PHP 11,524 mn even as net interest income rose to PHP 41,757 mn
— Top-line growth decelerated to 5.5% YoY from 13.3% in Q2
— Operating profit of PHP 19,371 mn came in below last year's PHP 20,159 mn
— A dividend yield of 8.29% against a P/E of 5.55 leaves room to the yield we consider fair
— On the portal's model the share trades at roughly a 17% discount to modelled fair value
Attractiveness
Key figures, PHP bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net interest income | 39.6 | — | — |
| EBITDA | 21.6 | — | — |
| Operating profit | 20.2 | 19.4 | -3.9% |
| Net profit | 12.4 | 11.5 | -7.3% |
| Capex | 2.04 | — | — |
| EBITDA margin | 54.6% | — | — |
| Net margin | 31.4% | — | — |
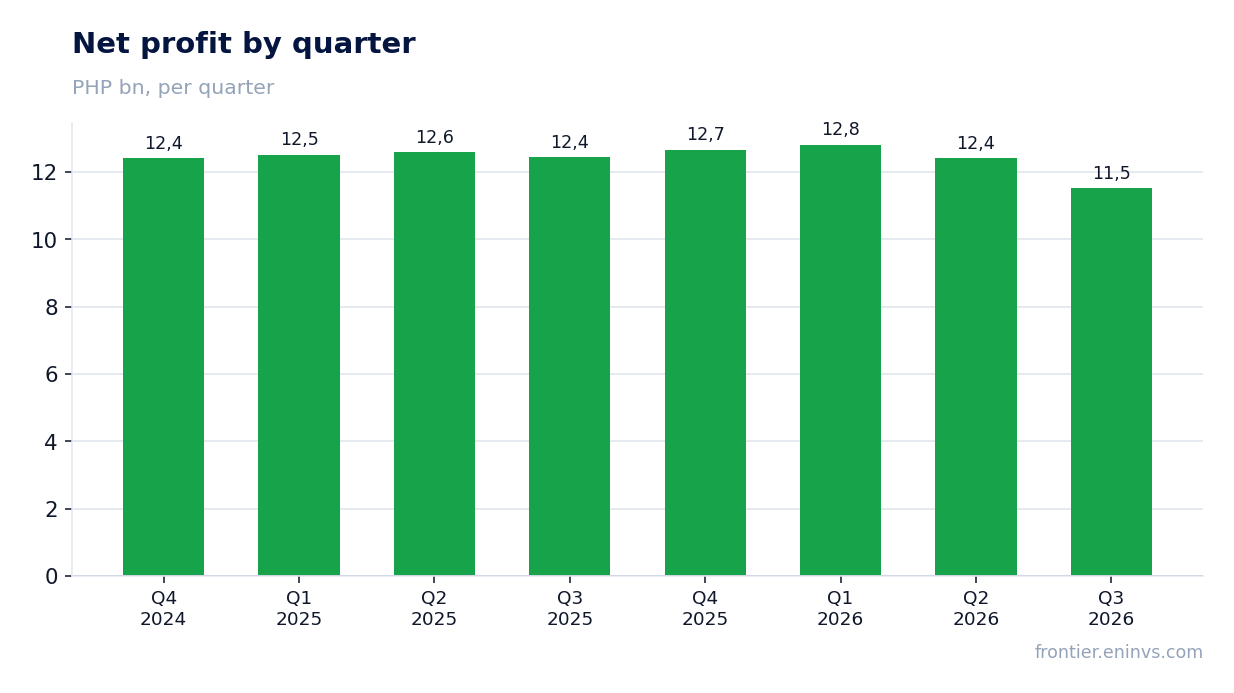
Q3 2026 net profit fell 7.3% to PHP 11,524 mn even as net interest income rose to PHP 41,757 mn
Q3 2026 net interest income reached PHP 41,757 mn, above PHP 39,568 mn a year earlier and PHP 41,131 mn in Q2. The top line is growing, but profit is not keeping pace: quarterly net profit was PHP 11,524 mn versus PHP 12,432 mn a year ago, a decline of 7.3%.
Operating profit also fell to PHP 19,371 mn from PHP 20,159 mn in Q3 2025. Costs are rising faster than income, and net interest income no longer fully offsets that. Over the trailing twelve months net profit was PHP 49,403 mn, the base for dividends and for the multiple.
For a holder, what matters is not the absolute profit level but its stability. Quarterly profit has stayed in a narrow PHP 11.5–12.8 bn range for several quarters, and the current decline is the first notable move lower in that period.
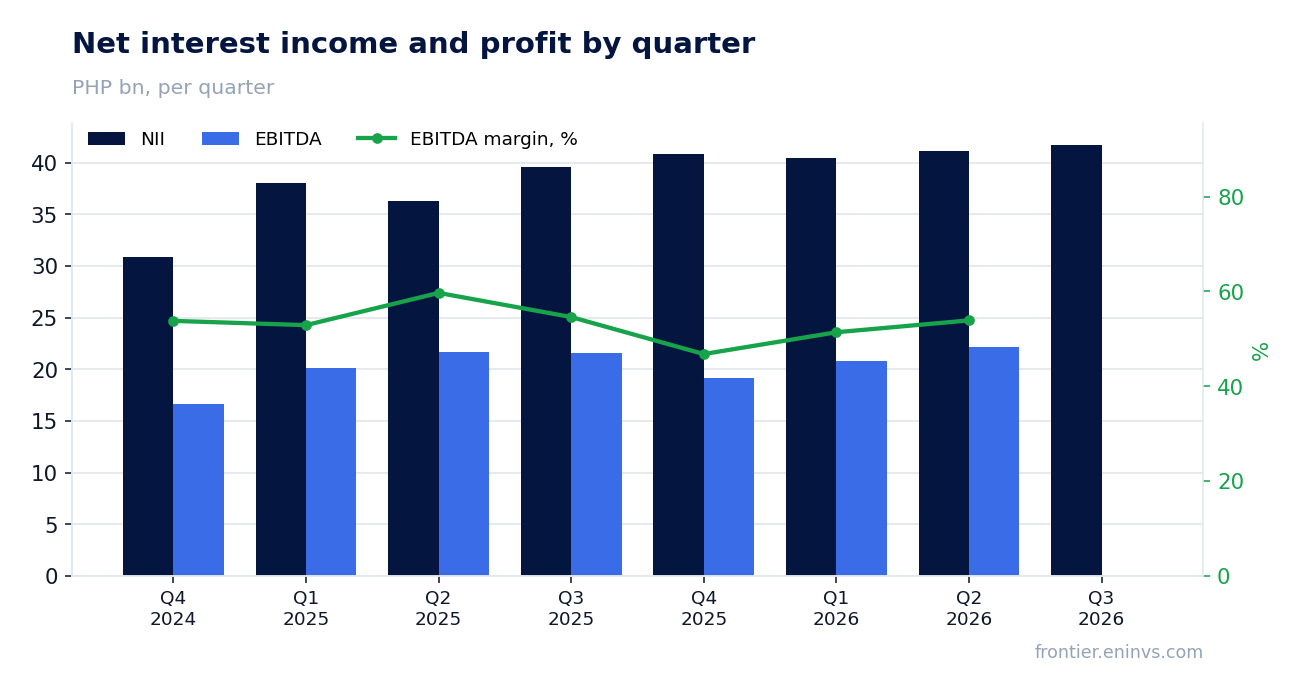
Top-line growth decelerated to 5.5% YoY from 13.3% in Q2
Q3 2026 net interest income grew 5.5% YoY, well below the 13.3% seen in Q2. The deceleration came as the quarterly figure was almost flat: PHP 41,757 mn versus PHP 41,131 mn.
The growth record over recent quarters is uneven: 6.0% in Q3 2025, 32.4% in Q4, 6.4% in Q1 2026, 13.3% in Q2 and 5.5% in Q3. That spread suggests individual quarters carry one-off components, so a single quarter is a poor guide to the trend.
Slowing top-line growth is the main argument against a higher rating. If growth returns to double digits in the next report, some of the concern will ease; if it stays near 5%, pressure on profit will persist.
Operating profit of PHP 19,371 mn came in below last year's PHP 20,159 mn
Q3 2026 operating profit was PHP 19,371 mn versus PHP 20,159 mn a year earlier. With net interest income up 5.5%, operating profit fell, meaning costs grew faster than income.
The gap between net interest income and operating profit, at PHP 22.4 bn, is operating expenses and provisions. That is the part of the report eating into top-line growth, and it determines whether revenue growth turns into profit growth.
Over the trailing twelve months operating profit has held around PHP 19–20 bn per quarter. The durability of that level as revenue growth slows is the key question for the next report.
A dividend yield of 8.29% against a P/E of 5.55 leaves room to the yield we consider fair
The trailing twelve-month dividend yield is 8.29%. With trailing net profit of PHP 49,403 mn and a market cap of PHP 274,342 mn, payouts are covered by earnings with room to spare if the payout ratio stays at its current level.
Our estimate for the current year's dividend is based on trailing twelve-month profit and the current payout ratio; it hinges on profit holding near PHP 49 bn. The 7.3% fall in quarterly profit is the first risk to that base.
A yield of 8.29% is well above what the money market offers at the current policy rate, and that is the main reason the share looks attractive. If profit keeps falling, the payout may shrink and the yield will no longer be as high.
On the portal's model the share trades at roughly a 17% discount to modelled fair value
The trailing P/E is 5.55 and ROE is 10.96%. On the portal's model, which sets ROE against price-to-book, the upside of the share to modelled fair value is +17%.
This is our own estimate, not a market consensus or a target price. It rests on current earnings and the current price; if earnings fall, modelled fair value falls with them.
The share is held in the portal's live model strategies, including PH Banks, but that is a membership fact, not an argument for the rating. The rating itself rests on the multiple, the yield and the direction of profit.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 274 bn PHP |
| P/E (LTM) | 5.6 |
| P/B | 0.63 |
| ROE | 11.0% |
| Dividend yield (12m) | 8.3% |
Bottom line
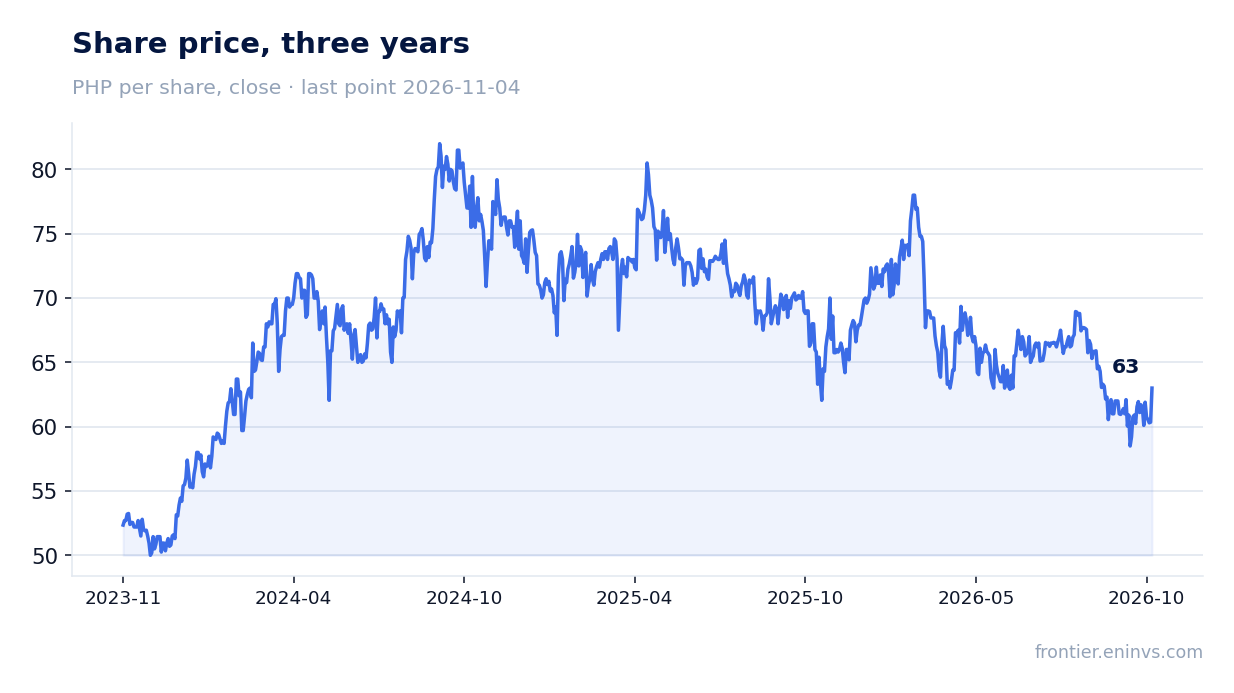
The strong part of the report is net interest income of PHP 41,757 mn and a dividend yield of 8.29% at a P/E of 5.55. The weak part is the 7.3% fall in net profit and deceleration of top-line growth to 5.5%. On the portal's model the share trades at roughly a 17% discount to modelled fair value, and that, together with the yield, outweighs concerns about profit. The key question for a holder is whether revenue growth returns to double digits; if not, the dividend and profit will come under pressure.
Open the company's financial profile MBT →
See also: market overview · valuation map · stock screeners