ABZ-1: RUB 15bn of bonds at a plant with RUB 2bn of EBITDA – a credit of the Baltic Project group, not of the plant, and a 19.5% yield for that
ABZ-1 is Asphalt Concrete Plant No. 1 JSC, a St Petersburg producer of road materials and the bond issuer of the road-construction group Baltic Project. There are 8 issues outstanding totalling RUB 15.2bn (the latest, 002P-07 of RUB 1bn at 17.75%, was placed on 28.08-02.09.2026); fixed-coupon issues yield 18.4-19.7% at a spread of 400-500 bp over OFZ, floaters 19-20%. Verdict: this is the debt of the whole group hung on a single plant. ABZ-1's own EBITDA is RUB 2.0bn a year against RUB 15bn of bonds, and the difference has been lent into the group. These bonds can only be bought as Baltic Project group risk, rated A-.ru by NKR and ruA- by Expert RA through the guarantee, and the answer to "how does it get paid" lies in the consolidated accounts due at the end of September.
The issuer card on the portal with financials by period, our credit analysis and all issues: ABZ-1. Below are the calculations of Enhanced Investments based on the issuer's IFRS and RAS statements, the MOEX payment schedule and disclosures; where a figure is the authors' estimate, it is marked as such.
What we are buying: a plant with RUB 9bn of revenue and RUB 15bn of bonds – the arithmetic does not work without the group
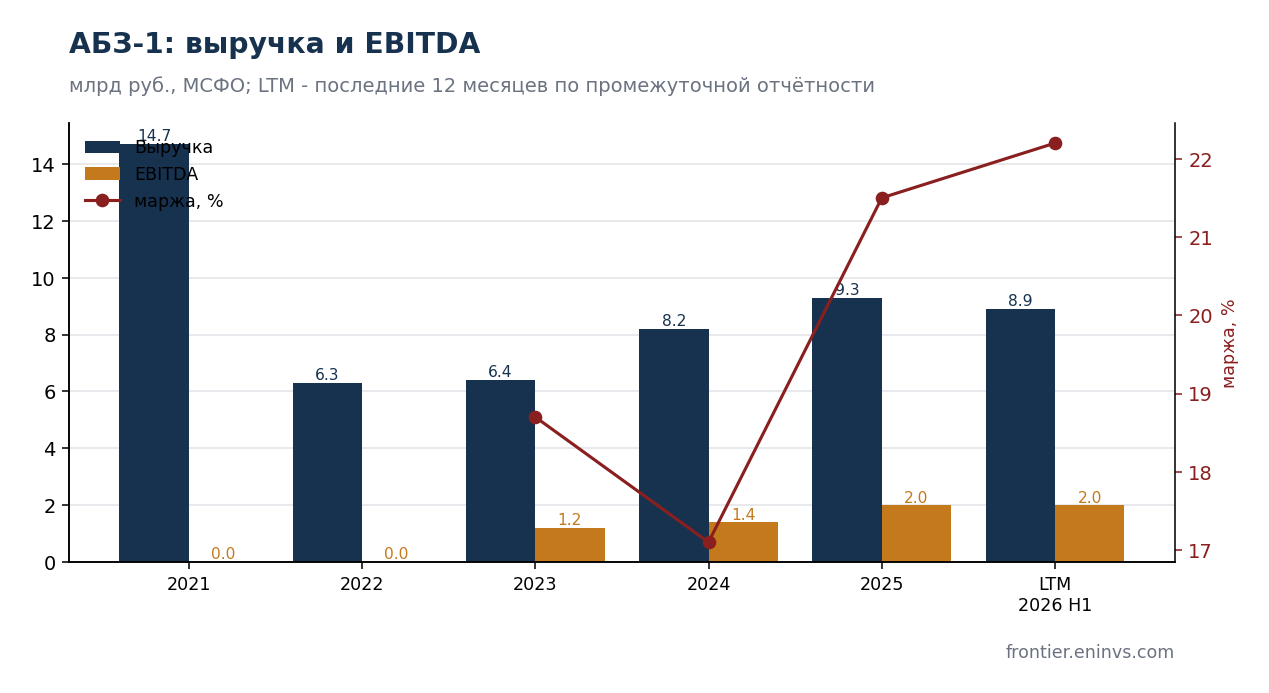
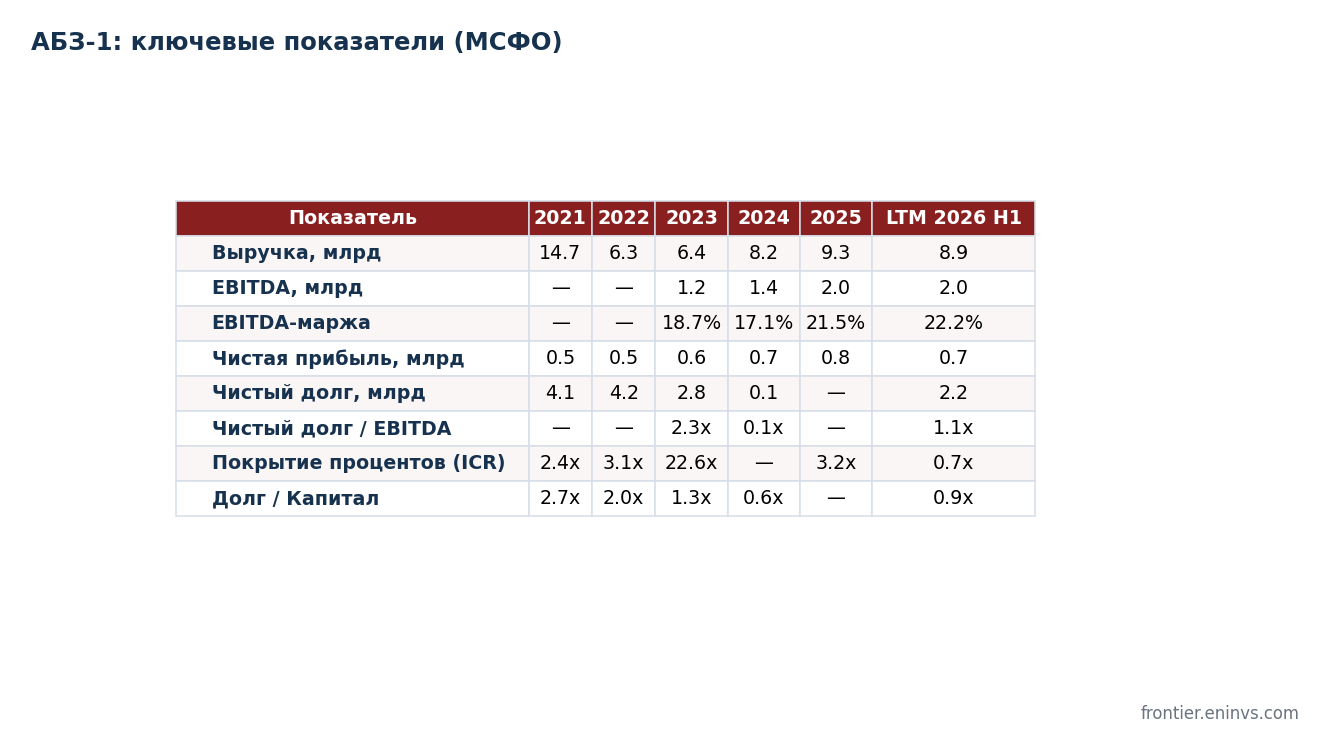
Fact. Under the consolidated IFRS of ABZ-1 JSC itself, 2025 revenue was RUB 9.3bn, EBITDA RUB 2.0bn (21.5% margin), net profit RUB 0.8bn. In 1H2026 revenue was RUB 2.6bn (minus 13% year on year), EBITDA RUB 0.6bn, net loss RUB 0.1bn – the business is seasonal, the first half is always weak and most revenue comes in the second. The plant's net debt at 30.06.2026 is only RUB 2.2bn, 1.1x EBITDA, debt to equity 0.9x.
Authors' estimate. With RUB 15.2bn of bonds outstanding, net debt of RUB 2.2bn means that about RUB 13bn of the money raised sits on the plant's balance sheet as loans and deposits, that is, passed to the parent PSF Baltic Project JSC and other group companies. Interest on the bonds at coupons of 17.5-25.5% is roughly RUB 2.8-3bn a year, one and a half times the plant's EBITDA. It is serviced not by the plant but by interest income on loans issued to the group. This is why the plant's LTM operating-profit interest cover is 0.7x while the accounts still show a profit.
Group credit: road construction on government contracts with a two-year backlog and leverage of about 3x FFO
Fact. The Baltic Project group runs the full road-construction cycle in the North-West: from producing materials to building and handing over facilities, plus a 30-year concession for the tram network in St Petersburg. According to the latest public ACRA release on the group (November 2023, BBB(RU)), the contract backlog was RUB 36.7bn, at least two average annual revenues, debt to FFO 2.5-3.5x, interest cover about 3x, FFO margin 12-15%. In 2026 ABZ-1 issues received A-.ru from NKR (30.03.2026) and ruA- from Expert RA (April 2026) – the issues' rating rests on the guarantee of the parent company.
Management view (Anton Kulikov, BCS, broadcast of 01.09.2026). ABZ-1 works on government contracts, the project backlog covers two years, cash flow and profit are improving, leverage is low, and nothing bad is expected. The plant usually reports in the first week of September, the group by the end of September; the first half is seasonally weak.
Authors' assumption. There is no consolidated IFRS for the group in our database, and the ACRA release on it is almost three years old. We cannot verify either the current contract backlog or the group's debt. All that is visible from the plant's public data is that money from the market is moving up the group, and the quality of those loans determines the quality of the bonds.
How it gets paid: RUB 6.2bn over the next 12 months, of which RUB 3.4bn is amortisation, and all of it is group money
Fact. According to the MOEX schedule, from September 2026 to August 2027 ABZ-1 must pay about RUB 2.8bn of coupons and RUB 3.4bn of amortisation (including the new 002P-07). In September 2026 1R05 is redeemed (RUB 350mn outstanding) and an amortisation payment falls due; after that issues 2R01-2R07 amortise in equal instalments: peaks of RUB 0.5-0.6bn in May, July, August, September and November 2027, and in 2028 RUB 1.2bn each in January, April and July. None of the issues has a put offer. The new 002P-07: RUB 1bn, 17.75% monthly coupon, amortising, maturing 17.08.2029; the issue was rated ruA- and A-.ru on 02.09.2026, and trades in the secondary market at 99.5% and 19.5% to maturity.
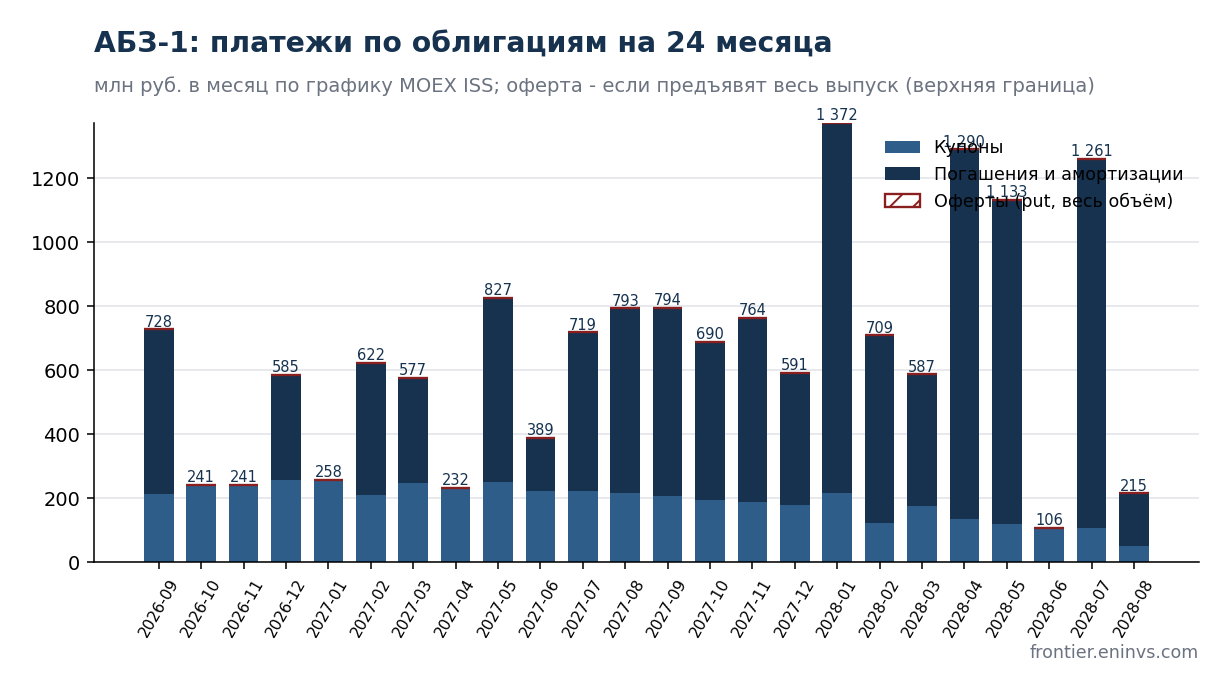
Authors' estimate. A plant with RUB 2bn of EBITDA a year cannot carry such payments, and it is not supposed to: amortisation is returned from the same loans issued to the group. So the key question for the group's half-year accounts is whether the operating cash flow of the road business covers RUB 6bn of bond payments a year plus bank loans. A fresh touch on the same point: on 27.08.2026 the plant gave a guarantee to Sberbank for Ekodor JSC of the same group – group obligations hang on the issuer through the bank line as well, not only through loans. For now the market answers "yes": all eight issues trade between 99% and 108% of par.
Market: 19.5% on the fixed-coupon issues and a 400-500 bp spread – the price of A- risk, not of high yield
Fact. The fixed-coupon issues 2R03 (25.5%, May 2028), 2R04 (19.5%, October 2028), 2R06 (17.5%, April 2029) and 2R07 (17.75%, August 2029) yield 18.4-19.7% to maturity at a spread of 400-505 bp over OFZ. The floaters 2R01, 2R02 and 2R05 yield 19.3-20.1% by MOEX. The shortest, 1R05, is redeemed on 30.09.2026.
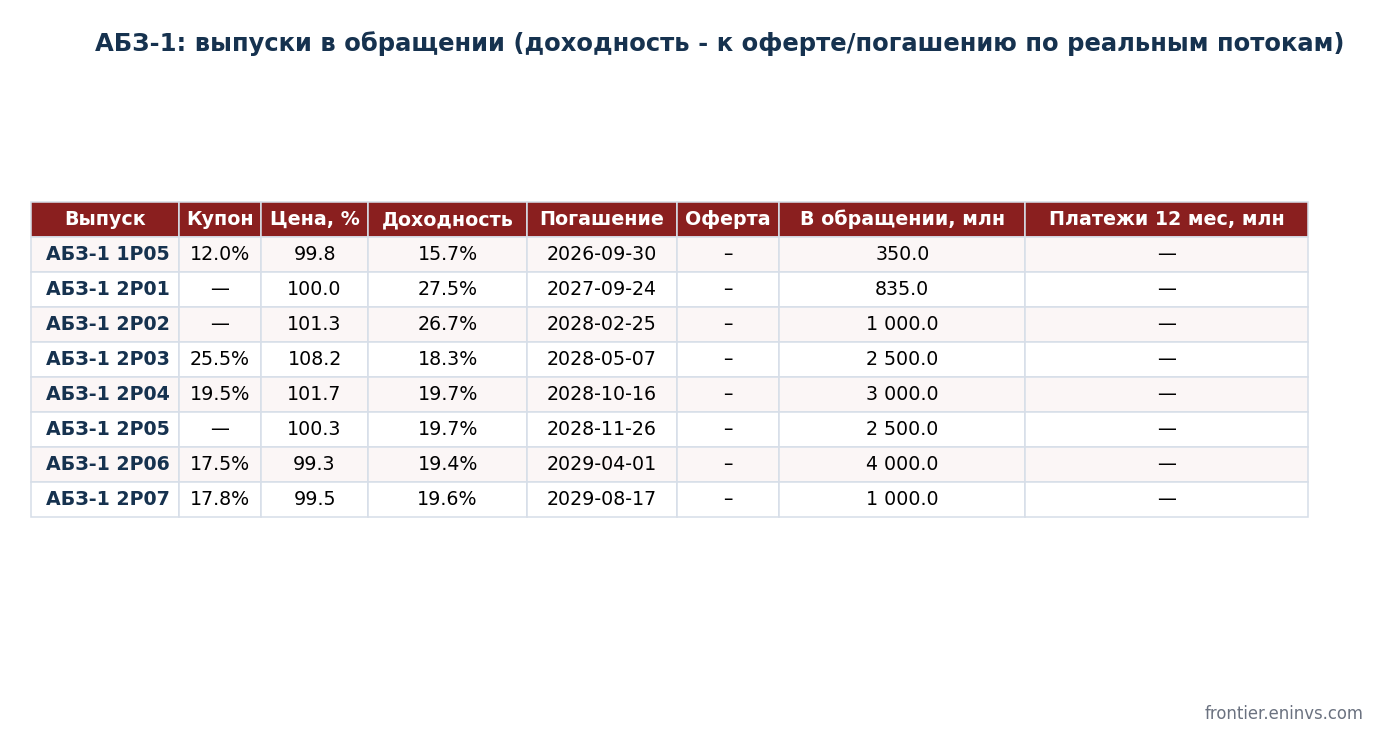
Authors' estimate. A spread of 400-500 bp matches the A-/BBB+ rating basket in our sample and leaves no cushion for a surprise in the group's accounts. The idea here is not yield but stability: the long fixed issues 2R06 and 2R07 are a bet on a lower key rate with the credit of a government-contract road contractor.
Risks: group opacity, seasonality and a single customer – the state
- Group reporting. Only the plant's IFRS is publicly visible. The Baltic Project consolidation comes out twice a year and with a delay, and we are not aware of a fresh rating release on the group.
- Government orders and advances. Revenue depends on regional budgets and Rosavtodor; advances and retentions on contracts move cash flow by quarters; in 1H2026 the plant's revenue is down 13%.
- Concession. The tram concession in St Petersburg is a 30-year project with capex that may require group cash earlier than bond amortisation does.
- Intragroup loans and guarantees. The quality of the RUB 13bn passed up the group is the main credit fact, and it cannot be checked from outside; the guarantee for Ekodor to Sberbank (27.08.2026) adds contingent liabilities.
Conclusion: acceptable risk for the conservative part of a high-yield portfolio, but buy it as the group, not as the plant
ABZ-1 is a convenient instrument for getting 19-20% on the credit of a government-contract road contractor, and Kulikov places it in the reliable part of his ideas alongside Borets and VIS Finance. Our view is more cautious: the plant's figures say nothing about credit by themselves, they speak about the group, and there is little public data on the group. It is sensible to wait for the group's half-year accounts at the end of September and keep the position within the usual limit for a single second-tier issuer.
Sources and caveats
- Consolidated IFRS of ABZ-1 JSC for 2021-2025 and 1H2026 (e-disclosure), half-years as in the issuer's disclosure.
- ACRA press release on PSF Baltic Project JSC of 29.11.2023; NKR (30.03.2026) and Expert RA (April 2026) notices on issue ratings.
- Schedule of coupons and amortisation – MOEX ISS; quotes – MOEX close on 03.09.2026; issuer notices on the placement of 002P-07, the issue ratings (02.09.2026) and the guarantee (27.08.2026).
- BCS broadcast with Anton Kulikov of 01.09.2026 – the speaker's position is given with attribution.
Other issuer reviews and weekly analytics are in the Telegram channel Enhanced Investments @eninv; extended cards of all issuers are on the portal.
See also: market overview · valuation map · stock screeners