Anterra: coupon default of RUB 38.7mn caused by frozen accounts despite RUB 6.2bn of assets – the bonds at 13-15% of par trade as a claim on the hotel, not as debt
Anterra operates the Green Flow wellness hotel at Roza Khutor and develops new properties of the same chain. It has two bond issues totalling RUB 600mn (BO-02: RUB 250mn at 20%, BO-03: RUB 350mn at 30%) and a B-|ru| rating from NRA (12.12.2025). On 18 August the company failed to pay coupons of RUB 38.7mn, and on 2 September the technical default became a default: the bailiffs have frozen its accounts since 31 July on a contractor's claim, no agreement was reached by 31 August, and holders gained the right to demand early redemption at par. The bonds trade at 13-15% of par. Verdict: this is no longer credit analysis but recovery analysis – the business is operationally profitable, equity rose from RUB 0.87bn to 2.2bn in 1H2026 and assets to RUB 6.2bn, but cash is RUB 4mn against RUB 1.9bn of debt. Everything hinges on one court dispute and the owner's willingness to pay, and the market prices holders' chances at about a tenth of par.
The issuer card on the portal with financials by period, our credit analysis and all issues: Anterra. Below are Enhanced Investments' calculations based on the issuer's IFRS and RAS statements, the MOEX payment schedule and disclosures; where a figure is the authors' estimate, it is marked as such.
What the business is: a profitable hotel with a 20-40% margin that started building a second one with borrowed money
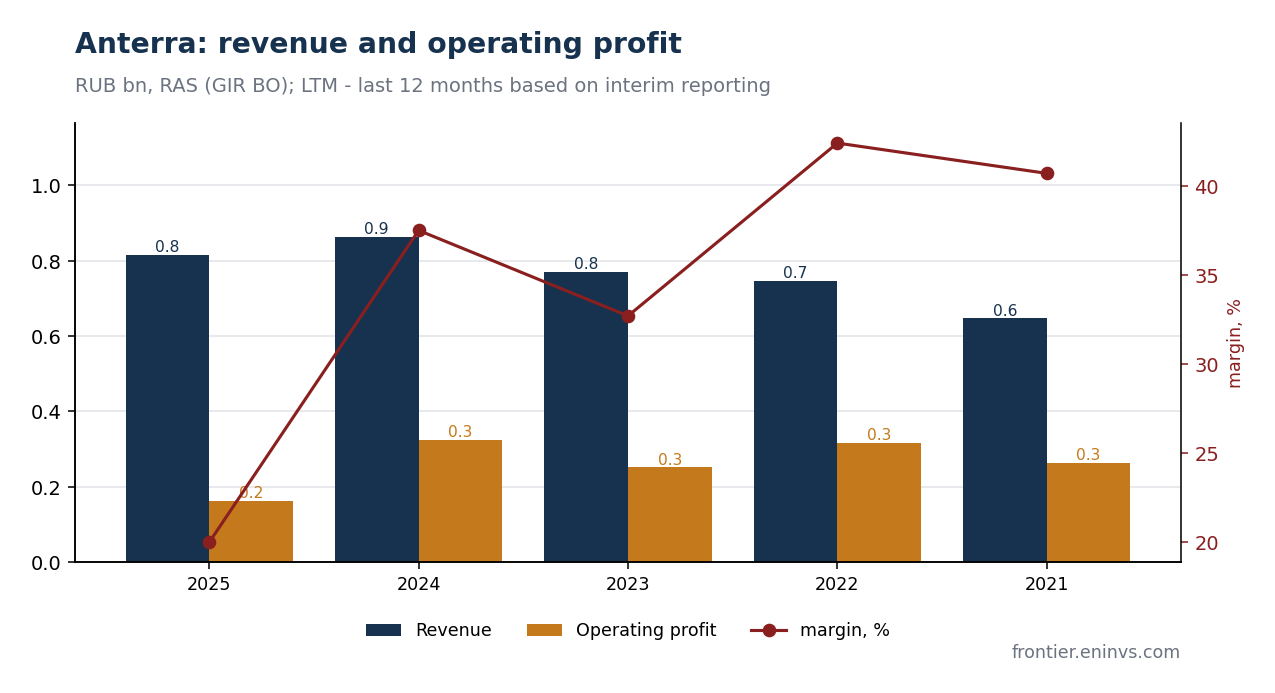
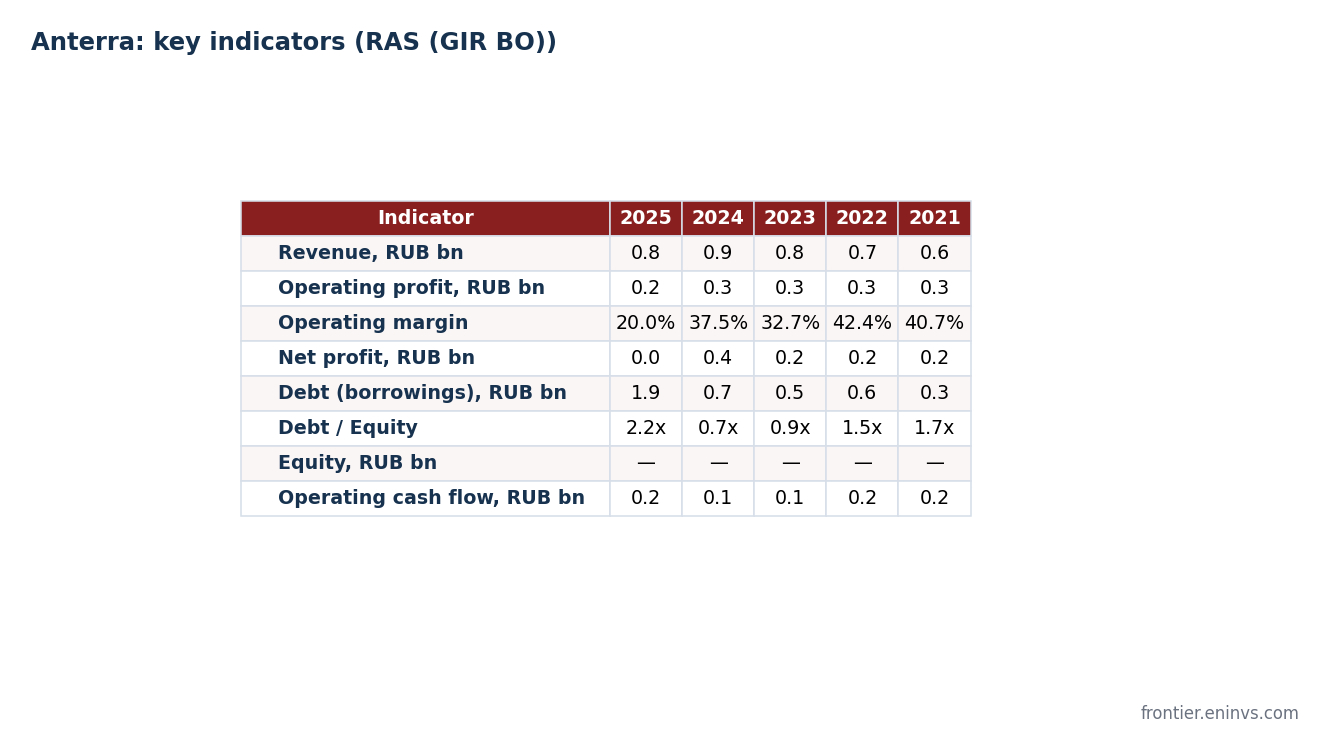
Fact (RAS). Revenue has been stable at RUB 0.75-0.86bn a year: RUB 0.86bn in 2024, RUB 0.82bn in 2025 (down 5%), RUB 0.40bn in 1H2026 (down 12%). Operating profit was RUB 0.25-0.32bn in 2021-2024 at a 33-42% margin, fell to RUB 0.16bn (20%) in 2025 and was RUB 0.10bn in 1H2026. Net profit was RUB 0.37bn in 2024 and about zero in 2025. Operating cash flow was positive in every year: RUB 0.12-0.19bn.
Fact. Borrowings rose from RUB 0.7bn at the end of 2024 to RUB 1.9bn at the end of 2025, and assets from RUB 4.4bn to RUB 6.2bn at 30.06.2026; equity rose from RUB 0.87bn to RUB 2.2bn in 2Q2026 – on the balance sheet this looks like an owner's contribution or a revaluation, and the interim RAS statements do not disclose the details. Cash on accounts is RUB 4-6mn.
Default: RUB 12.5mn on BO-02 and RUB 26.2mn on BO-03 unpaid since 18 August, accounts frozen since 31 July
Fact. The ninth coupon of BO-02 and the seventh coupon of BO-03 were due no later than 18.08.2026. According to the issuer, the reason was a lack of funds because its settlement accounts were frozen in a dispute with a contractor; the company expected the freeze to be lifted within 10 days and a court hearing in October. On 2 September the Moscow Exchange recorded a default: no agreement with the claimant had been reached and talks continue, while the company promises an anti-crisis strategy and a presentation by CEO Alexander Tertychny. The same day the issuer disclosed that holders of both issues gained the right to demand early redemption at 100% of par plus accrued interest (coupon overdue by more than 10 business days). As of the evening of 4 September there were no new announcements on lifting the freeze or an agreement with the claimant. In December 2025 NRA downgraded the rating to B-|ru|.
Authors' estimate. RUB 38.7mn is less than one month of the hotel's revenue and a quarter of its annual operating cash flow. The problem is not the ability to pay but access to the money: with accounts frozen, all receipts are blocked. So the outcome depends on the size of the contractor's claim (not disclosed) and on whether the owner lifts the freeze with its own funds. The RUB 1.3bn rise in equity in the second quarter suggests that the shareholder had the money.
How it can pay: RUB 392mn over 12 months, including RUB 250mn BO-02 redemption in May 2027, against RUB 6mn of cash
Fact. Quarterly coupons are RUB 39mn in November 2026, February and May 2027, then RUB 26mn in August and November 2027; BO-02 redemption of RUB 250mn is on 18.05.2027, BO-03 redemption of RUB 350mn on 16.11.2027. Coverage of annual payments in our screening is 0.41x, based on operating cash flow of RUB 157mn and almost zero cash.
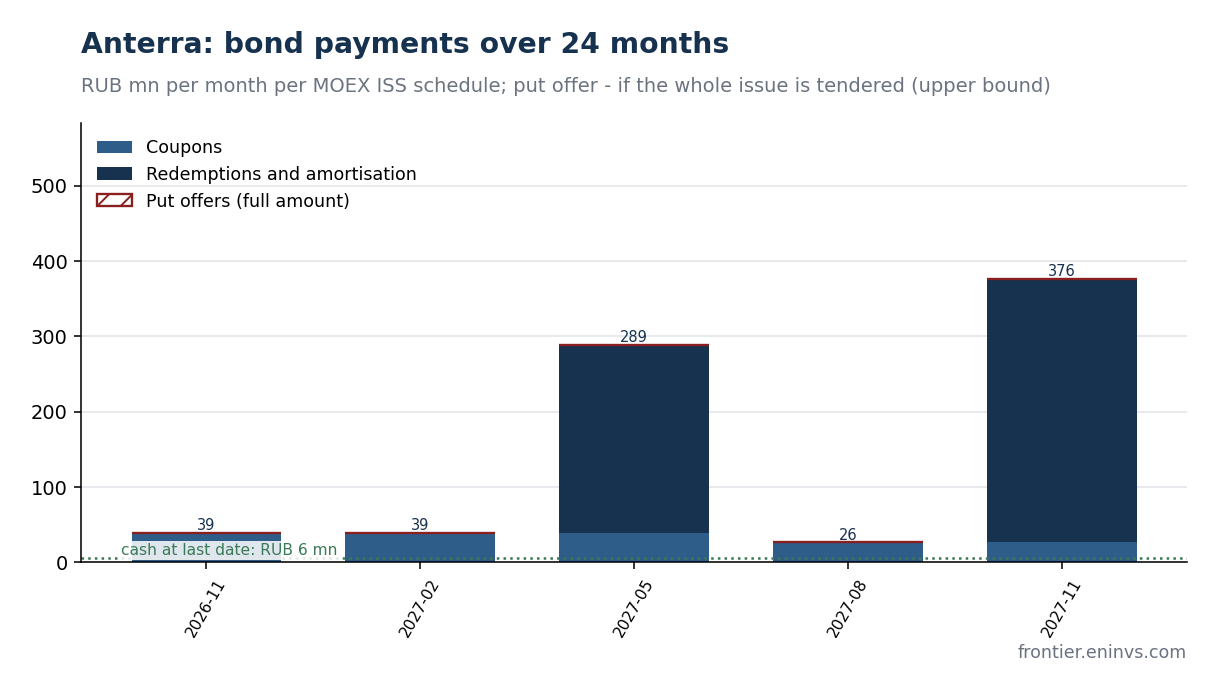
Authors' estimate. Even without the freeze, a hotel generating RUB 0.15-0.2bn a year cannot repay RUB 600mn in 2027 from operations; this was built into the model from the start – refinancing or a sale of the property. The coupon default shuts the market refinancing route, leaving the shareholder, a bank loan secured on real estate, or an asset sale. RUB 6.2bn of assets against RUB 1.9bn of borrowings gives a formal 3x coverage – if the real estate on the balance sheet is worth what is recorded.
Market: 11% of par is holders' estimate of recovery after the court case, not a yield
Fact. At the 3 September close BO-02 stood at 10.7% of par and BO-03 at 11.2% (these prices are on the chart below); by 17:30 Moscow time on 4 September they were at 15.3% and 13.0%. The rebound came on the back of coupon payments by another troubled issuer, L-Start, not on news from Anterra itself. Both issues are in coupon default, volumes are small and liquidity is minimal.
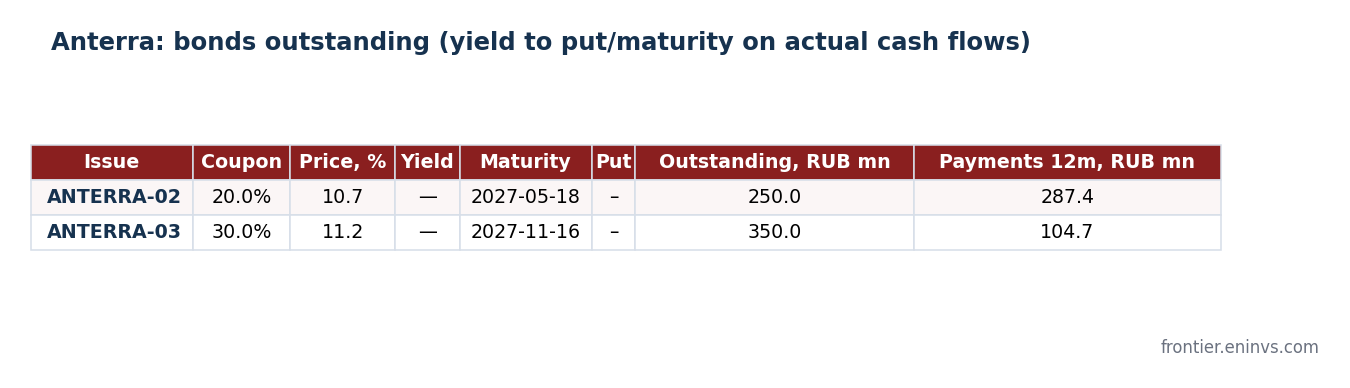
Authors' estimate. At 13-15% of par a holder buys a claim for RUB 1,000 plus an overdue coupon for RUB 130-150. If the freeze is lifted and coupons are paid, the price would return to 50-80%; if it comes to bankruptcy, bondholders are unsecured creditors in the third tier behind banks with a pledge over the hotel. Intermediate scenarios (a bondholders' meeting with an extension) are usually not available for issues of RUB 250-350mn from a small issuer: either they pay or they do not. We do not attempt to estimate the probability, because the size of the contractor's claim and the position of secured creditors are not disclosed.
Risks and what to watch
- Contractor's claim. The amount and subject are not disclosed; the first hearing is in October. Lifting the freeze is the only event that brings the bonds back to life.
- Early redemption. All holders have had the right to demand redemption at par since 02.09.2026; mass presentation with frozen accounts turns a coupon default into a default on principal and speeds the path to bankruptcy.
- Collateral. The RUB 1.9bn of borrowings are most likely bank loans secured on the hotel; the bonds are unsecured.
- Disclosure. Interim statements are published, but the structure of the new debt and of the second-quarter 2026 equity is not explained.
- Kulikov's rule. A B- rating, issues below RUB 1bn and RAS-only reporting – the bonds were screened out by all three filters long before the default.
Conclusion: only for professionals in distressed debt
Anterra is not a story about a bad business: the hotel earns money, cash flow is positive and the owner recapitalised the company in 2026. It is a story about how, for an issuer with RUB 5mn of cash, any external freeze of accounts turns into a default. Buying at 13-15% is a bet that the freeze is lifted and that the shareholder prefers to pay RUB 38.7mn rather than lose the hotel in bankruptcy. The bonds do not suit an ordinary high-yield portfolio; for those who trade distressed debt, the event to watch is the court hearing in October.
Sources and caveats
- RAS statements of OOO Anterra for 2021-2025 and interim for 2025-1H2026 (GIR BO of the Federal Tax Service, e-disclosure).
- Issuer's announcements on non-performance of obligations (18.08.2026, 02.09.2026) and on the right to early redemption (02.09.2026), Vedomosti and Smart-Lab publications on them, and the Moscow Exchange default flag.
- NRA, rating action of 12.12.2025 (B-|ru|).
- Coupon and redemption schedule – MOEX ISS; quotes – MOEX close on 03.09.2026 on the chart and last trades at 17:30 Moscow time on 04.09.2026 in the text.
Reviews of other issuers and weekly analytics are in the Telegram channel Enhanced Investments @eninv, and extended cards of all issuers are on the portal.
See also: market overview · valuation map · stock screeners