B2B-RTS (BTBR): a 15% dividend yield with the key rate at 14%. Upside +28%
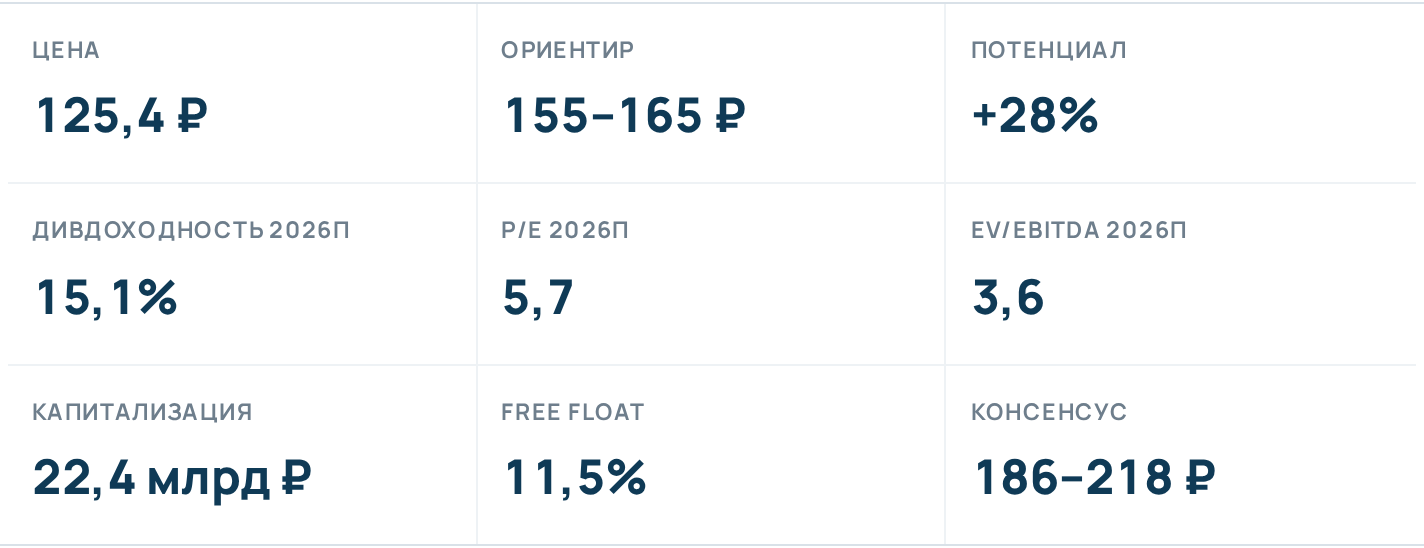
*Enhanced Investments · price RUB 125.36 as of 4 September 2026 · target RUB 155–165 · version 2 of 9 September*
In brief
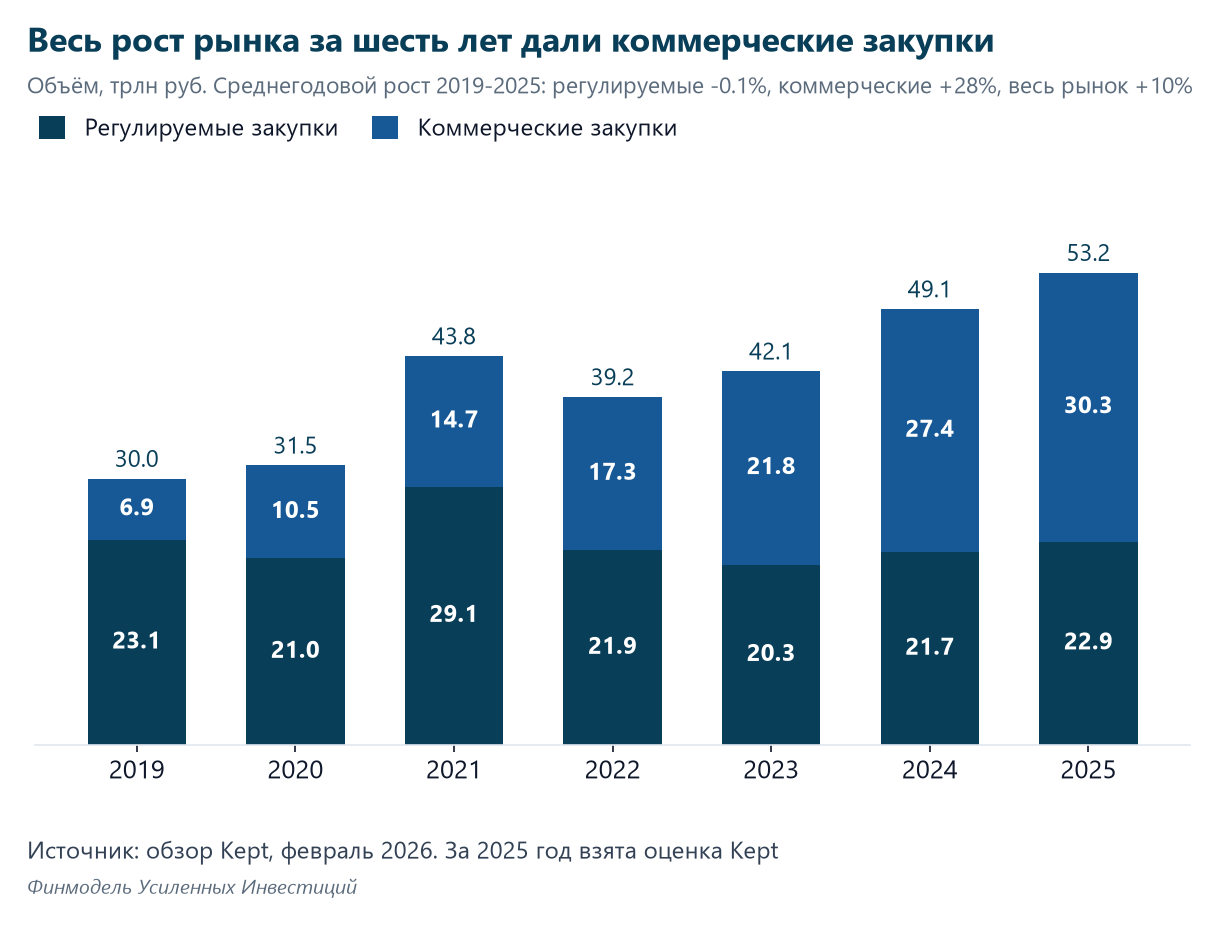
- The leader by number of procedures in all segments of electronic procurement. In 2025, RUB 9.7 trn, about 4.5% of GDP, went through its two platforms (RTS-tender and B2B-Center). Its share in the turnover of independent platforms rose from 25.4% to 26.1% without price dumping. The list of federal government-procurement operators has been closed since 2018, and the company is the only publicly listed one of the eight.
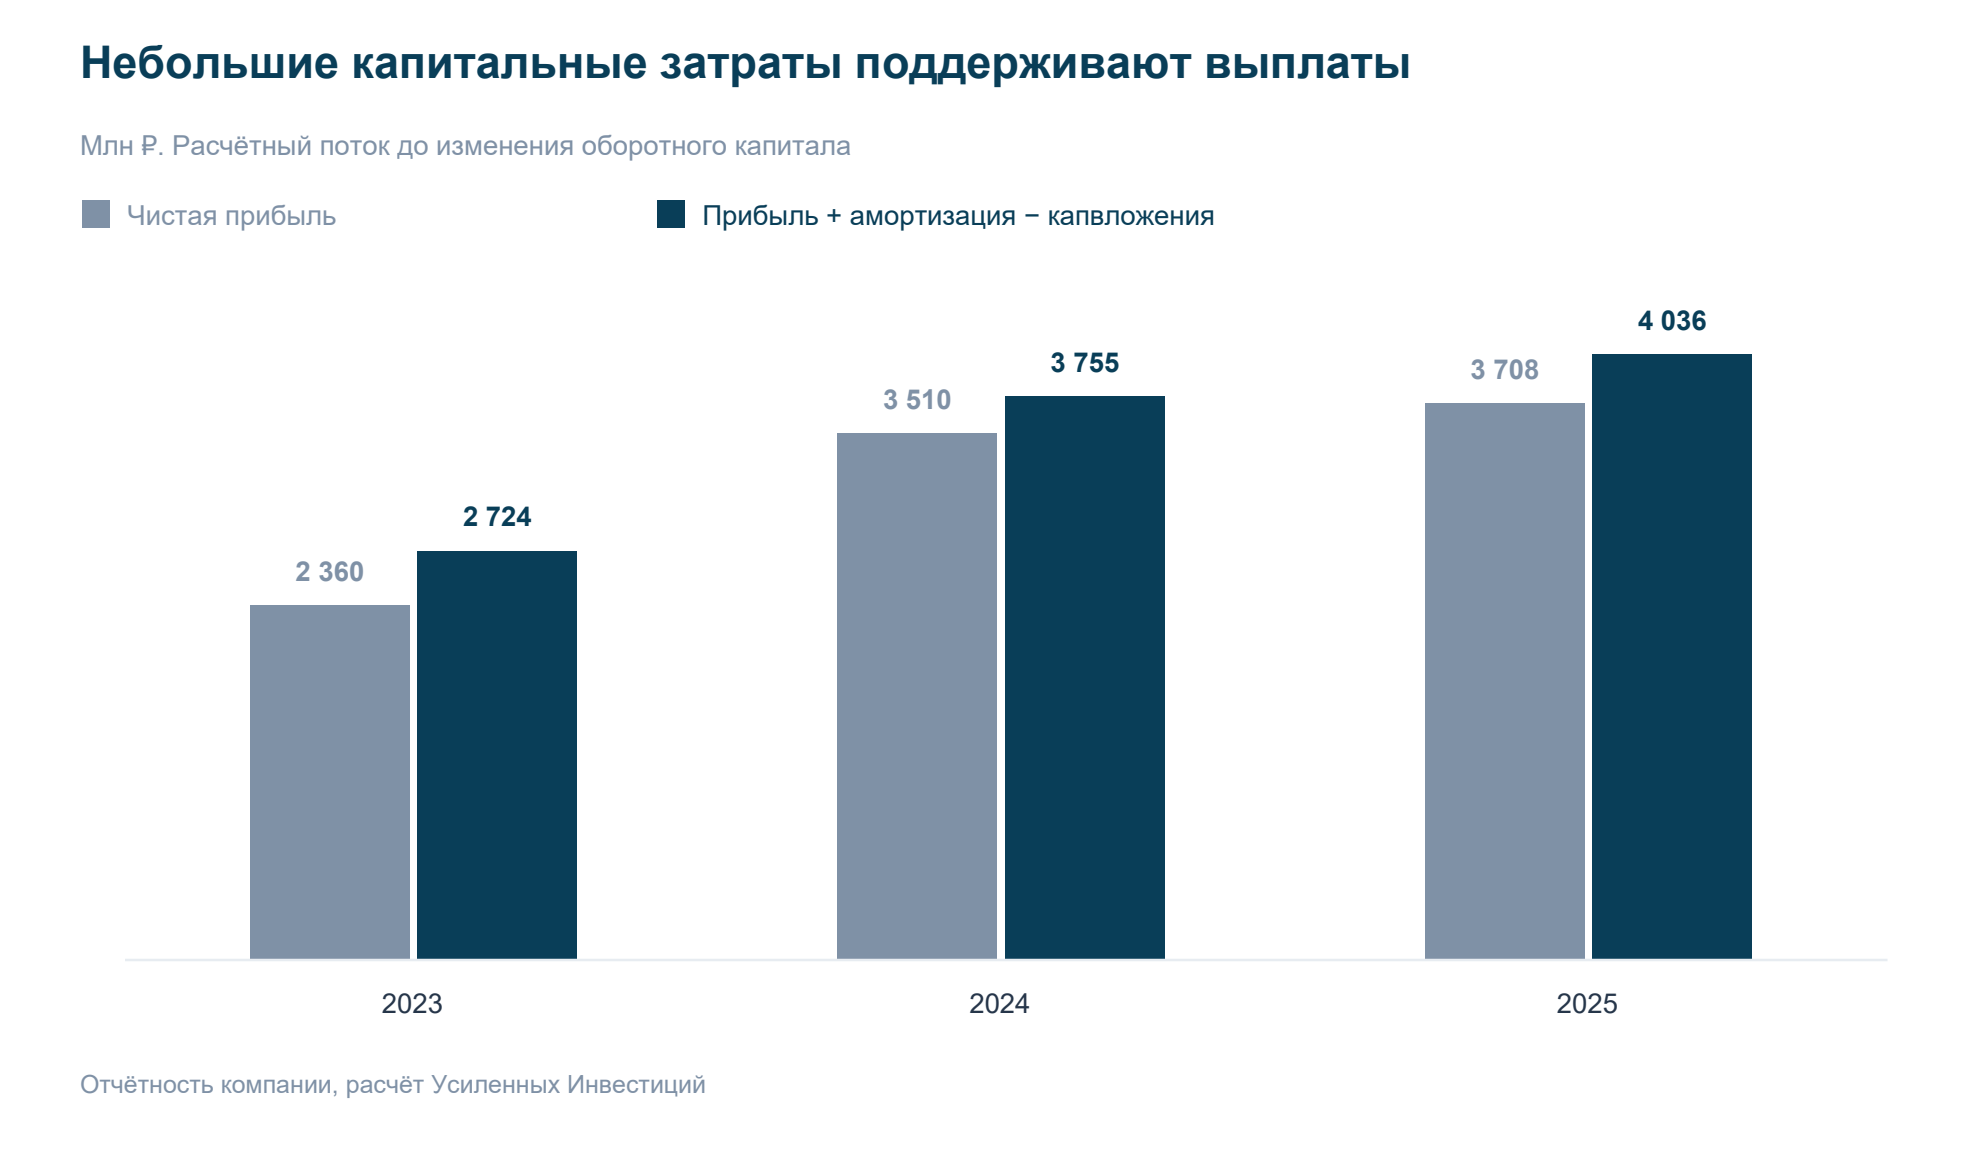
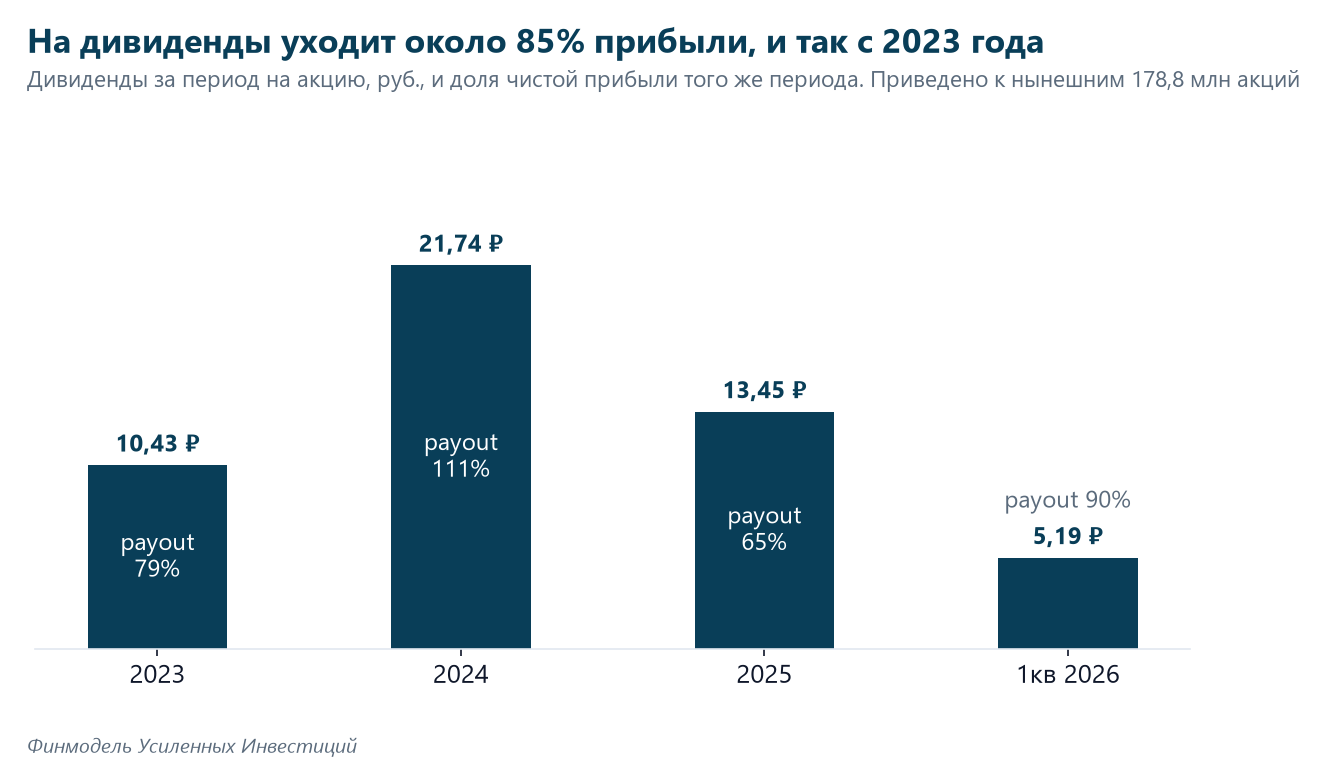
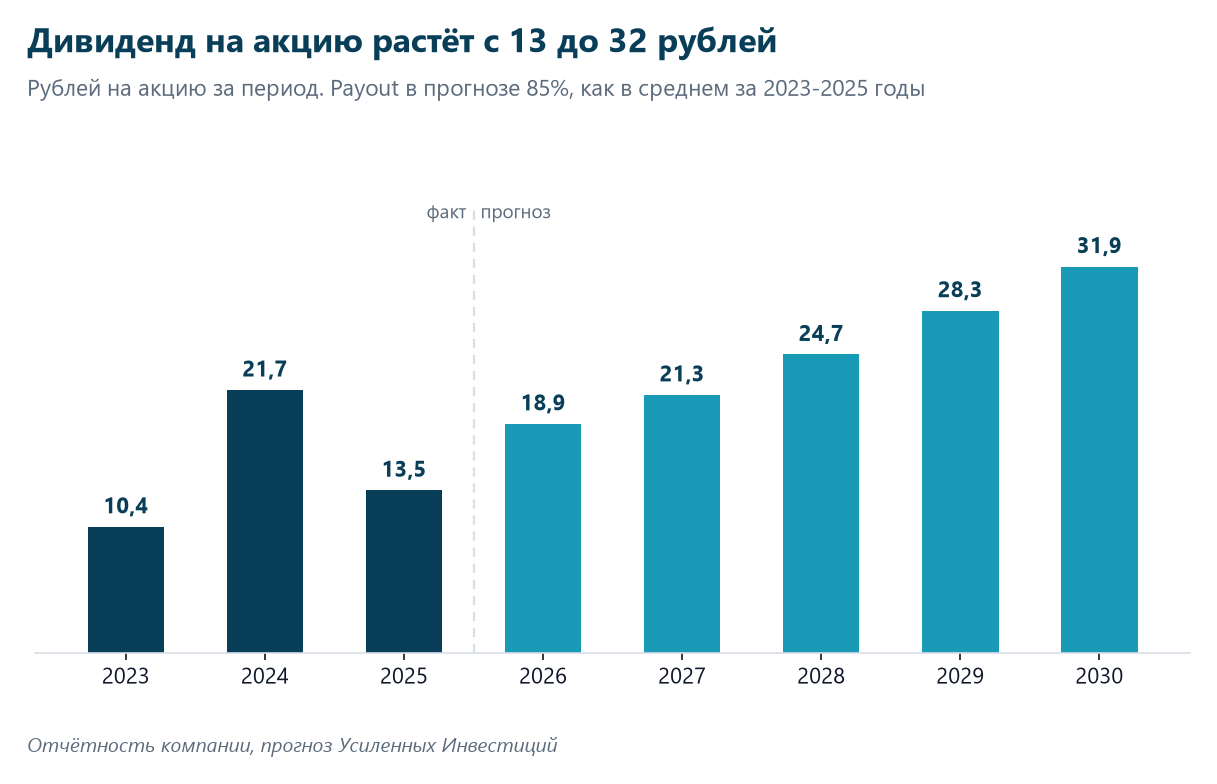
- A business with almost no capex and no debt, where all profit turns into cash. EBITDA margin of 51–54% three years in a row, estimated cash flow of 107–115% of profit, capex below 2% of revenue. Payout averages 85%, paid quarterly.
- Growth has accelerated: services +15% in 1H2026, 2Q +17.7%. The drivers are the new tariff model in commercial procurement (procedures +35% y/y in 2Q) and the tariff indexation in small-volume procurement (+44%). The company sets the tariff itself in both areas.
- Revenue does not depend on the rouble volume of procurement. The fee is charged to the winner and is capped (RUB 7.5 thousand under Law 44-FZ), so what pays is the number of procedures, not their value. In 1H2026 government procurement volume fell by 6.9%, while segment revenue rose by 3.9%.
- It trades like a bond and grows like an IT company. P/E of 5.7 and a 15% dividend yield for 2026E with the key rate at 14%. A discount of about 40–50% to HeadHunter and Cian on P/E and EV/EBITDA. The analyst consensus is RUB 186–218; our target is more conservative.
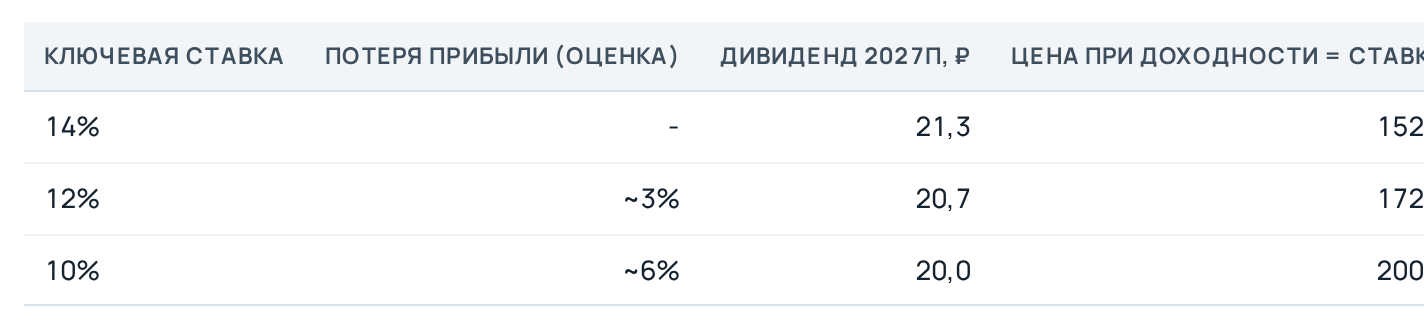
- A beneficiary of lower rates, despite the interest income. Each 1 pp of the key rate takes away about 1.5% of profit (interest on client funds), but it lowers the required yield of a quasi-bond share: at 12% the same 2027E payout is worth about RUB 172, at 10% about RUB 200.
- The main risk is the dividend policy, not the business. The formal minimum is 50% of profit, and a move to it costs about RUB 60 per share. Another 5% of revenue has already been cut by Law 577-FZ from 1 July 2026, which is a precedent that the regulator can change the rules quickly. The nearest pressure is the end of the lock-up in mid-October.
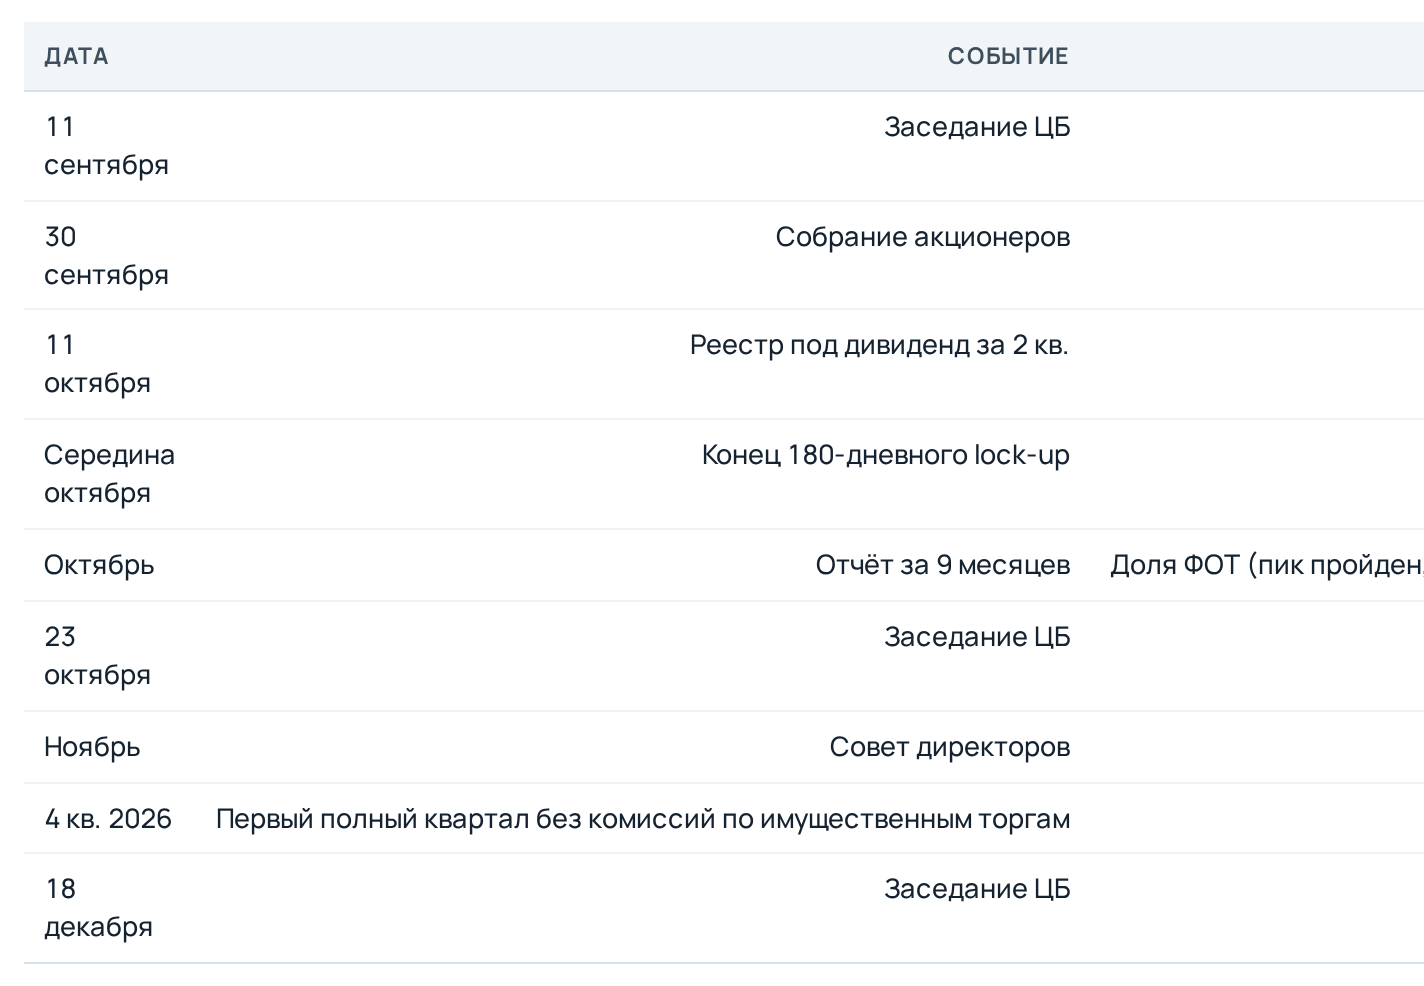
- Target RUB 155–165, 12-month total return of about 43% (28% price growth plus 15% dividends). The first test of the assumptions is the dividend meeting on 30 September and the 9M report.
1. What the business is, in a minute
- Two platforms: RTS-tender is one of the eight federal government-procurement platforms, B2B-Center is a commercial procurement platform. Plus e-shops for small-volume procurement (SVP), software for the procurement process (B2B Altis) and OTC digital products.
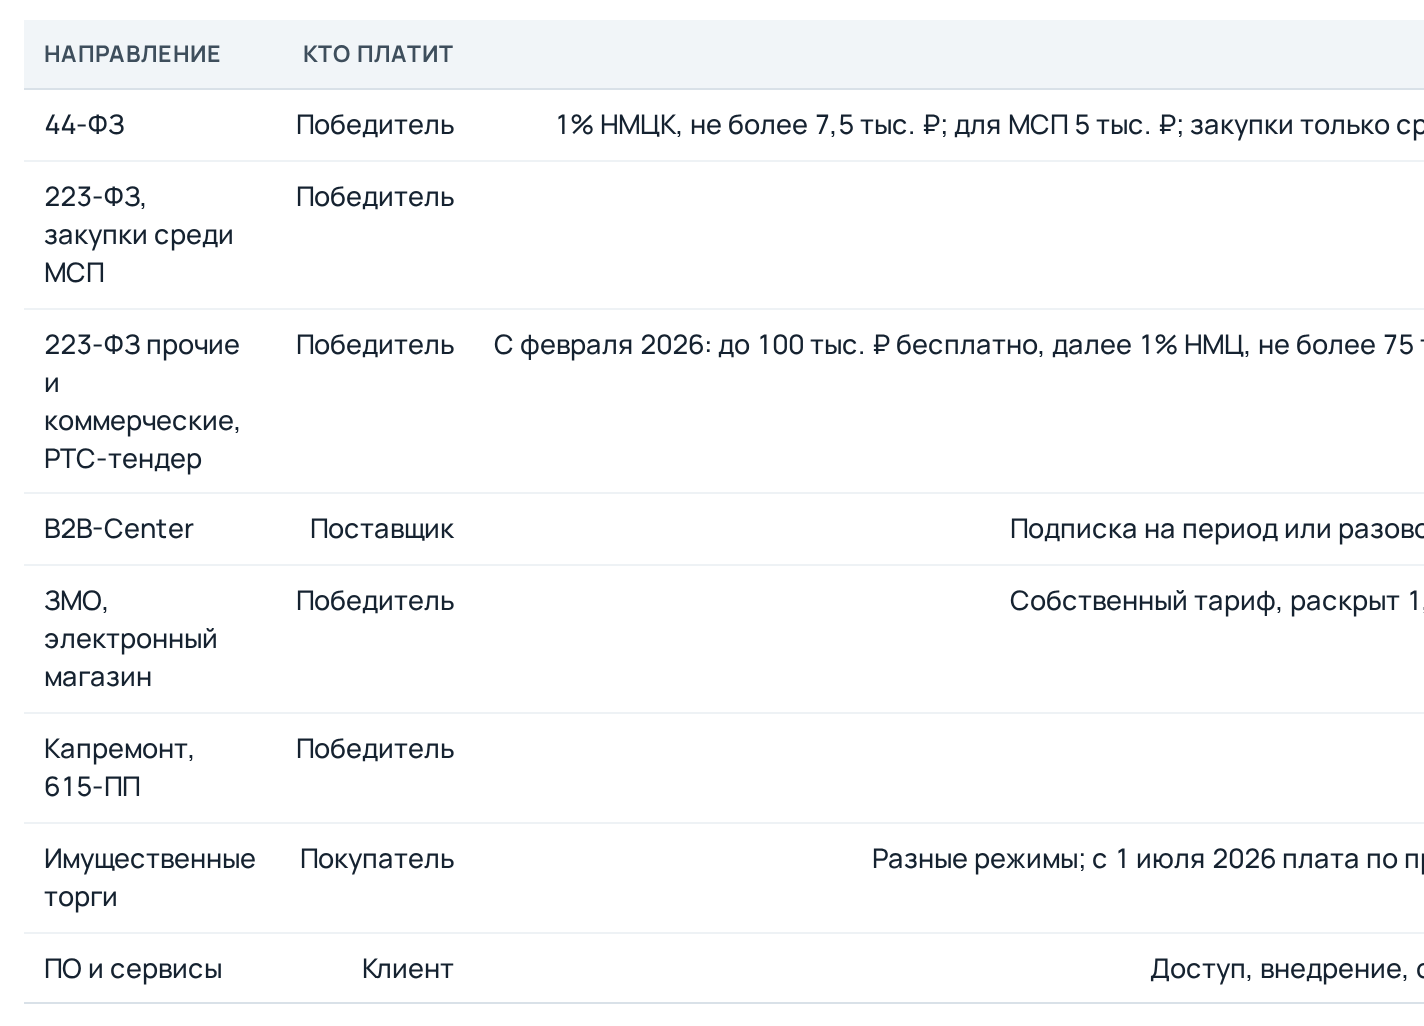
- The winner pays after the contract is signed: under 44-FZ 1% of the starting price but no more than RUB 7.5 thousand (RUB 5 thousand for SMEs); under 223-FZ for SME-only procurement 1%, no more than RUB 5 thousand; in other 223-FZ and commercial procurement on RTS-tender since February 2026 1%, no more than RUB 75 thousand, with lots up to RUB 100 thousand free. SVP has its own tariff (1.5% of the starting price), capital repairs 0.5% with a cap of RUB 14 thousand. B2B-Center works on subscription.
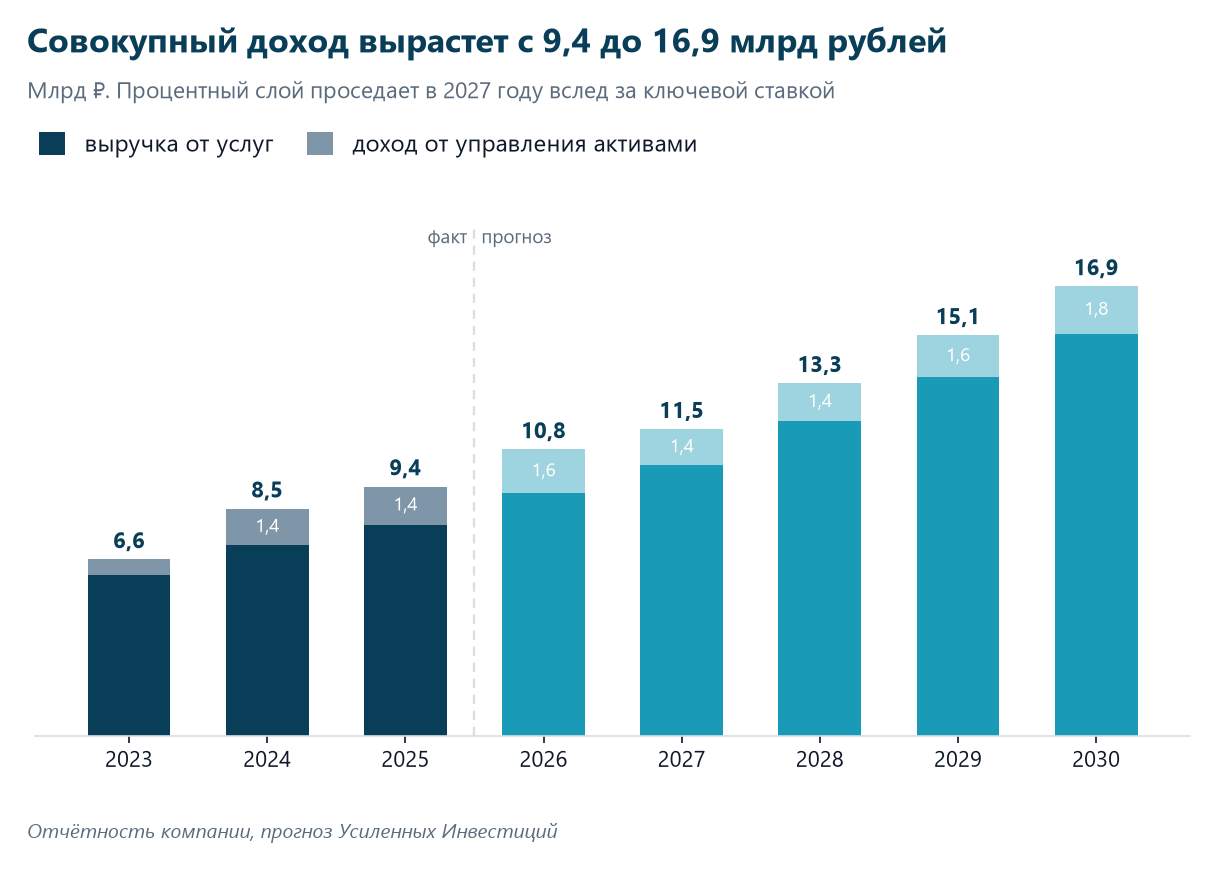
- The second source is interest on client funds (bid security, deposits and account balances): about 15% of total income. The money is held at Sovcombank, the controlling shareholder.
- Platforms compete for the customer, not for the supplier: the supplier is accredited on all eight at once, and the customer chooses the platform. What holds the customer is integration with accounting systems and trained staff, not price.
- IPO on 17 April 2026 at RUB 118, free float 11.5%. Since the placement the share has gained 6% excluding dividends. The lock-up declared at the IPO for the company, the selling shareholders and management is 180 days, that is, until mid-October.
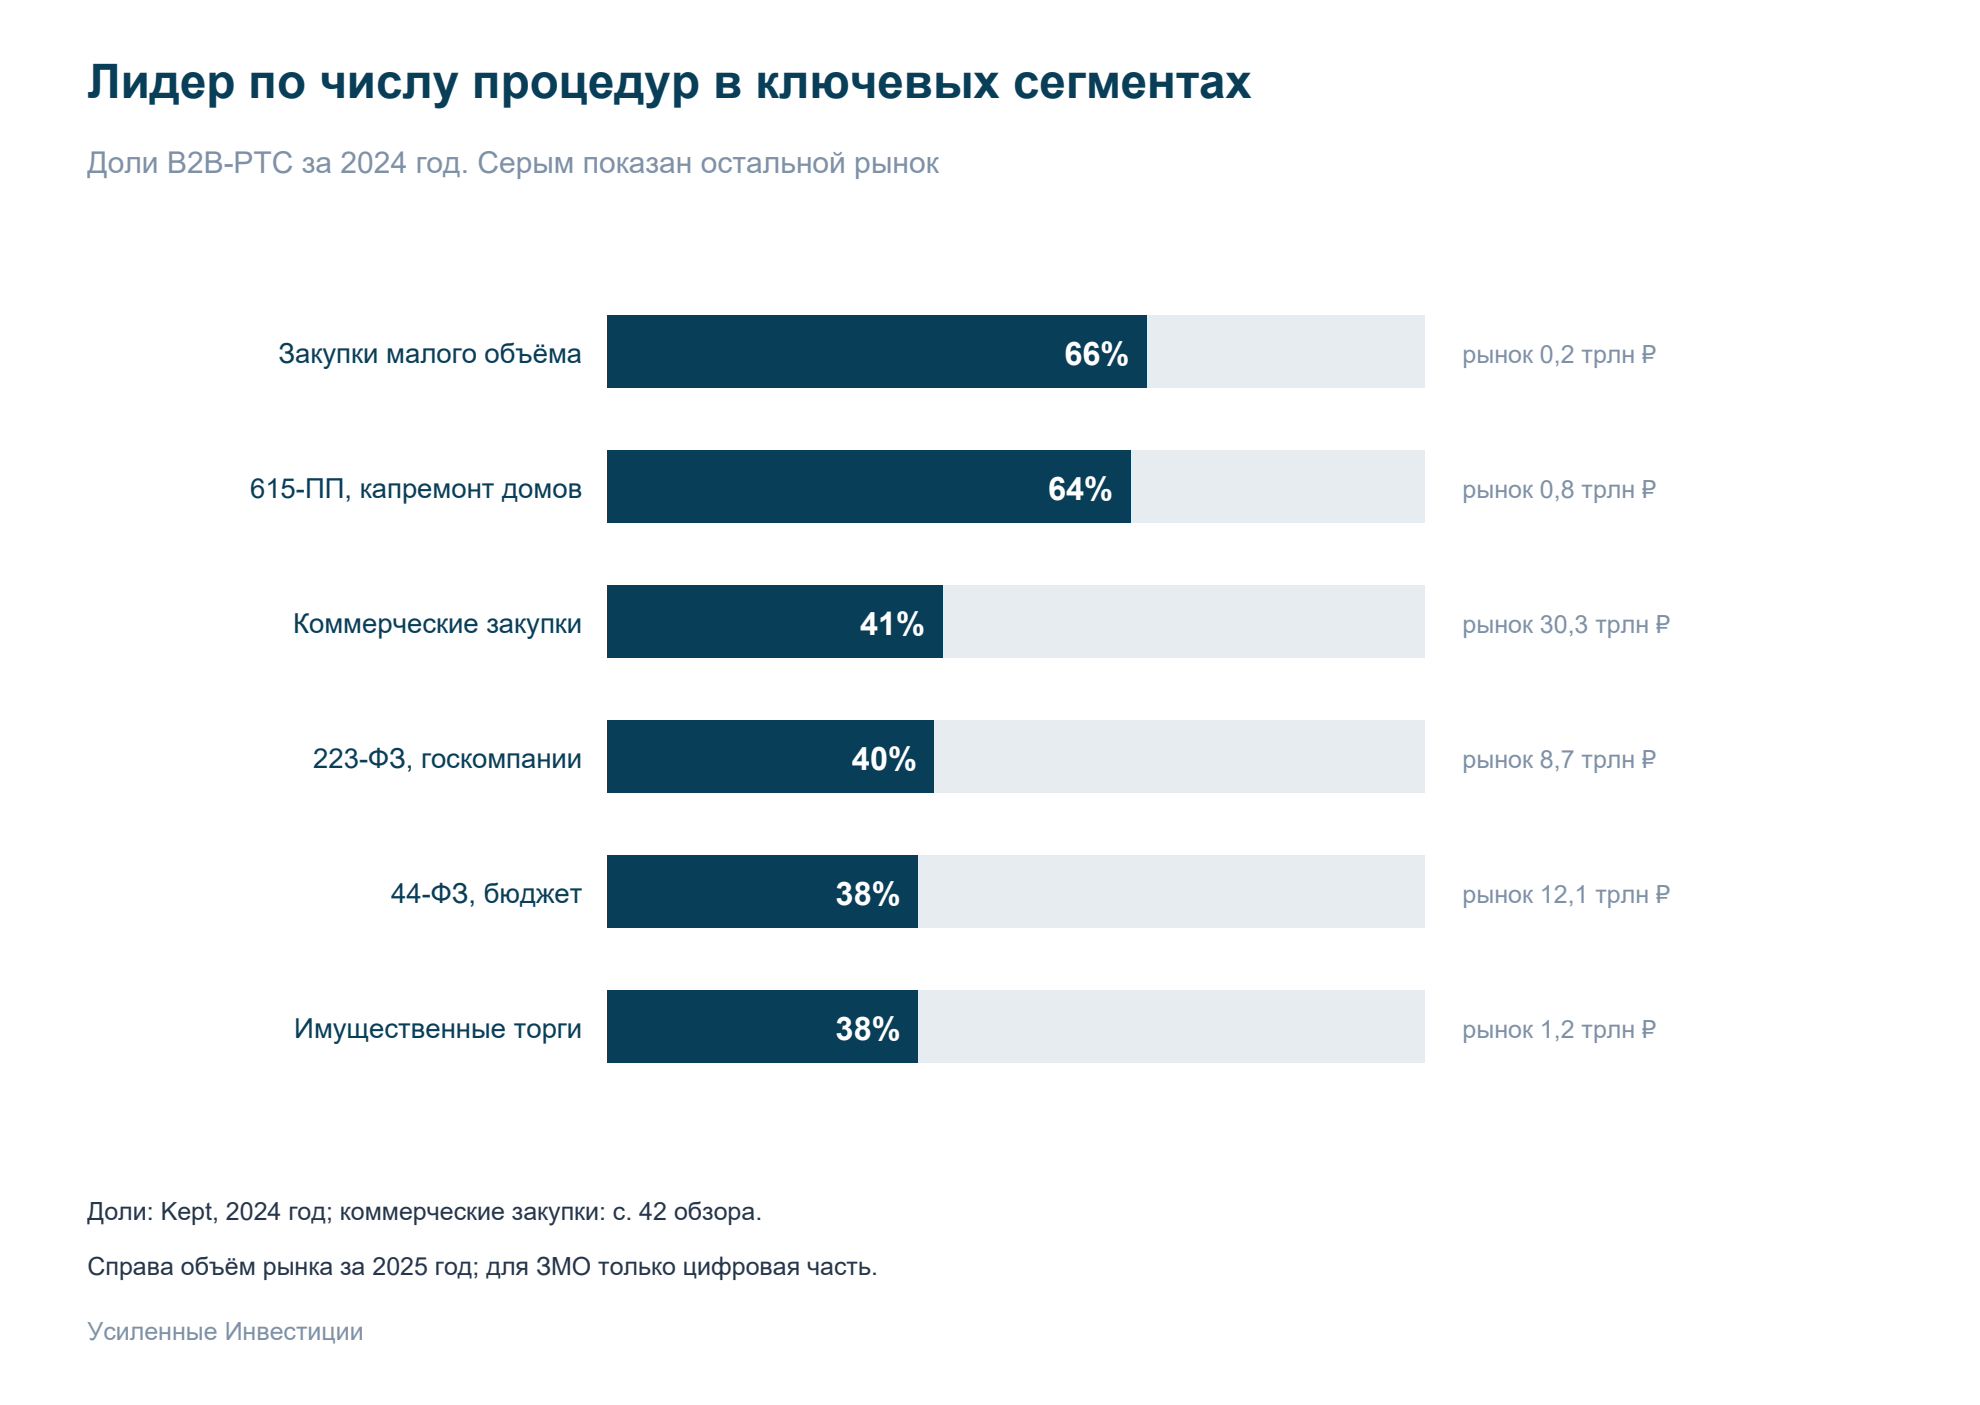
Half of revenue from services is under a regulated tariff, half under the company's own. 44-FZ, 223-FZ and capital repairs (RUB 4.0 bn, 50%): the rate is set by the state or by competition within the regulatory framework, and no increase is in the forecast. Commercial procurement, SVP and services (RUB 3.6 bn, 45%): the tariff is the company's own, and the lever has already been tested: the SVP indexation from 1 February 2026 gave +44%. Property auctions (RUB 392 mn, 5%): fees for privatization, leasing of public property and land auctions have been prohibited since 1 July 2026; bankruptcy auctions and seized-property sales were not covered by the ban.
2. Why it is growing: three drivers
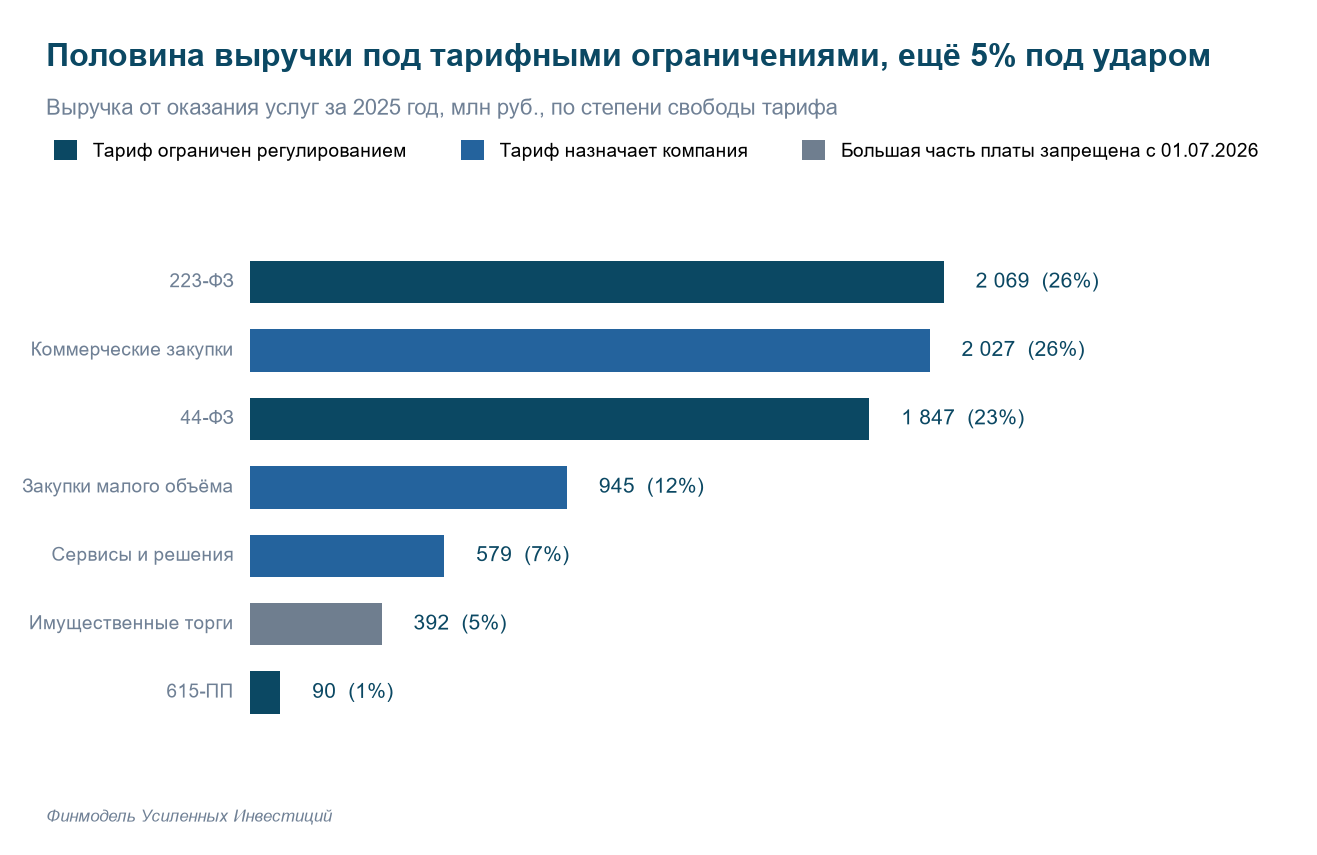
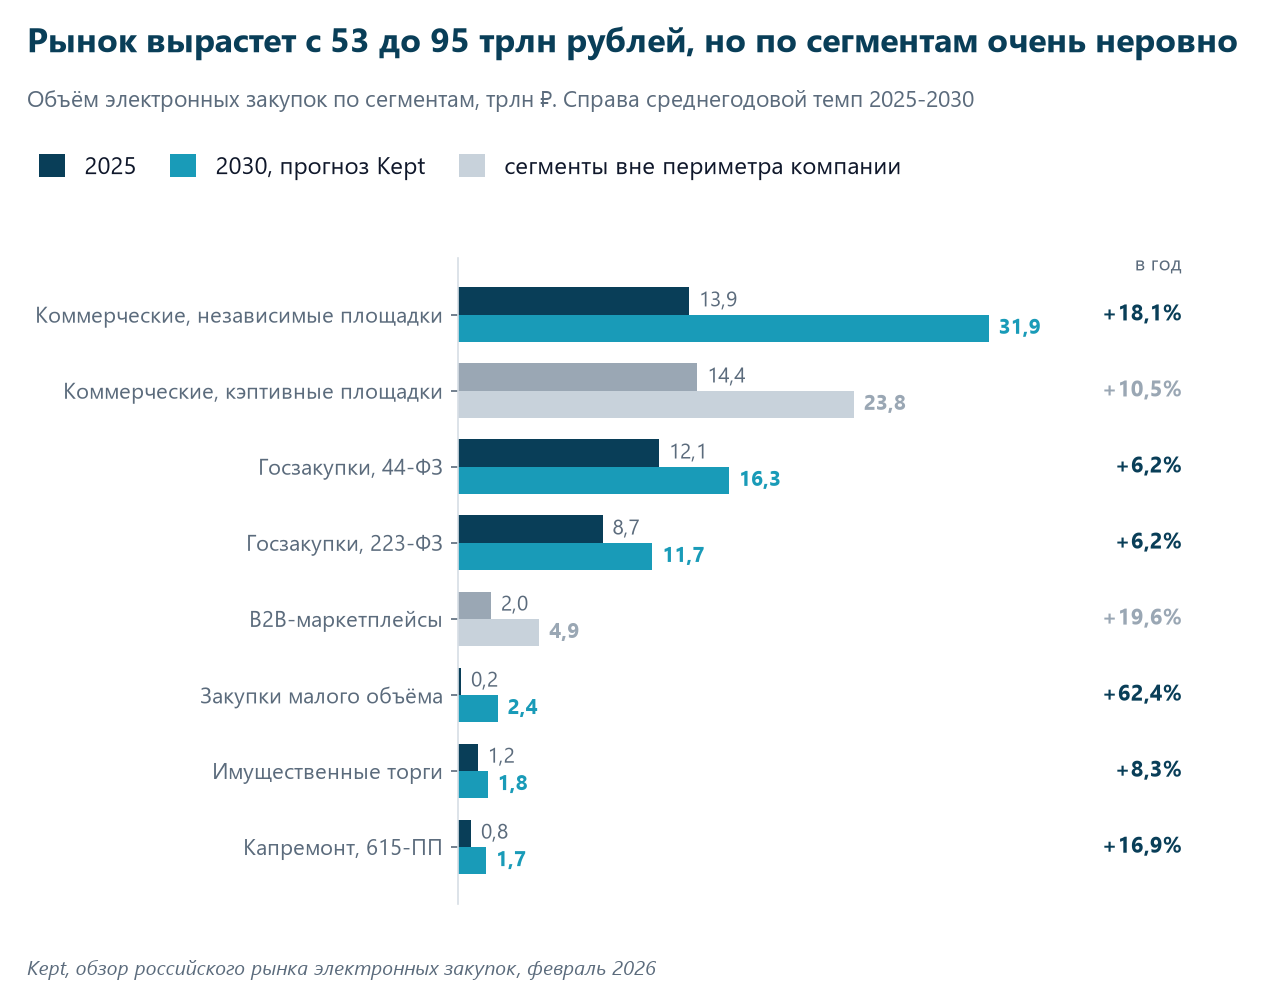
Driver 1. Commercial procurement is the only growing segment of the market. In 2019–2025 regulated procurement stood still (RUB 23.1 trn to 22.9 trn, minus 0.1% a year, almost halved in real terms), while commercial procurement grew 4.4 times (RUB 6.9 trn to 30.3 trn, +28% a year). The commercial share of the market went from 23% to 57%. The part available to the company (independent platforms, excluding captive ones) is growing at 19% a year and is not losing share.
Driver 2. The change of tariff model from 1 February 2026 removed the entry barrier for suppliers. Instead of an advance subscription fee, 1% from the winner (cap RUB 75 thousand), with lots up to RUB 100 thousand free. The result: commercial procurement procedures +24% for the half-year and +35% in the second quarter, segment revenue +22%. The gap between procedures and revenue is a lag: the fee arrives after the contract is signed, and part of the procedures already held is not yet reflected in revenue. The acceleration will continue in 2H2026 mechanically.
Driver 3. Small-volume procurement is a market where the company holds 66% and sets the price itself. E-shop data from the Ministry of Finance for 1H2026: number of purchases +49% (from 99.7 to 148.9 thousand), amount +47% (from RUB 38.3 bn to 56.2 bn), growth of about 50% for the second year in a row. The company's SVP revenue is +44% to RUB 645 mn for the half-year. The ratio of revenue to turnover here is about 0.7% against about 0.07% for the other procedures, which is ten times more monetizable. Resolution No. 590 from 1 July 2026 widens the digital footprint of SVP, but there is no mandatory move to the platforms, so this is not built into the forecast and is an option.
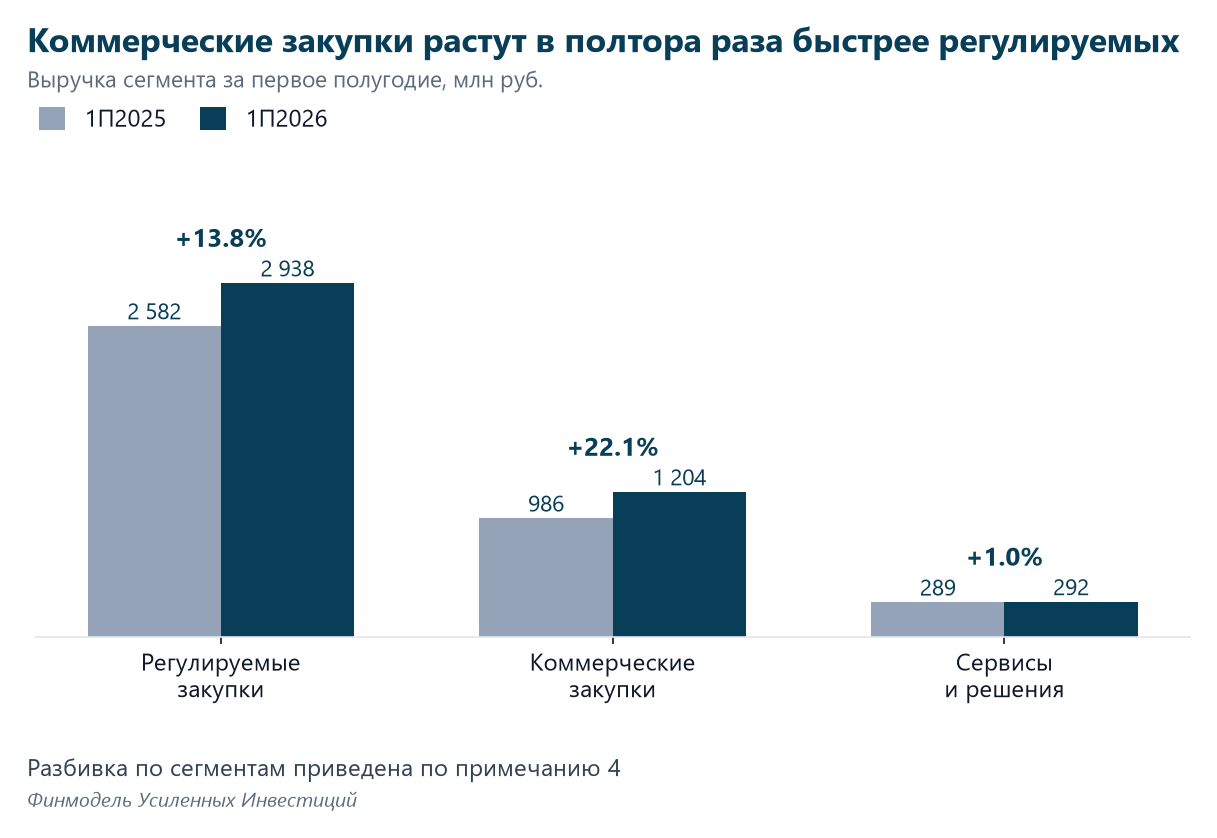
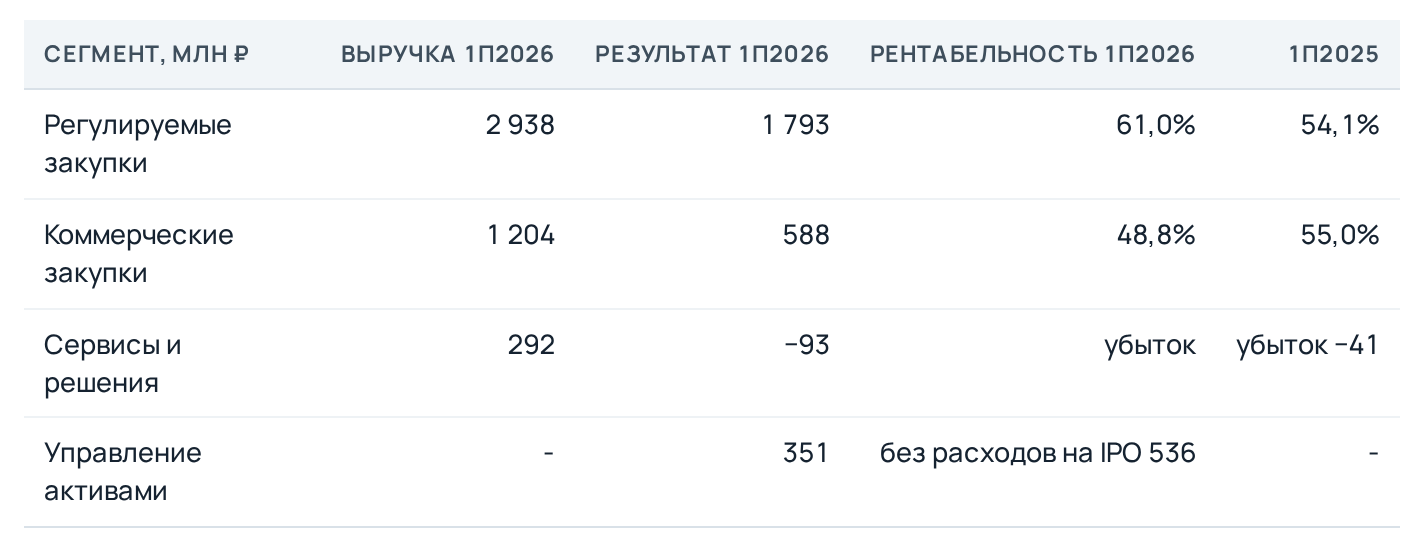
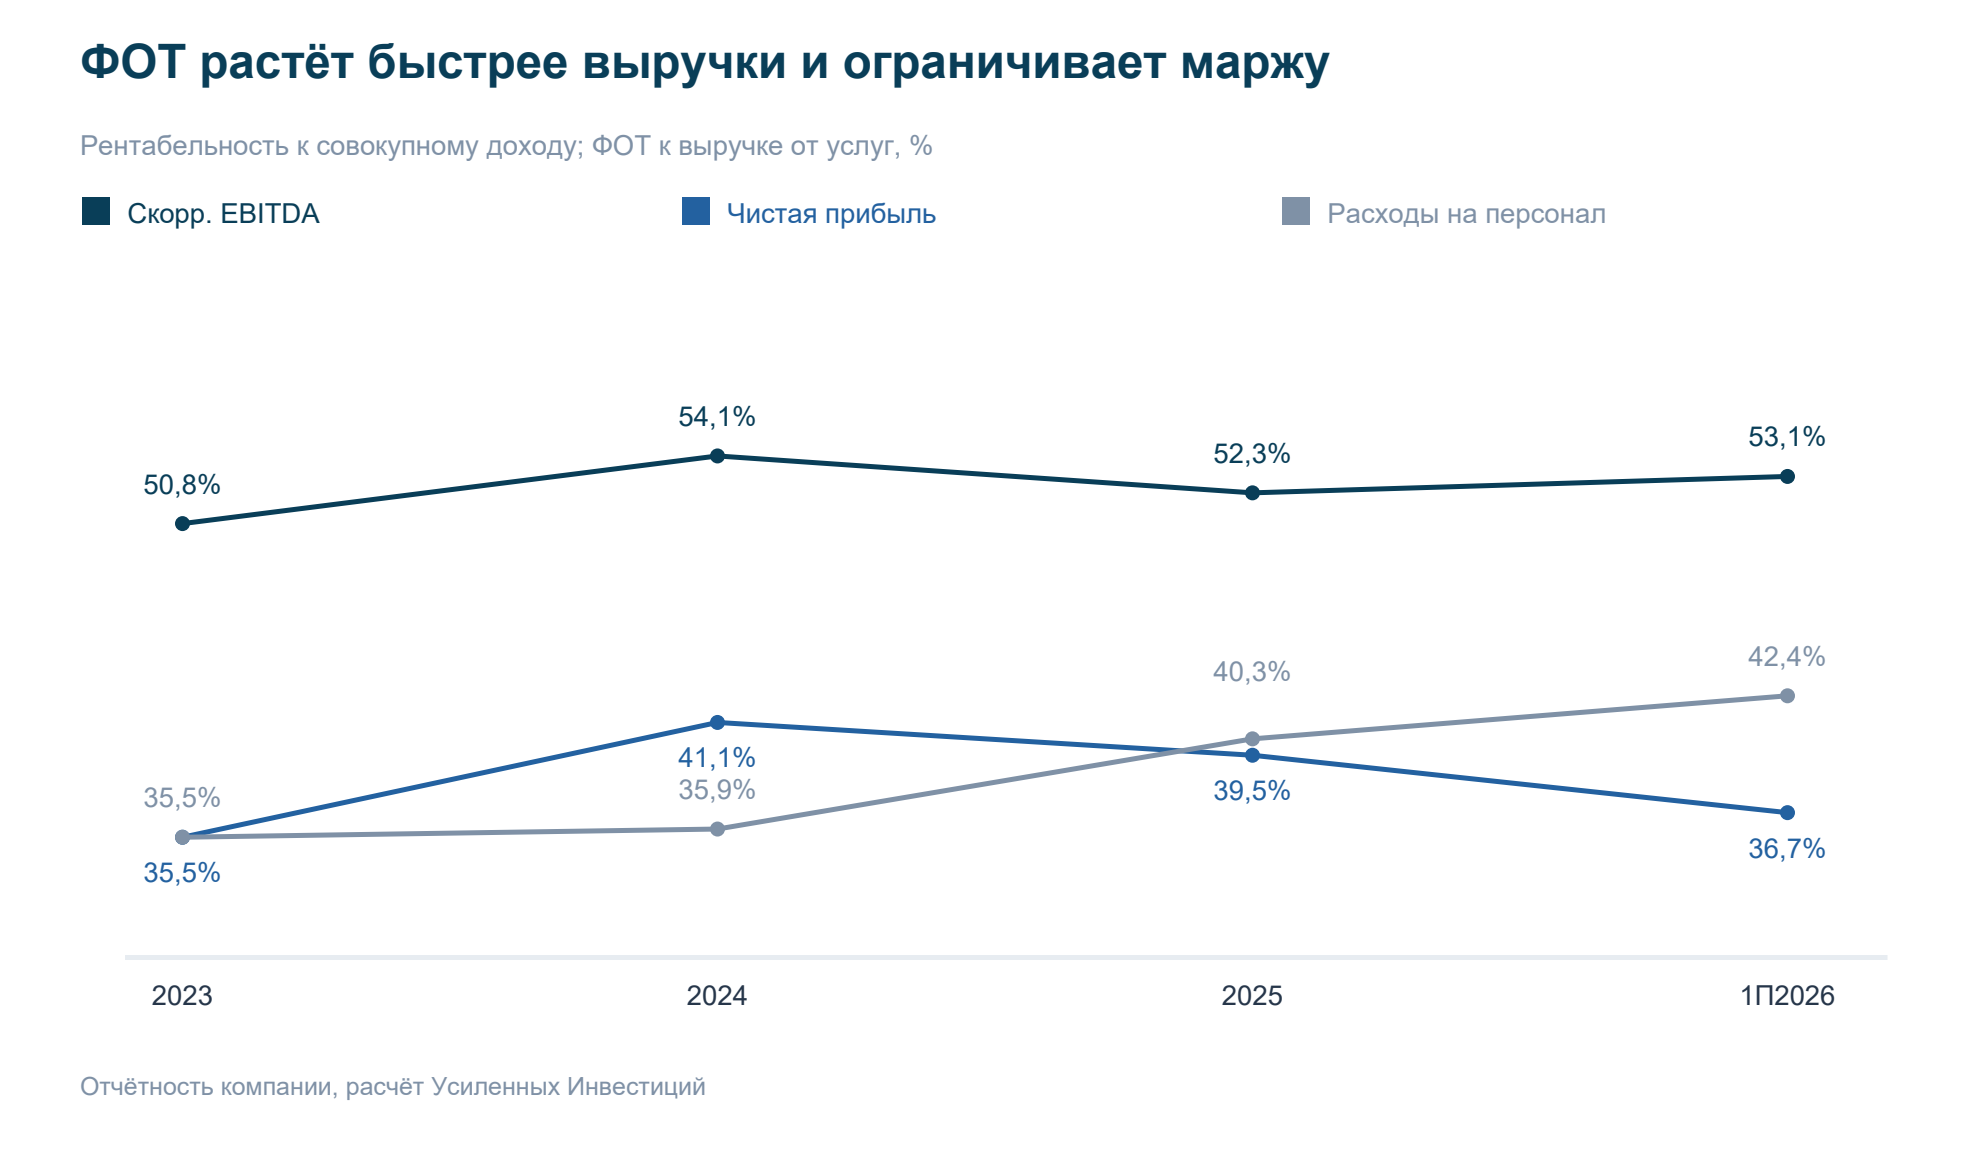
The lever on all of this is operating. Costs are almost entirely fixed: 62% is people. In 1H2026 revenue from services rose 15% and EBITDA 18%, even in a year when insurance contributions for IT companies rose from 7.6% to 15%.
3. Financials: there is growth, but its quality varies
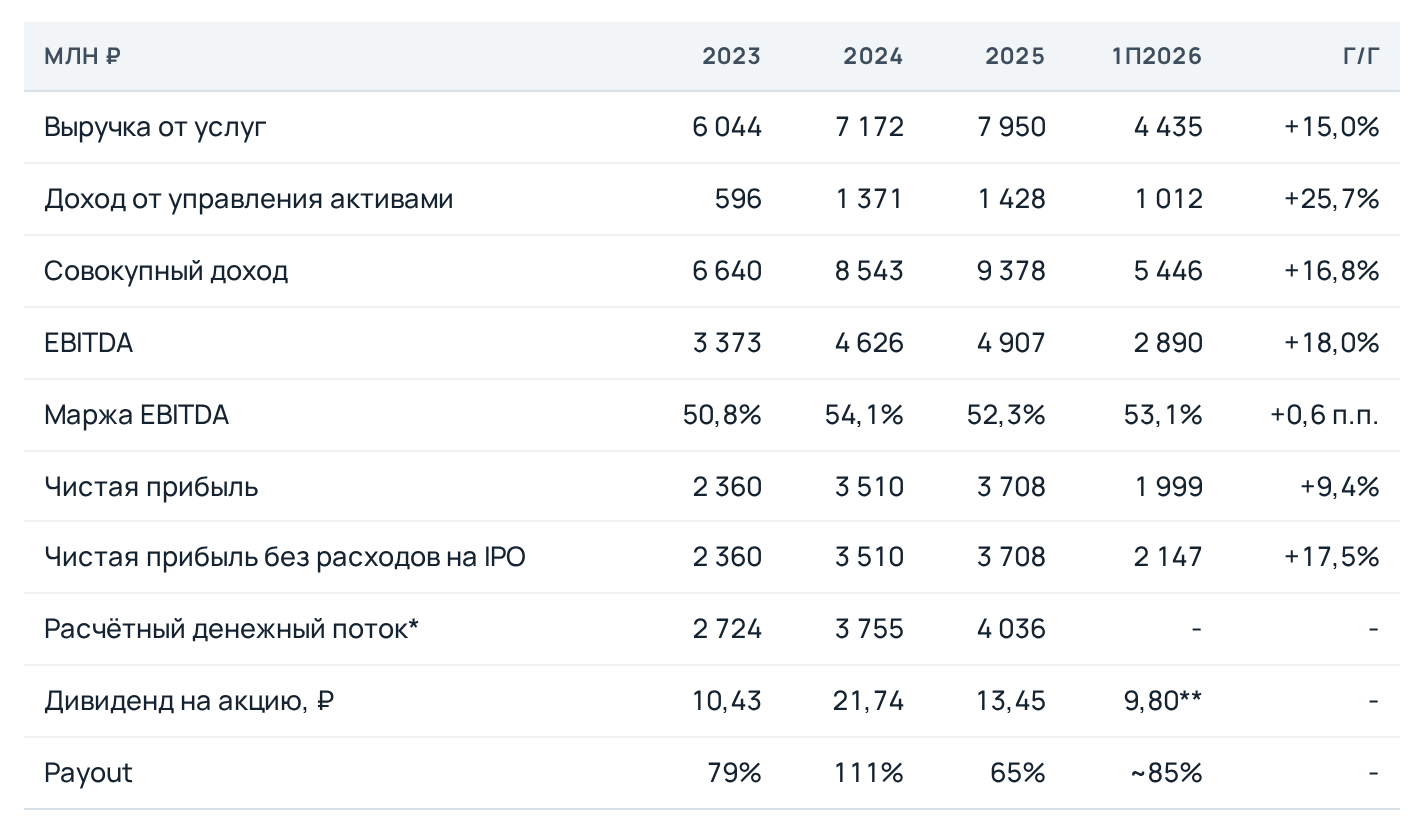
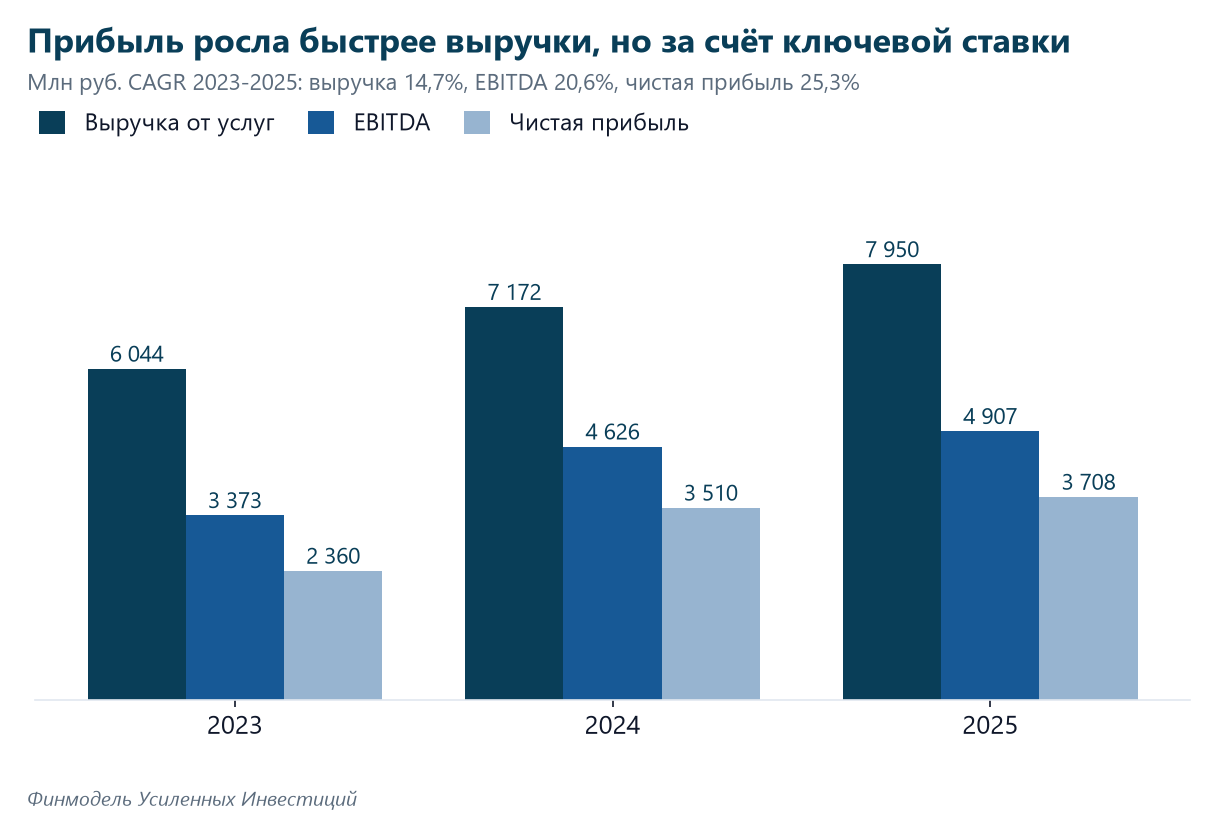
- Half of the profit growth in 2023–2025 came from the key rate, not from the business. Profit grew by 25% a year against 15% for revenue: interest income rose 2.3 times in 2024, when the rate went to 21%. In 2025 the effect ended (RUB 1,428 mn against 1,371 mn), and profit added only 5.7%. The sustainable part is fees, +15% a year.
- Growth came through monetization, not through volume. The number of procedures hardly changed for three years (2,471 to 2,579 thousand, +2% a year), while revenue per procedure rose from RUB 2.4 thousand to 3.1 thousand (+12% a year). That is why 2026 matters: for the first time a volume lever has been added to the price lever (commercial procedures +35%, SVP +49%).
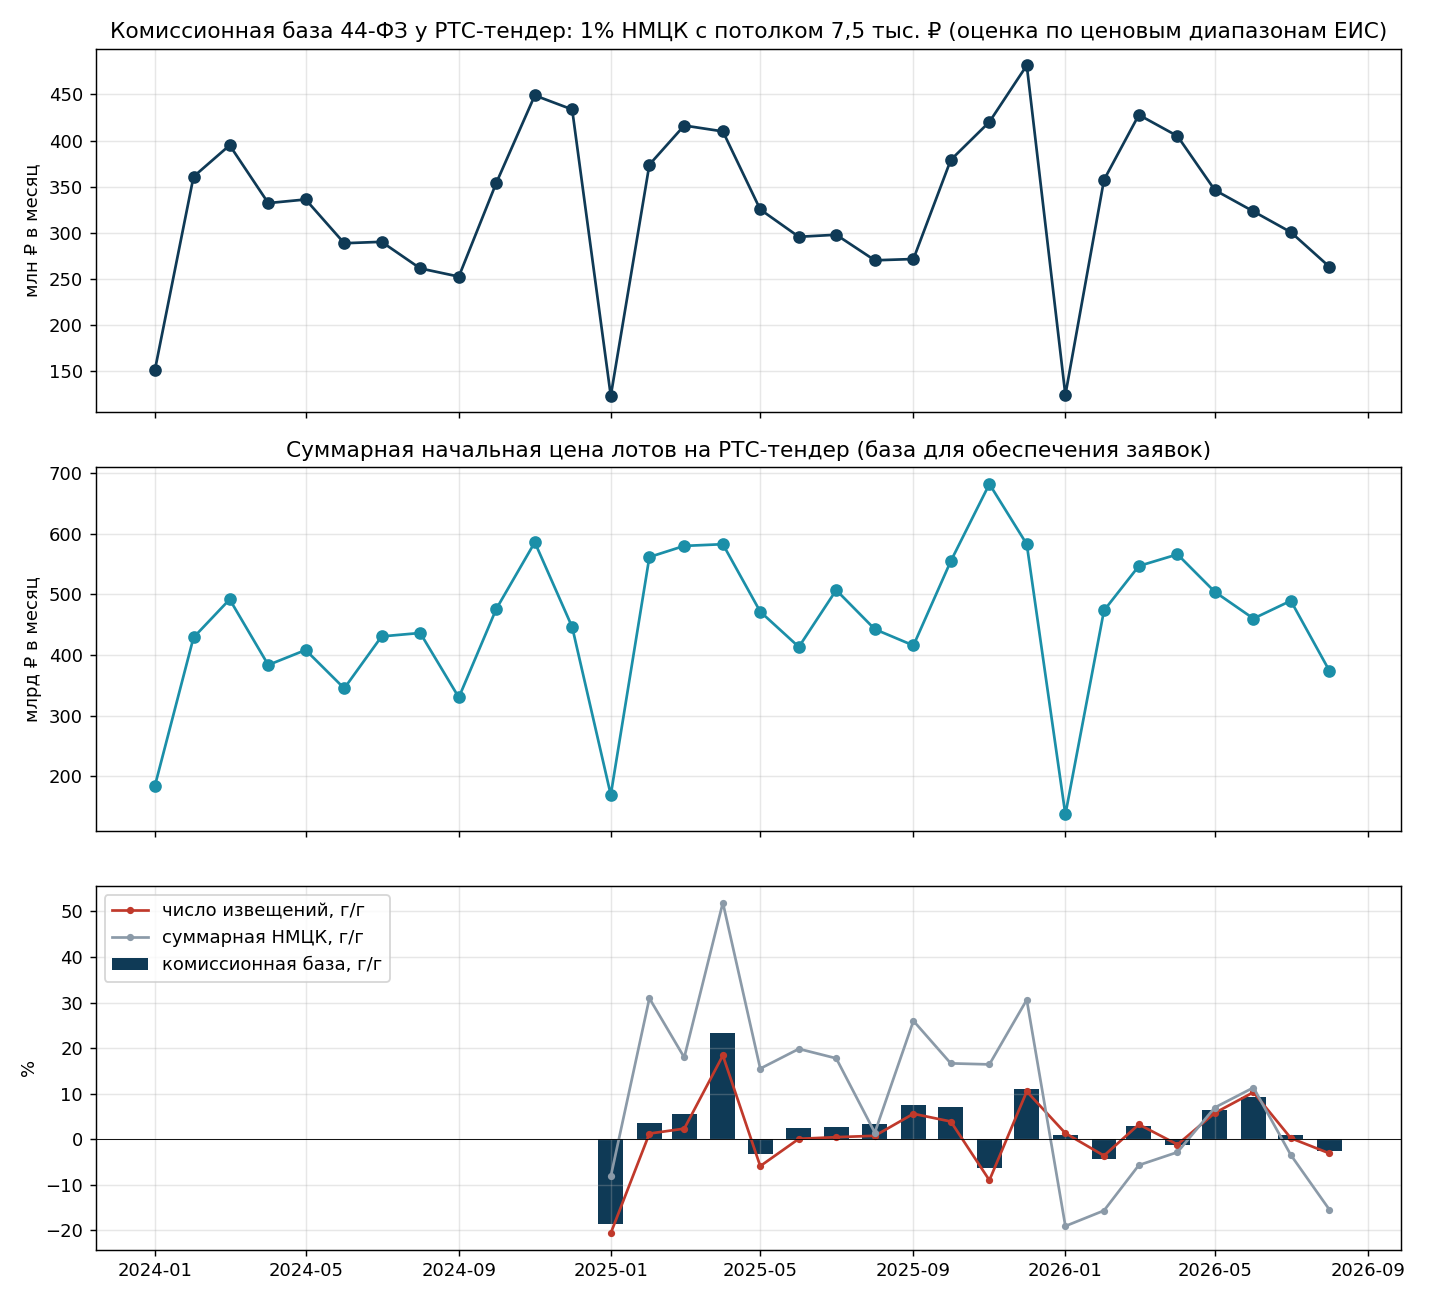
- Interest income is turning down. The +26% y/y in 1H2026 is misleading: the first quarter was inflated by deposits for the sale of Domodedovo (a deposit of RUB 26.45 bn; even a week of placement at 14–16% gives RUB 70–80 mn). The second quarter was RUB 354 mn against 658 mn in the first, minus 46%. Next quarters should be compared with the second, not the first. In 2025, RUB 992 mn of the RUB 993 mn of interest income came from Sovcombank. The base of client funds under 44-FZ is also shrinking: the total starting price of lots on RTS-tender by our count from the EIS grew by 21% in 2025, but fell by 3% in 1H2026 and by 9% in July–August.
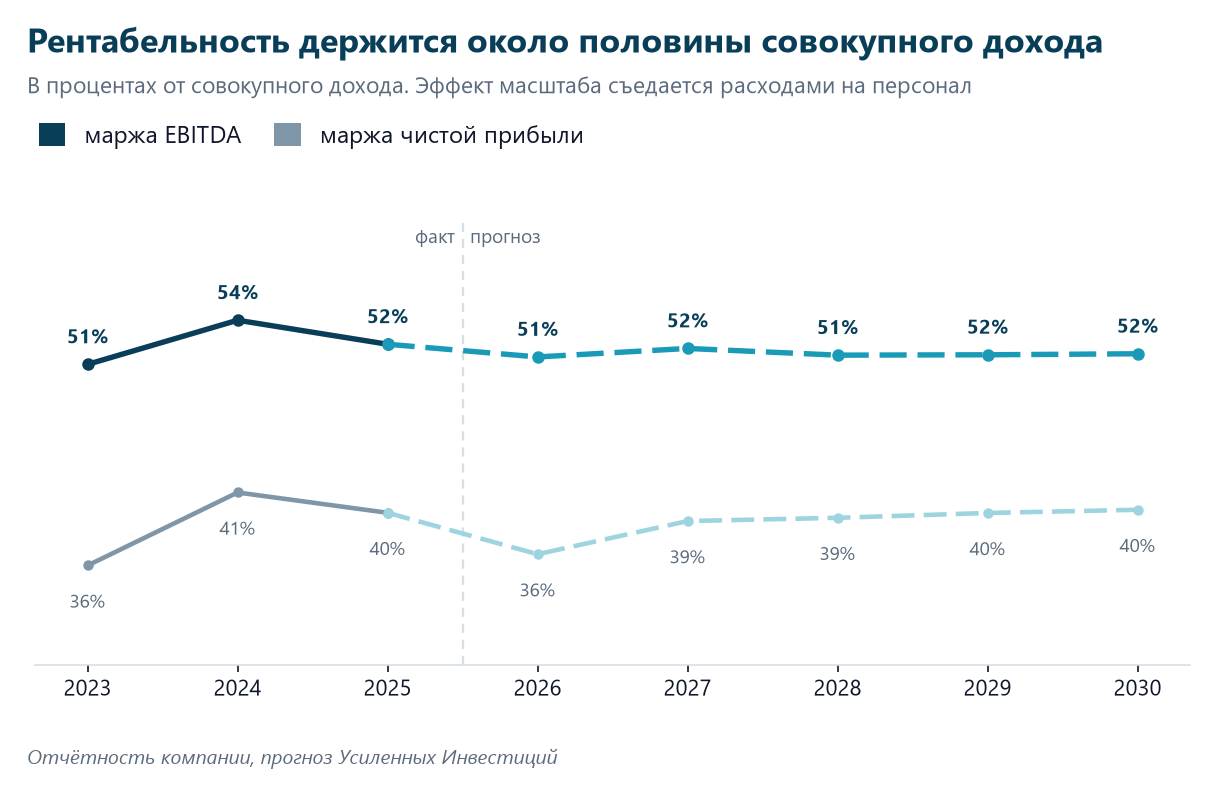
- Expenses are growing faster than revenue, and it is almost entirely personnel. Operating expenses in 2025 were +17.1% with services +10.8%: employee compensation +24.5% (RUB 3,201 mn, 62% of expenses), other items +2–4%. The reasons: contributions of 7.6% to 15% and hiring (about 1,000 people at the end of 2025, 43% of them IT). The share of payroll in revenue from services: 35.9% (2024), 40.3% (2025), 42.4% (1H2026). In the second quarter the share fell to 38.6% against 46.8% in the first: one quarter, so we do not call a peak.
- Regulated procurement is the most profitable segment, services are loss-making. Profitability of regulated procurement for the half-year rose to 61%, of commercial it fell to 49% (segment personnel +27% with revenue +22%). "Services and solutions" doubled their loss: RUB 93 mn against RUB 41 mn. The company calls them part of future growth; for now they are subsidized by the two main platforms.
4. Cash and dividends
- Profit turns entirely into cash. Capex is no higher than 1.8% of revenue, and depreciation covers it (RUB 383 mn against 56 mn in 2025). Working capital is negative: client deposits arrive in advance and also earn interest. The deposits themselves are a liability to participants and must not be added to the dividend reserve.
- There is no debt. The net cash position is RUB 2.1 bn at 30 June, but RUB 1.75 bn of it is dividends already declared for 1Q–2Q (RUB 928 mn paid in July, RUB 824 mn recommended). There is essentially no free cash: everything goes to shareholders.
- Payout of 85% on average over three years, four payments a year. The policy requires a minimum of 50%, and management's guidance is above 85% for 2026 and above 80% afterwards. The controlling shareholder is Sovcombank, which needs the cash flow from its subsidiary; this is an argument for keeping a high payout, but not a guarantee: each payment is approved separately.
- 2026 calendar: 1Q – RUB 5.19 (paid on 14 July); 2Q – RUB 4.61 (recommended by the board on 2 September, meeting on 30 September, record date 11 October); 3Q – RUB 4.23 (forecast); 4Q – RUB 4.91 (forecast). Total RUB 18.93, 15.1% of the current price.
5. Forecast: more conservative than the company
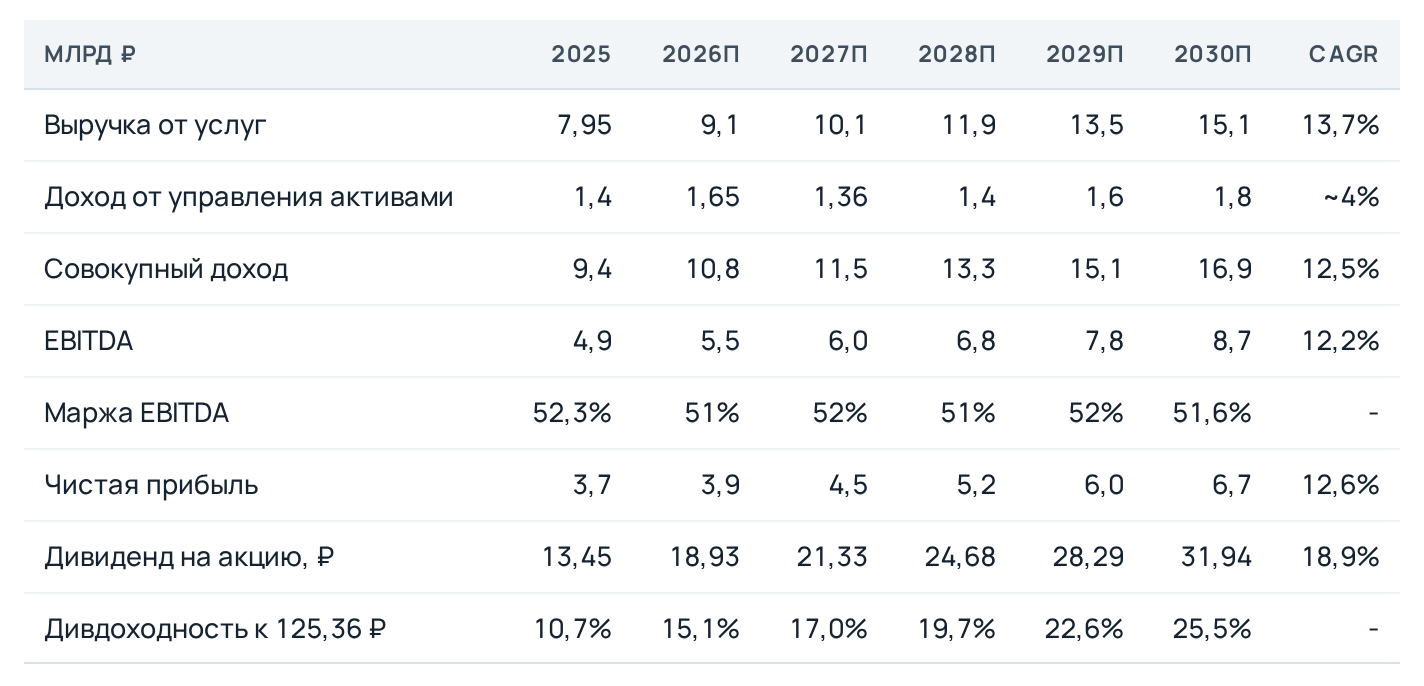
- We are below company guidance. Management guides to RUB 18–21 bn of revenue from services by 2030 (+18–21% a year); we have RUB 15.1 bn (+13.7%). For 2026 we have RUB 9.1 bn against guidance of 9.2: to meet the plan, the second half must be 7.5% stronger than the first, with the usual 50/50 seasonality.
- Where exactly we are more cautious. Government procurement is at the market level or below: the segment has not grown for six years, and there are no grounds for a turnaround other than the Kept and Sovcombank forecasts (+6–8% a year). Our EIS counter confirms this: RTS-tender 44-FZ notices were +1.4% in 2025, +1.7% in 1H2026, and −2.9% year on year in July–August. SVP: the pace fades from 41% in 2026 to 13% in 2030, and we do not take the 66% share as guaranteed. Property auctions were cut by law with a transition period. The half of revenue under a regulated tariff grows at 7.7% a year, the free half at 21%.
- Market forecasts rest on two opposite assumptions: a bold one for the regulated half (Kept +8.1%, Sovcombank +6.1% a year against an actual 0%) and a cautious one for the commercial half (+18% against an actual +26%). The errors partly offset each other; we took the Sovcombank series as the more conservative: the available market RUB 37.2 trn to 62.5 trn, +10.9% a year.
- The EBITDA margin sits at about 51–52%: scale works in its favor, payroll against it, and in the forecast the personnel share stays at 42%. If hiring slows, the margin will rise, which is upside to the base case.
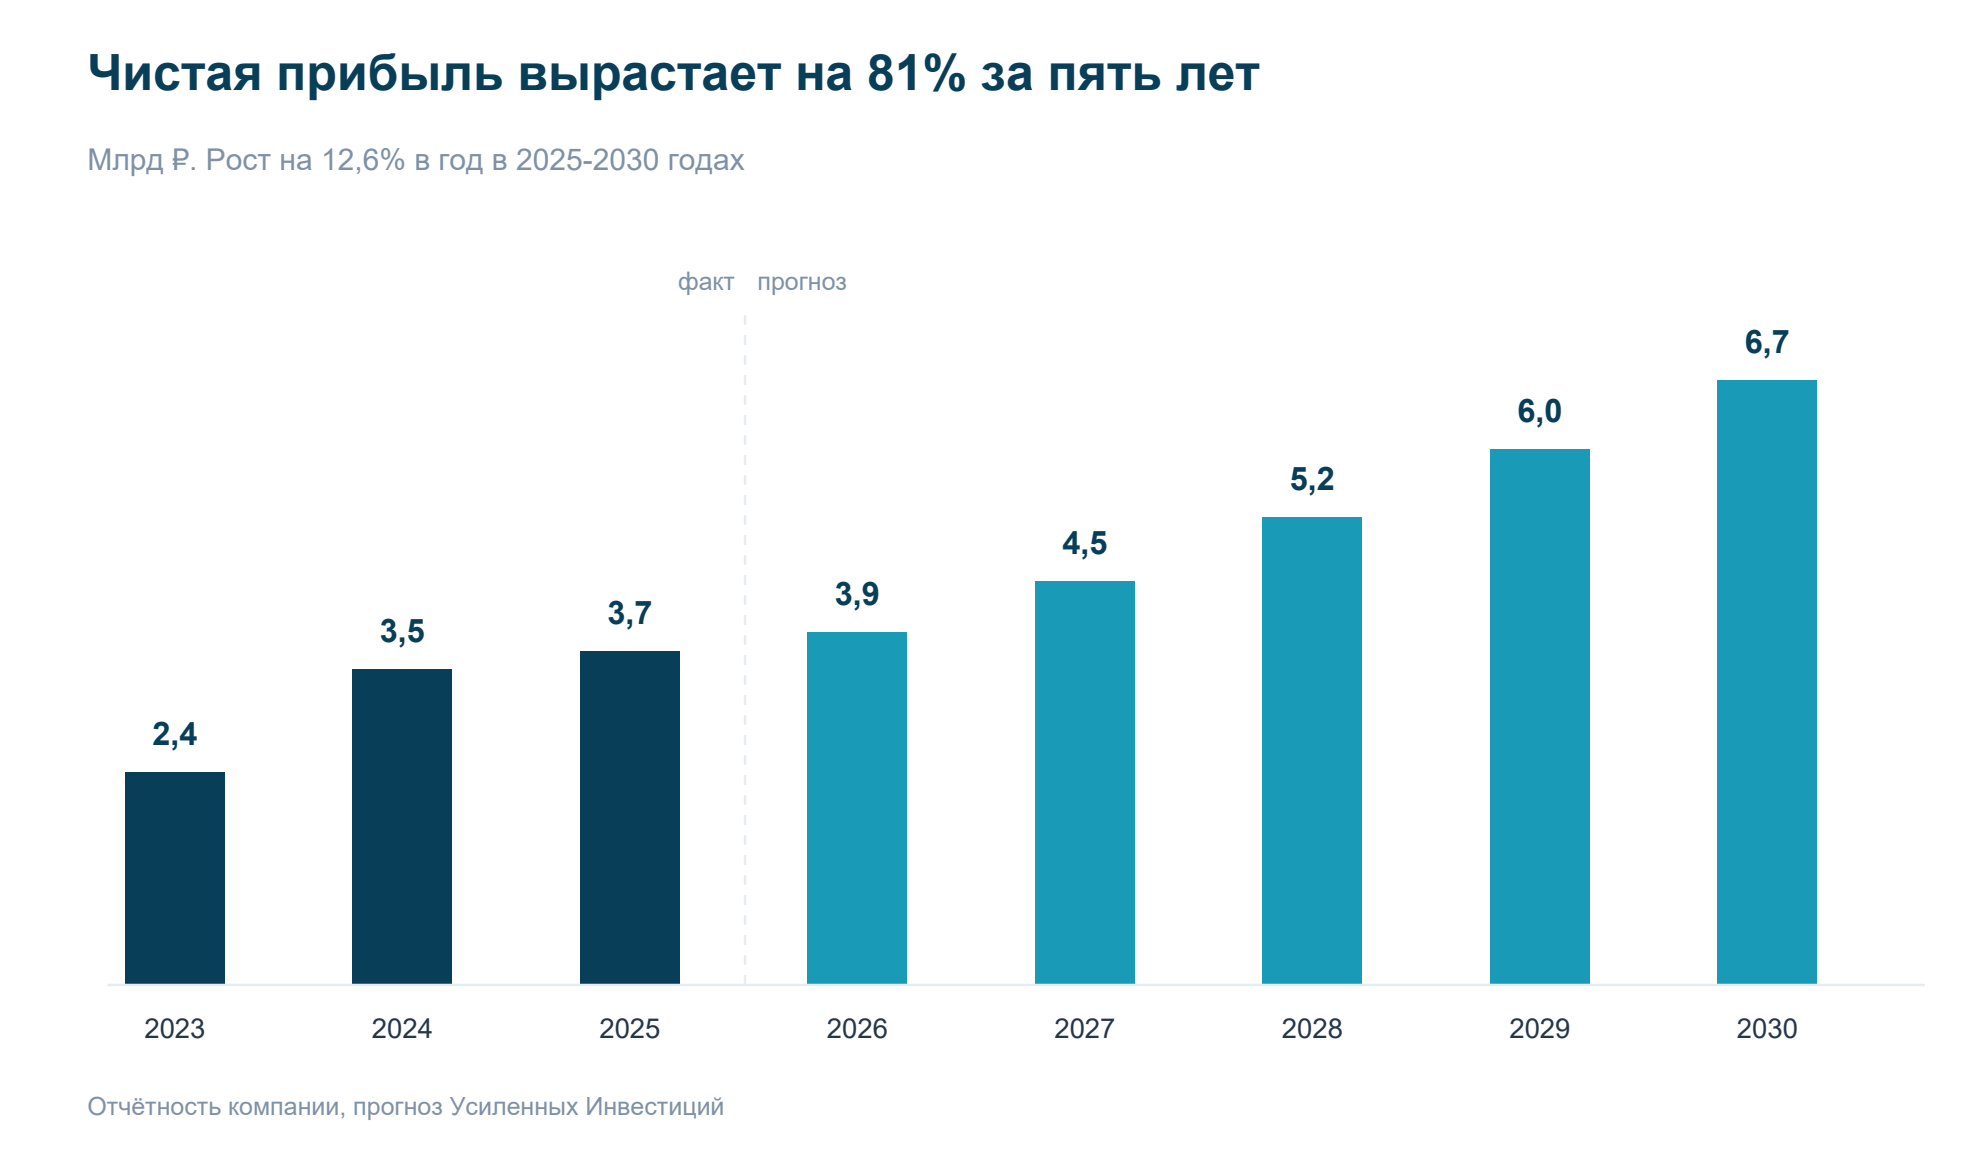
- 2027 is a trough for interest income: RUB 1.65 bn to 1.36 bn, the rate cut outweighs the growth in balances. Profit nevertheless accelerates from +5.7% to +14.5%: services grow and there are no more IPO costs. We do not include large one-off deposits like Domodedovo in the forecast.
6. Valuation: three methods, one answer
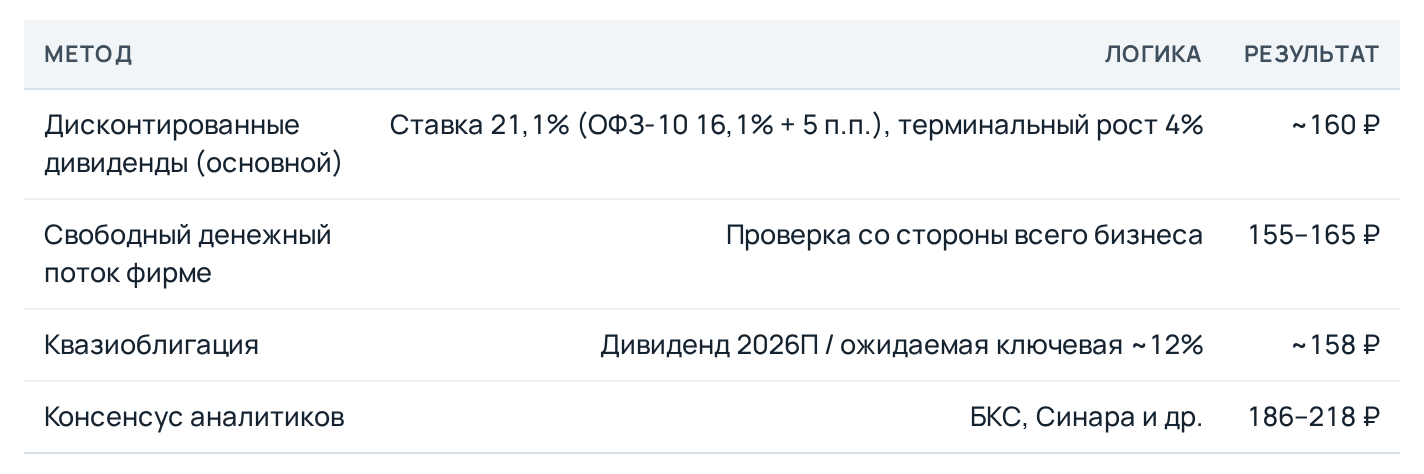
- On multiples, a 40–50% discount to public platforms. P/E 2026E of 5.7 and EV/EBITDA of 3.6 against 6.4 / 5.5 for HeadHunter and 13.1 / 8.7 for Cian (LTM for them). At the same time, profit growth is 12–13% a year and payout 85%, a PEG of about 0.45.
- Why the market gives a discount and why it should narrow. Free float of 11.5%, a short trading history (IPO on 17 April 2026), low daily turnover, and all interest revenue coming from the controlling shareholder. None of the reasons is about the business; all of them fade with time and with growing liquidity.
- The consensus of RUB 186–218 is a "management delivers the plan" scenario. If revenue from services reaches RUB 19–20 bn by 2030 instead of our 15, profit will be about RUB 8.5 bn and the dividend about RUB 40, and the fair price about RUB 200. Our target does not require the plan to be met.
The rate is the main external driver of the re-rating. The share trades at a 15% dividend yield with the key rate at 14%. A rate cut hits interest income (about 15% of total income), but the effect on the price through the required yield is an order of magnitude larger:
7. Risks, with a price in roubles per share
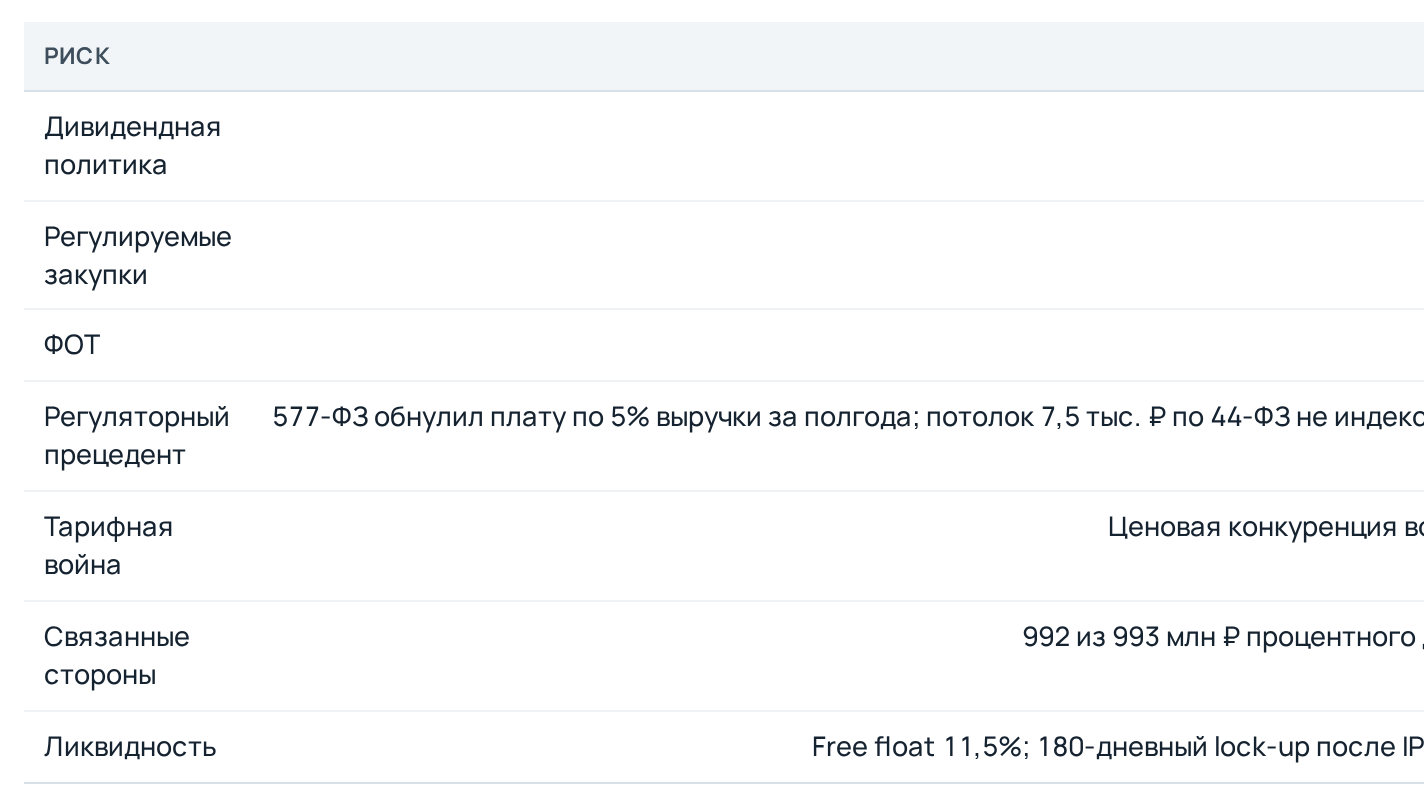
The valuation range under reasonable deviations in the discount rate and market growth is RUB 115–207. The lower bound is below the current price: a negative-return scenario exists and does not require extreme assumptions.
8. What to monitor and when
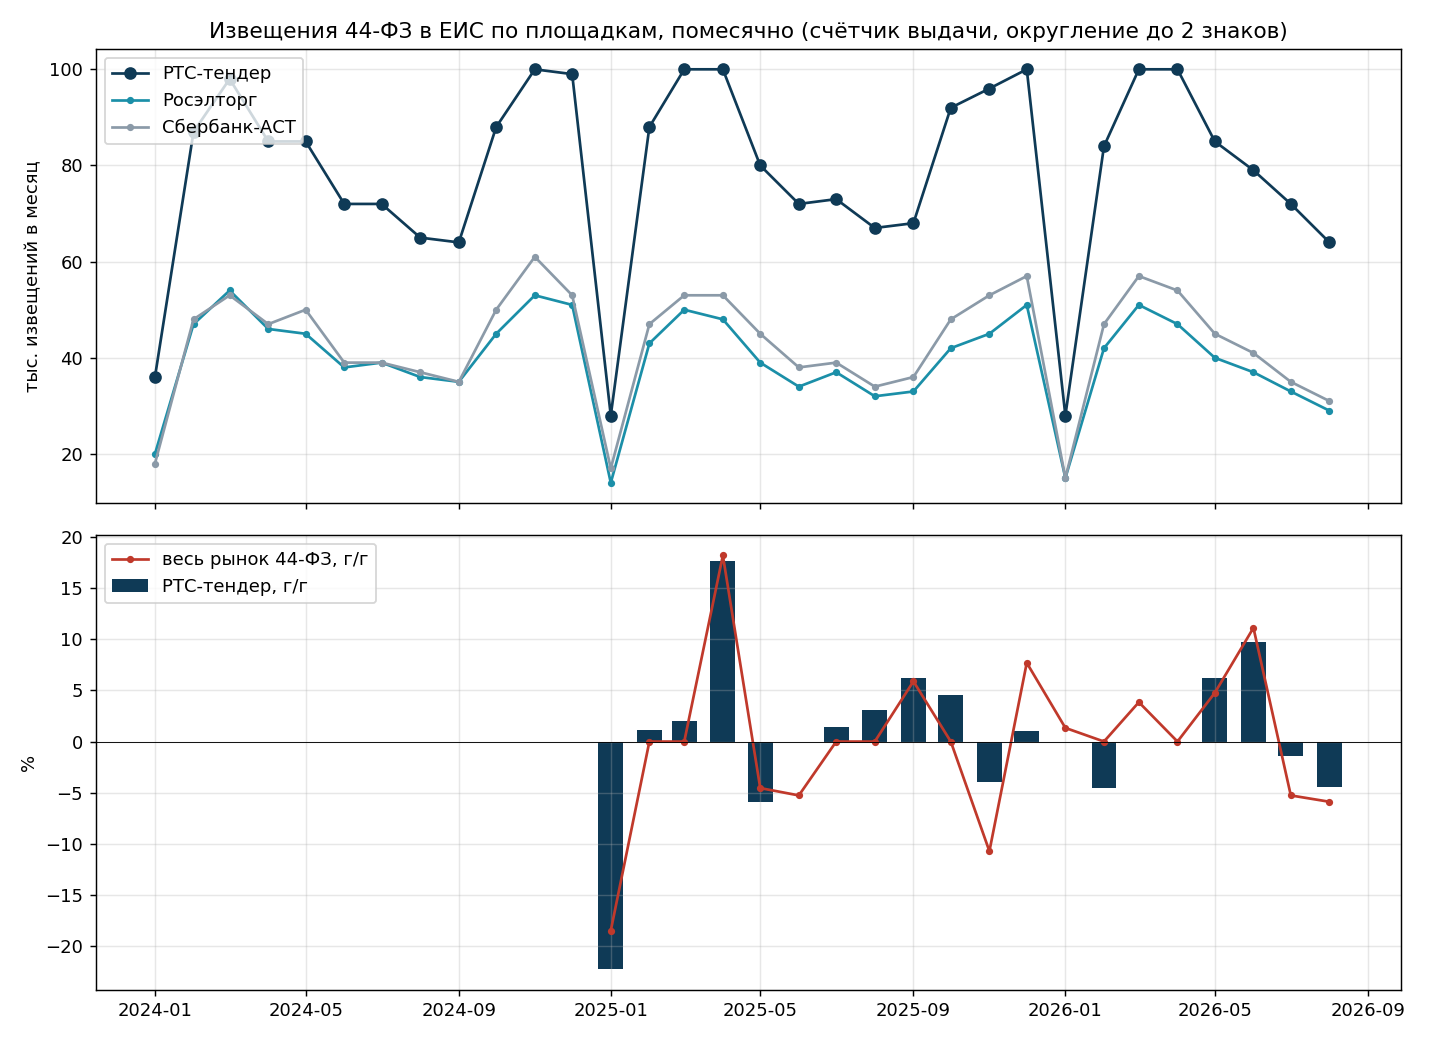
- Our leading indicator for 44-FZ: the counter of notices in the EIS by platform. RTS-tender's share has been a steady 37.5–40% since 2024, with procedures adding 1–2% a year. July–August 2026: RTS-tender −2.9% year on year, the whole 44-FZ market −5.6%, the lot range of RUB 600 thousand to 3 mn (regions and municipalities) has sagged, and small lots did not move to the e-shop. We do not expect volume growth in government procurement in 3Q. The indicator covers 44-FZ and capital repairs, about a quarter of revenue from services; we update it monthly.
- The same counter in money. From the lot price ranges we calculate the fee base (1% of the price with a cap of RUB 7.5 thousand) and the total starting price of lots. RTS-tender's fee base: 2025 +4.1% with units +1.5%, July–August 2026 −0.7% with the market at −5.5%, that is, 44-FZ fees in 3Q are flat. The total price of lots, the base for bid security and interest income: 2025 +21%, 1H2026 −3%, July–August −9%. A second minus for interest income, independent of the rate.
- The Ministry of Finance's monitoring of the e-shop comes out quarterly and ahead of the reporting, and is a leading indicator for SVP.
- We revise the target down if payout falls below 80%, the payroll share settles above 45%, or the number of procedures in commercial procurement and SVP stops growing.
Conclusion
B2B-RTS is the leader by number of procedures in all segments of electronic procurement, with an EBITDA margin of about 52%, no debt or capex, and it returns about 85% of profit to shareholders four times a year. Growth in the coming years is provided by two segments where the company sets the tariff itself and where the number of procedures is growing by 35–49% a year. At a P/E of 5.7 and a 15% dividend yield the share trades like a bond, and a lower key rate works for the re-rating more strongly than against interest income. The target is RUB 155–165 (+28%), 12-month total return about 43%. The main things to watch are the payout on 30 September and the payroll share in the 9M report.
Appendix. How the procurement market works
- Three circuits. 44-FZ covers budget organizations (a ministry, a school, a hospital), with the strictest rules, and the platform must be from the list of eight. 223-FZ covers state companies (Russian Railways, Gazprom), each writing its own procurement regulation. Commercial covers private companies, which buy as they wish. SVP is small purchases from a single supplier through an e-shop, a key segment for B2B-RTS. Separately there are capital repairs of residential buildings (Resolution 615) and property auctions.
- How a procurement runs. The customer posts a notice in the EIS and chooses a platform. The supplier registers once in the EIS and gets accreditation on all eight platforms. Bid security is blocked on a special bank account, the platform runs the auction, the winner signs the contract on the platform and pays the fee under the tariff. The platform does not become a seller and does not recognize the contract price as its revenue.
- Why share is not equal to turnover. The company's shares are measured in numbers of procedures, market volumes in roubles, and the company's average lot is smaller than the market's because of its focus on the regions (5 branches and 28 representative offices). For revenue this is a plus: the fee hits the cap, and a small lot brings almost as much as a large one.
- Protection against the cycle and inflation. More than half of revenue is procurement under the budget plan (consolidated budget spending RUB 63 trn to 81 trn over 2023–2025, never declining). Protection is weakest under 44-FZ: the RUB 7.5 thousand cap is not indexed, and the higher the inflation, the more procedures run into it.
See also: market overview · valuation map · stock screeners