Borets: 18-19% for a state-controlled company with debt at 4x FFO – a higher yield than ODK and GTLK; the risks are non-public accounts and a RUB 5bn wall in November 2027
Borets Capital is the finance company of the Borets group, a maker of submersible pumps for oil production (by the group's own account, its equipment serves about a third of onshore oil output in Russia). There are 5 issues outstanding totalling RUB 12.95bn, rated A-(RU) by ACRA (affirmed 09.07.2026) and A-.ru by NKR (affirmed for four issues on 26.08.2026). The fixed-coupon issues yield 18.0-18.9%, while state-owned companies with the same rating yield about 18%. Verdict: this is one of the most understandable ideas in the A- segment: the group has been under state control since April 2025, the replacement issue of RUB 254mn is redeemed on 17 September with the money already raised, and the next 12 months require only RUB 2.2bn of coupons. What is unclear is the reporting itself: the consolidated IFRS of PK Borets is not publicly disclosed, and everything we know about the group's debt comes from ACRA.
The issuer card on the portal with financials by period, our credit analysis and all issues: Borets Capital. Below are the calculations of Enhanced Investments based on the issuer's IFRS and RAS statements, the MOEX payment schedule and disclosures; where a figure is the authors' estimate, it is marked as such.
What we are buying: an SPV with RUB 1mn of revenue and all of the group's debt – PK Borets is what needs to be assessed
Fact. The issuer, Borets Capital LLC, is a financing shell: its own revenue is RUB 0.5-1mn a year, it has an operating loss and equity of RUB 0.2bn against assets of RUB 33bn. All bonds are guaranteed by PK Borets LLC, the group's operating company. The issuer's standalone IFRS says nothing about credit quality, so it is hidden on our card, and the analysis is built on group data from the rating release.
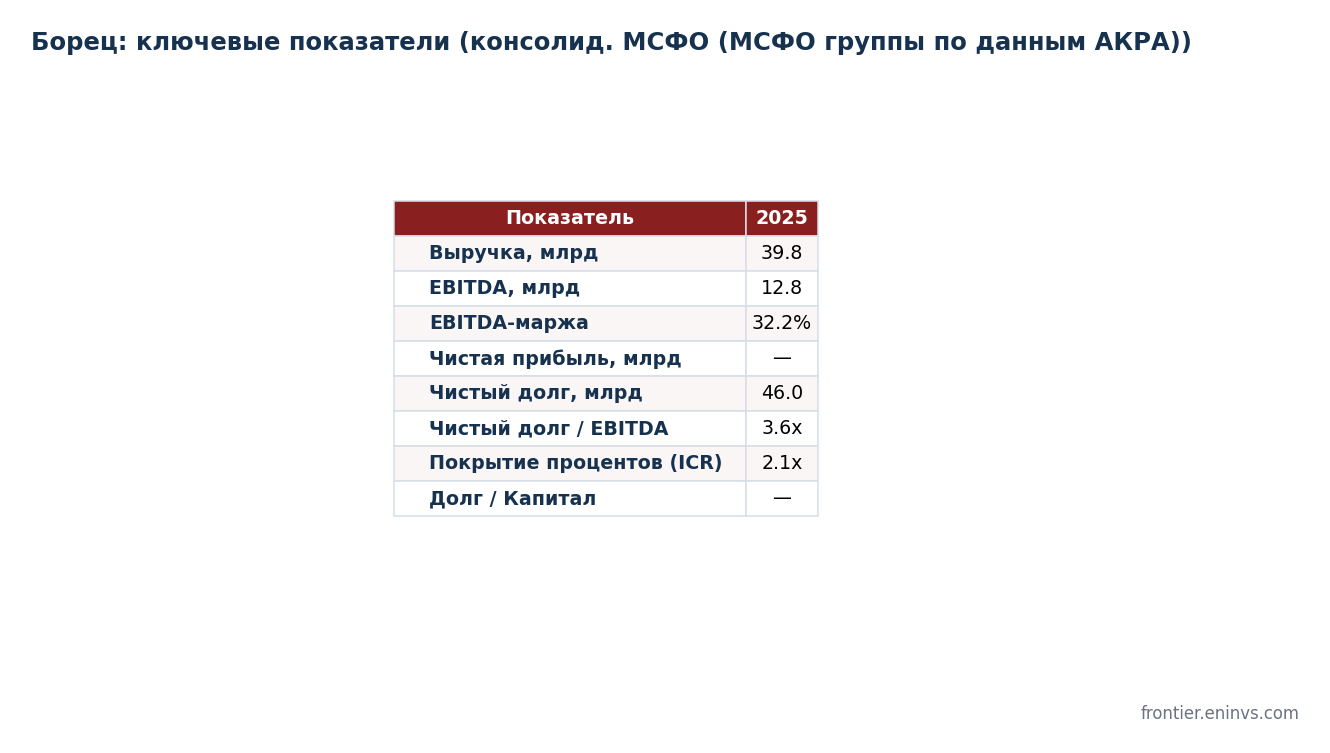
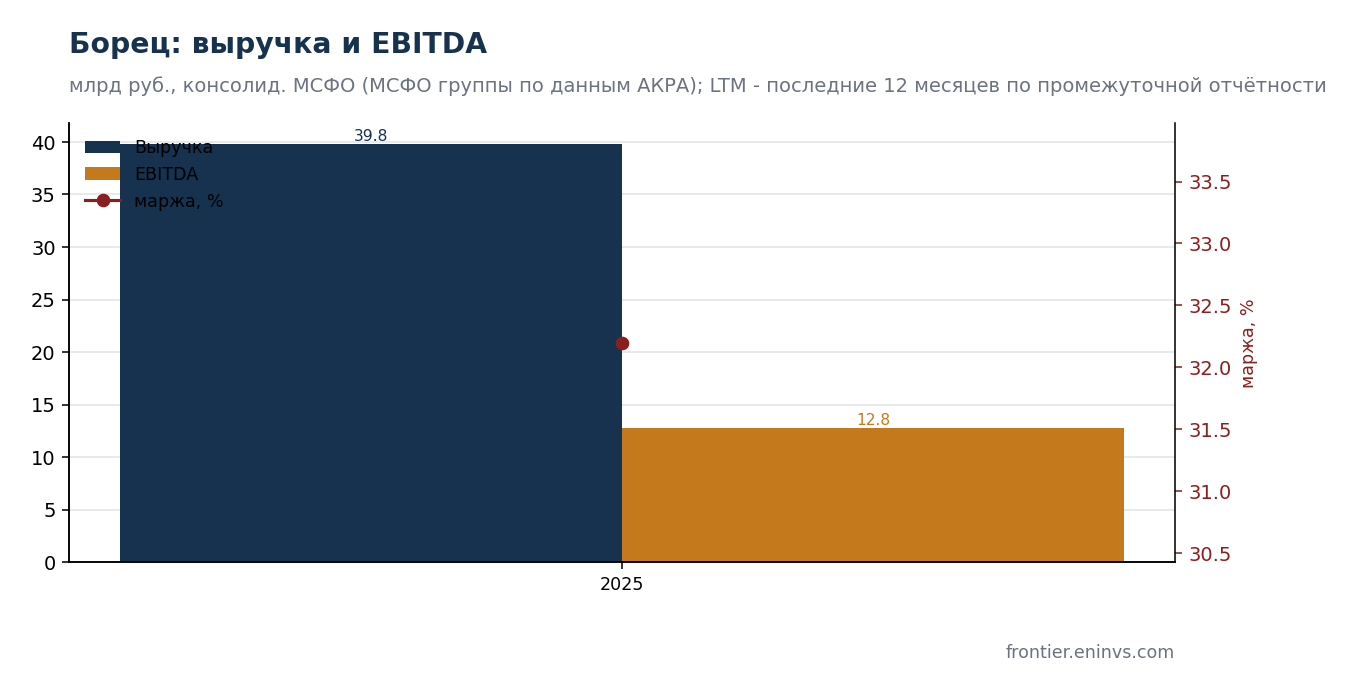
Fact (ACRA, 09.07.2026). The group's 2025 FFO before interest and taxes was RUB 12.8bn at a 32.2% margin, total debt fell to RUB 46bn, debt to FFO 4.0x, interest cover 2.1x, and free cash flow is negative (minus 3.5% of revenue). The agency estimates debt to FFO weighted over 2024-2028 at 3.3x and expects revenue growth of at least 8% a year with no dividends.
Authors' estimate. From FFO of RUB 12.8bn and a 32.2% margin, group revenue comes out at about RUB 40bn. Leverage of 3.6-4.0x is elevated for a machine builder, and negative FCF means deleveraging comes not from cash flow but from refinancing and withheld dividends.
State control removed the shareholder risk but left a mark: the 2025 technical default caused by the asset seizure
Fact. In April 2025 a court upheld the Prosecutor General's claim, and the group passed under state control through Rosimushchestvo. During the seizure of assets the issuer committed a technical default on a coupon; payments were later restored, and the Moscow Exchange still flags the issuer as "had a technical default". Management view (Anton Kulikov, BCS, broadcast of 01.09.2026): the rating outlook was raised to positive because the liquidity risk is gone: half of the debt was a replacement eurobond maturing in September, and the company bought it back in advance through an offer, so the money for redemption has already been raised. The Borets and Domodedovo cases, in his words, showed that after passing to the state coupons keep being paid and credit quality tends to improve.
Authors' assumption. State control is both protection and a constraint: decisions on dividends, capex and refinancing are no longer taken by a market shareholder. For a bondholder this is more of a plus while the state is interested in a working producer of pumps for a third of oil output.
Fact. On 26.08.2026 NKR affirmed A-.ru on issues 1R03, 1R04, 1R05 and 1R07 (disclosed 27.08); August coupons were paid on time on 21.08. There have been no negative notices on e-disclosure since mid-August.
How it gets paid: RUB 2.2bn of coupons a year and a RUB 254mn redemption on 17 September are comfortable; the wall is the RUB 5bn floater in November 2027
Fact. According to the MOEX schedule, over the next 12 months Borets Capital pays about RUB 2.2bn of coupons (RUB 0.18bn a month) and redeems the replacement issue ZO-2026 of RUB 254mn in US dollar equivalent on 17.09.2026. The next large redemption is RUB 5bn on the floater 1R04 on 14.11.2027, then RUB 1bn on 1R03 in May 2028, RUB 2.5bn on 1R05 in February 2029 and RUB 4.2bn on 1R07 in May 2029. None of the issues has a put offer.
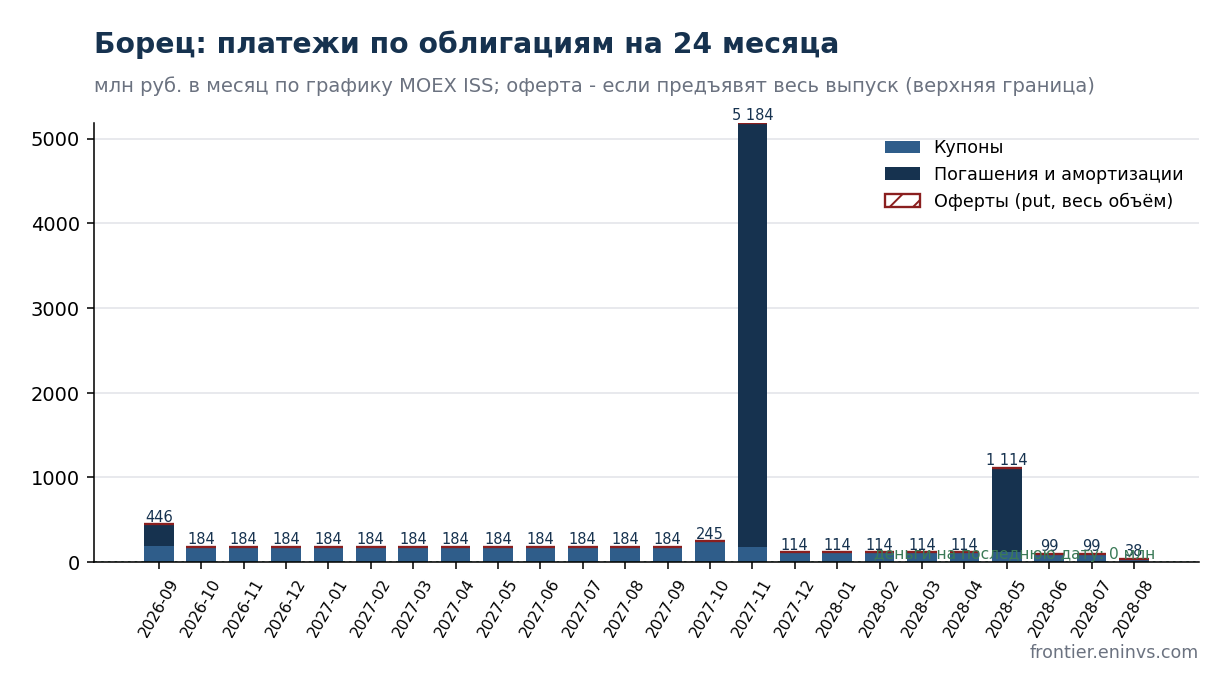
Authors' estimate. With FFO of RUB 12.8bn and interest of about RUB 6bn (cover of 2.1x per ACRA), annual bond coupons of RUB 2.2bn are a third of the group's interest burden, the rest being banks. November 2027 with RUB 5bn is the only point where refinancing will be needed, and the group has two years to get there.
Market: 18.0-18.9% on the fixed-coupon issues and a spread of 315-383 bp – more than ODK and GTLK at the same rating
Fact. 1R03 (18%, May 2028) yields 18.0% at a price of 102, 1R05 (18.5%, February 2029) 18.0% at 103.6, 1R07 (17.75%, May 2029) 18.9% at 100.8. The spread to OFZ is 315-383 bp. The floater 1R04 trades at 100.1 with a MOEX yield of 17.7%. Per Kulikov, state-owned ODK and GTLK with a comparable rating yield about 18%, and Borets at 19% for almost three years should, in his view, compress to at least 18%.
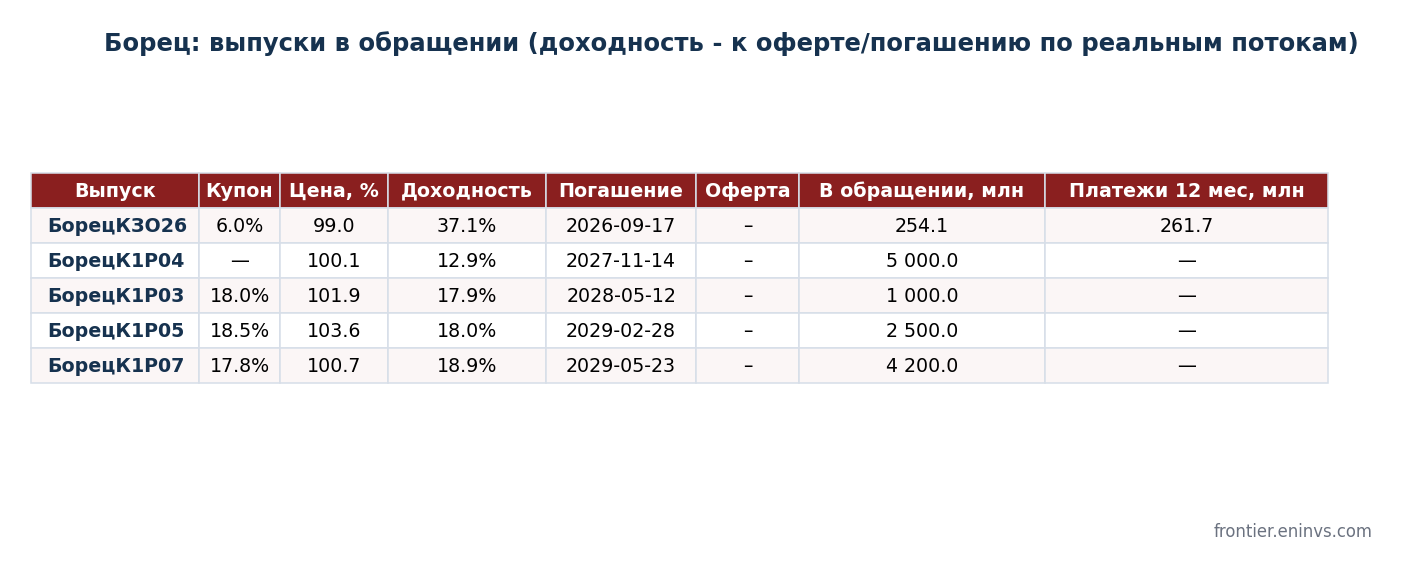
Authors' estimate. In our sample a spread of 315-383 bp lies inside the A- basket, meaning the market no longer demands a premium for the 2025 technical default. The idea is not a revaluation but an 18% coupon on a state-company credit whose debt the agency expects to decline.
Risks: a blind spot in reporting, negative FCF and the oil price
- Non-public consolidation. PK Borets does not disclose IFRS; all group figures are known through agency press releases. They cannot be verified independently, and on the portal card we mark this honestly.
- Negative free cash flow. FCF of minus 3.5% of revenue in 2025 with debt at 4x FFO: deleveraging depends on the 8% annual revenue growth that ACRA assumes and on zero dividends.
- Oil producers' demand. Pump sales follow drilling and well workovers; OPEC+ output cuts and lower oil company capex hit revenue.
- November 2027. RUB 5bn on the floater is 40% of bond debt on a single date.
Conclusion: a reliable part of a high-yield portfolio with a yield above state companies, paid for opacity
Borets is a rare case where the premium is paid not for credit risk but for the lack of public reporting and the trace of a technical default. Debt at 4x FFO is elevated, but the state as controlling shareholder and an A- rating with a positive outlook make the story predictable over the 2027 horizon. For the conservative part of a high-yield portfolio, the fixed-coupon 1R03 and 1R05 at an 18% yield look reasonable; 1R07 is longer and slightly higher-yielding. One thing to watch: whether the group's consolidated reporting appears; until it does, one has to trust the agencies.
Sources and caveats
- ACRA, press release of 09.07.2026 on the affirmation of A-(RU) for PK Borets LLC and the bonds of Borets Capital LLC – the only public source of consolidated group metrics.
- NKR, affirmation of A-.ru on issues 001P-03/04/05/07 of 26.08.2026 (issuer notice of 27.08.2026).
- Standalone IFRS and RAS of Borets Capital LLC (e-disclosure, GIR BO) – not used for assessing the group.
- Schedule of coupons and redemptions – MOEX ISS; quotes – MOEX close on 03.09.2026.
- BCS broadcast with Anton Kulikov of 01.09.2026 – the speaker's position is given with attribution.
Other issuer reviews and weekly analytics are in the Telegram channel Enhanced Investments @eninv; extended cards of all issuers are on the portal.
See also: market overview · valuation map · stock screeners