Bank Saint Petersburg: profit fell 38.8%, but a 23.2% trailing dividend yield holds the stock up
On 28 September Bank Saint Petersburg released its Q2 2026 results. Net interest income came in at RUB 18,223 mn, down 6.6% year on year, while net profit was RUB 5,580 mn, 38.8% lower than a year earlier. The ratio of net profit to net interest income fell to 30.6% from 46.8% a year earlier. The share looks attractive for a holder on the strength of its dividend yield: we estimate the next payout at RUB 42.84 per share, a 16.1% yield on the current price, against the 11.0% yield we consider fair.
Key takeaways
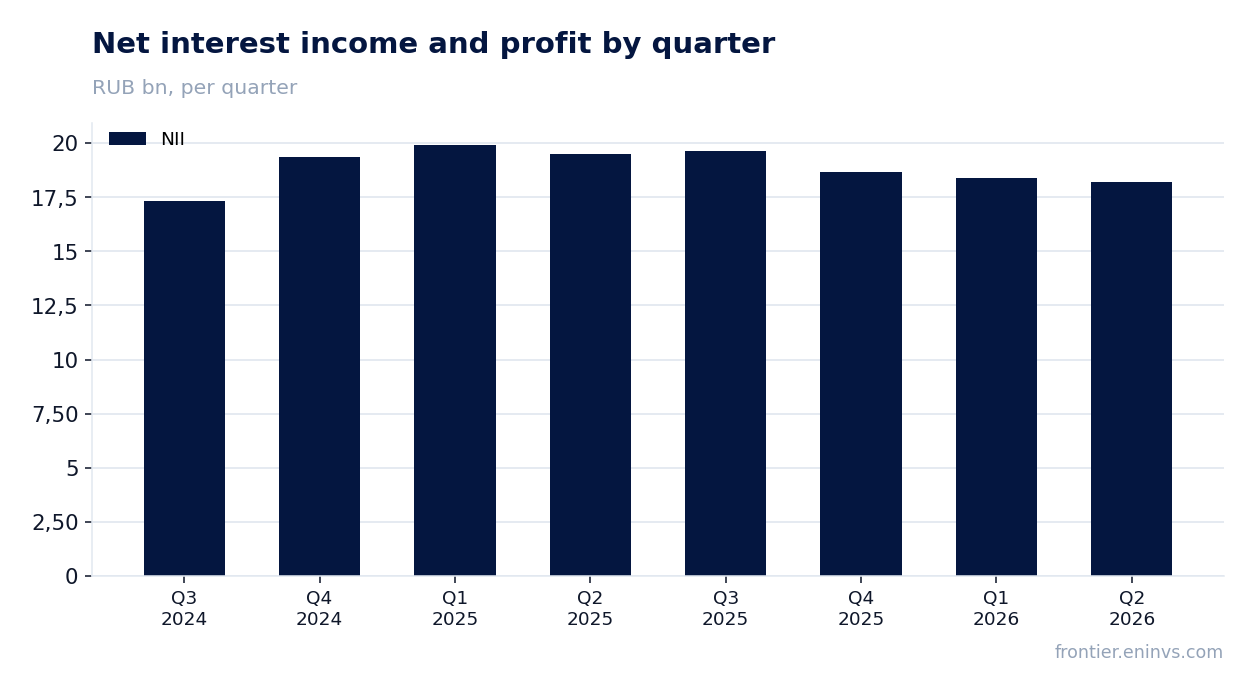
— Net interest income fell 6.6% year on year to RUB 18,223 mn, but the rate of decline slowed compared with the first quarter
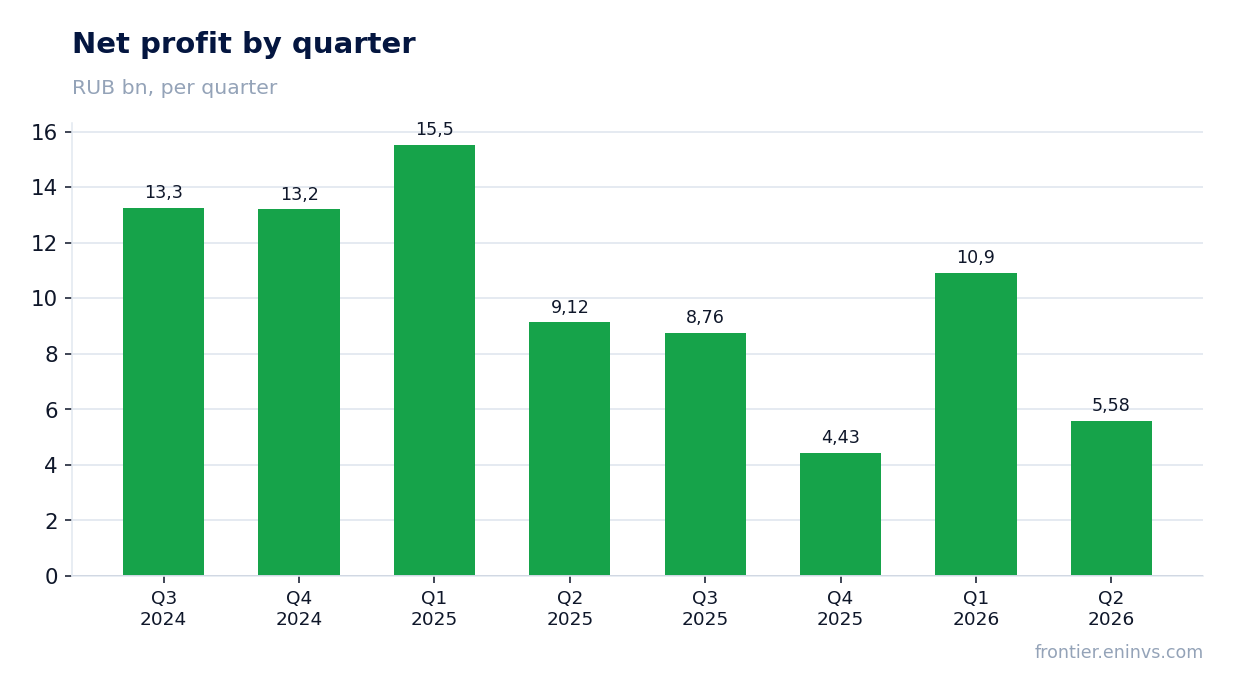
— Q2 profit dropped 38.8% year on year to RUB 5,580 mn, and its share of net interest income fell to 30.6% from 46.8%
— Fee and commission income rose to RUB 3,146 mn, partly offsetting the weakness in net interest income
— The dividend paid over the last 12 months was RUB 62.01 per share, a 23.2% yield on the current price
— We estimate the next dividend at RUB 42.84 per share, a 16.1% yield and a payout ratio of 0.41 of profit
— The bank trades at a P/E LTM of 4.0 and an ROE of 10.2%, below the yield we consider fair for this name
— On the portal's model, the upside of the share to its fair value is +29%
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | 19.5 | 18.2 | -6.6% |
| Net profit | 9.12 | 5.58 | -38.8% |
| Net margin | 46.8% | 30.6% | -16.2 pp |
Net interest income fell 6.6% year on year to RUB 18,223 mn, but the rate of decline slowed compared with the first quarter
Bank Saint Petersburg's net interest income in Q2 2026 was RUB 18,223 mn, 6.6% less than in the same quarter a year earlier. This is the fourth consecutive quarter of year-on-year decline: in Q4 2025 the drop was 3.4%, in Q1 2026 it was 7.8%. The decline continues, but its pace in Q2 was slightly slower than in Q1.
The main reason is the reduction in interest income amid the falling key rate. The bank earns on the spread between loan and deposit rates, and when the central bank rate falls, the margin compresses. The key rate now stands at 14.0%, and its further decline will continue to pressure net interest income.
Fee and commission income rose to RUB 3,146 mn, partly offsetting the fall in net interest income. However, its share of total income remains small, and it cannot fully offset the decline in interest income. The dynamics of net interest income remain the key factor for the bank's profit.
Q2 profit dropped 38.8% year on year to RUB 5,580 mn, and its share of net interest income fell to 30.6% from 46.8%
Bank Saint Petersburg's net profit in Q2 2026 was RUB 5,580 mn, 38.8% less than a year earlier. For comparison: in Q1 2026 profit was RUB 10,911 mn, and in Q4 2025 it was RUB 4,432 mn. Thus, Q2 was weaker than Q1 but better than Q4 last year.
The ratio of net profit to net interest income fell to 30.6% from 46.8% a year earlier. This means the bank began spending a larger share of net interest income on expenses and provisions. The reasons are not disclosed in the report, but the significant decline in the ratio itself indicates pressure on profitability.
The fall in profit against a relatively small drop in net interest income suggests that expenses or provisions increased. Without detail from the bank, we cannot name the specific line, but the dynamics are clear: profit is falling faster than revenue.
Fee and commission income rose to RUB 3,146 mn, partly offsetting the weakness in net interest income
Bank Saint Petersburg's fee and commission income in Q2 2026 was RUB 3,146 mn, up from RUB 2,841 mn a year earlier. This is the only major income line that showed growth. In Q1 2026 fee and commission income was RUB 2,795 mn, so in Q2 it also grew quarter on quarter.
The growth in fee and commission income is a positive signal, but its share of total income remains small. With net interest income of RUB 18,223 mn, fees account for about 17% of the sum of interest and fee income. This is not enough to reverse the overall trend of falling profit.
Nevertheless, income diversification is an important factor of resilience. If the bank can grow fee income faster, it will partly offset the pressure on the interest margin.
The dividend paid over the last 12 months was RUB 62.01 per share, a 23.2% yield on the current price
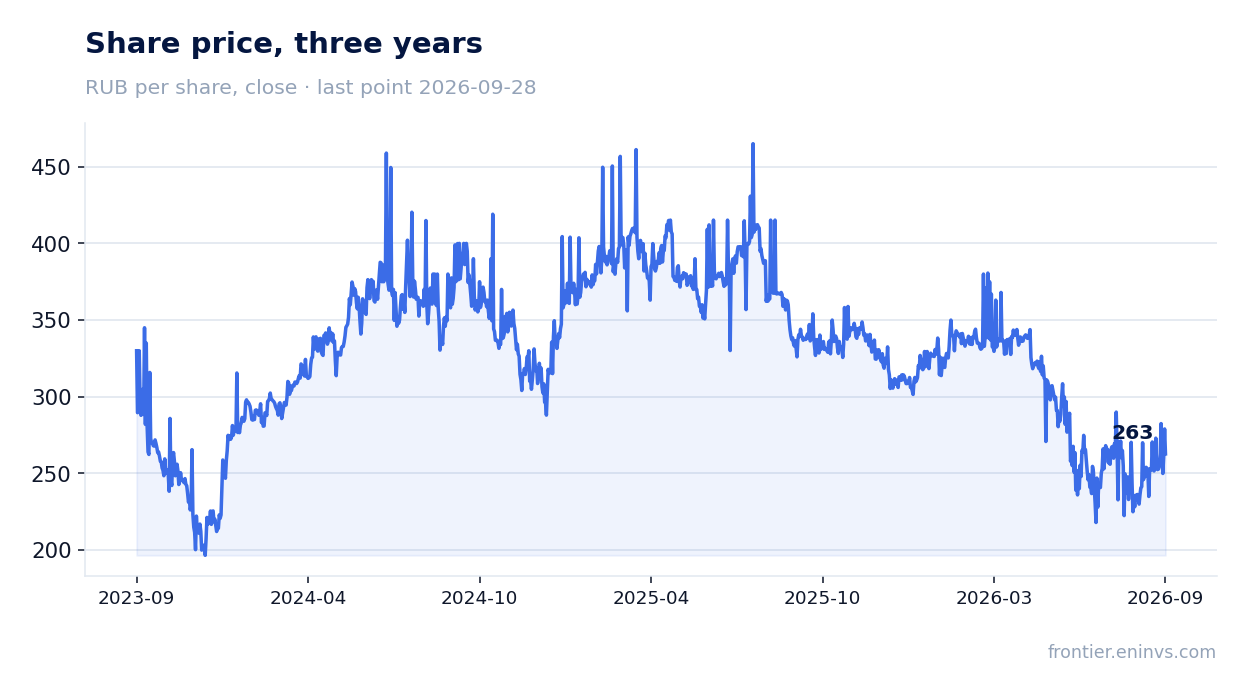
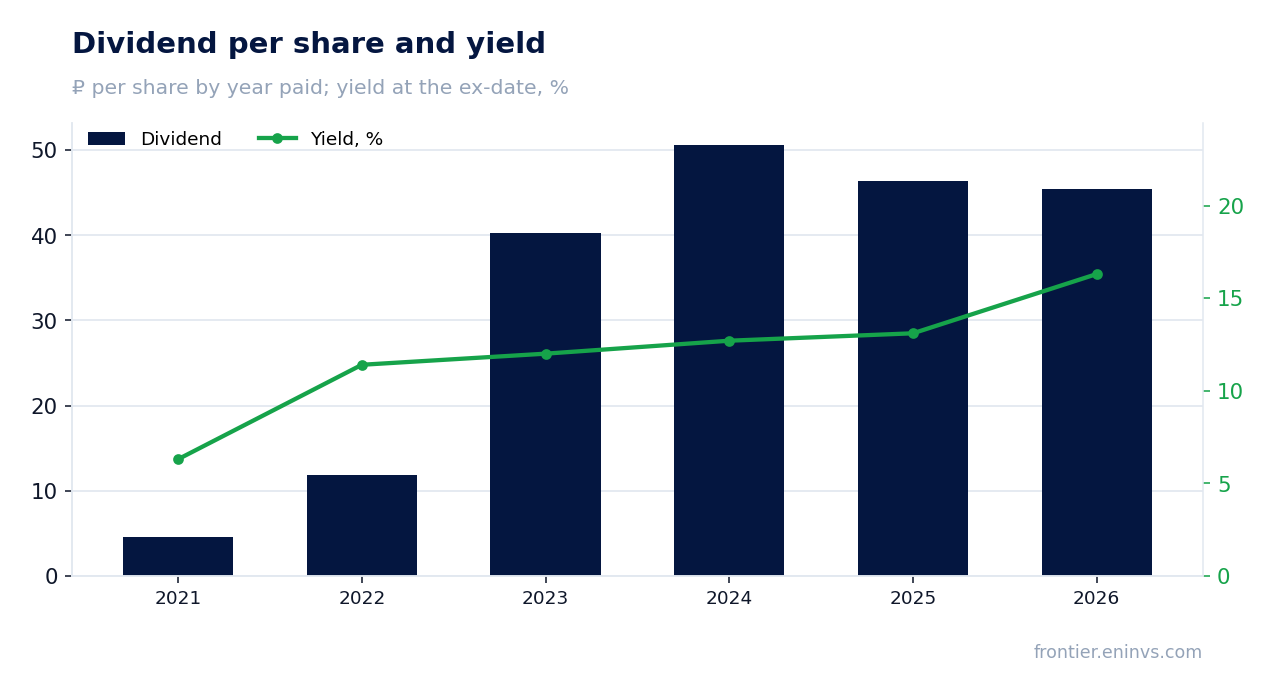
Over the last 12 months Bank Saint Petersburg paid dividends of RUB 62.01 per share. At the current price of RUB 238.92, this gives a trailing yield of 23.2%. For comparison: in 2025 the dividend was RUB 46.33 per share with a yield of 13.1% at the ex-date, in 2024 – RUB 50.63 with a yield of 12.7%, in 2023 – RUB 40.24 with a yield of 12.0%. The current yield is substantially above the historical level.
Such a high yield is explained primarily by the fall in the share price: the stock has become cheaper since the start of the year, which automatically raised the yield. In addition, the bank paid a large dividend for 2025, which included both regular and possibly one-off payments.
The key rate now stands at 14.0%. A yield of 23.2% significantly exceeds the rate, making the share attractive for income-oriented investors. However, the sustainability of such a payout level depends on the bank's profit, which is declining.
We estimate the next dividend at RUB 42.84 per share, a 16.1% yield and a payout ratio of 0.41 of profit
According to our model, Bank Saint Petersburg's next dividend will be RUB 42.84 per share. At the current price of RUB 238.92, this gives a forward yield of 16.1%. This is below the trailing yield of 23.2% but still significantly above the yield we consider fair for this name – 11.0%.
Our estimate assumes a payout ratio of 0.41 of profit. This means the bank will allocate about 41% of net profit to dividends. Such a payout level looks sustainable if profit does not continue to fall at the same pace as in Q2.
The main risk to the dividend is a further decline in profit. If annual profit comes in below our assumption, the dividend could be smaller. The payout may also be affected by the bank's capital adequacy policy: if loan quality deteriorates, the bank may prefer to retain capital rather than distribute it to shareholders.
The bank trades at a P/E LTM of 4.0 and an ROE of 10.2%, below the yield we consider fair for this name
Bank Saint Petersburg trades at a P/E LTM of 4.0 and a return on equity of 10.2%. For the banking sector, such a P/E looks low, reflecting market concerns about further profit declines. Market capitalisation stands at RUB 119,198 mn.
A comparison of the current P/E with its own three-year history is not possible due to the absence of data in the FACTS. However, it can be noted that with an ROE of 10.2% and a P/E of 4.0, the market values the bank below book value, which is typical for banks with falling profits.
On the portal's model, the upside of the share to its fair value is estimated at +29%. This is our own estimate, based on comparing ROE and P/B. It is not a market consensus and should not be taken as a target price.
On the portal's model, the upside of the share to its fair value is +29%
On the portal's model, Bank Saint Petersburg shares have an upside to fair value of +29%. This estimate is based on comparing return on equity (ROE 10.2%) and the price-to-book ratio (P/B). The model assumes the market underestimates the bank's ability to generate profit at a level close to the current one.
It should be noted that the model is not a price forecast and does not account for possible changes in dividend policy or asset quality. It merely shows how much the current price deviates from an estimate based on fundamental metrics.
The share is held in our live model strategies on the portal – RU Banks & financials (potential). This is a fact, not an argument for the verdict: membership is determined by the strategy's own screen.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 119 bn ₽ |
| P/E (LTM) | 4.0 |
| P/B | 0.55 |
| ROE | 10.2% |
| Dividend yield (12m) | 16.1% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2021 | 4.56 | 6.3% |
| 2022 | 11.81 | 11.4% |
| 2023 | 40.24 | 12.0% |
| 2024 | 50.63 | 12.7% |
| 2025 | 46.33 | 13.1% |
| 2026 | 45.40 | 16.3% |
Bottom line
Bank Saint Petersburg reported Q2 2026 with net profit down 38.8% year on year to RUB 5,580 mn and net interest income down 6.6% to RUB 18,223 mn. The ratio of profit to net interest income fell to 30.6% from 46.8%, indicating higher expenses or provisions. The only positive was the growth in fee and commission income to RUB 3,146 mn. The dividend yield remains high: 23.2% trailing and 16.1% forward on our estimate, well above the 11.0% yield we consider fair. The verdict is "attractive": the share is interesting for income-oriented holders, but a further decline in profit could jeopardise the payouts.
Open the company's financial profile BSPB →
See also: market overview · valuation map · stock screeners