B2B-RTS: double-digit profit growth, but the margin is compressing and the dividend already trades above fair value
On 25 November B2B-RTS reported results for the nine months of 2026. Revenue rose 15.8% year on year to RUB 7,862.9 mn, EBITDA – by 16.5% to RUB 4,062.4 mn, net profit – by 11.5% to RUB 2,883.0 mn. The EBITDA margin held at 51.7%, but the net margin slipped to 36.7% from 38.1%. The company sits on a net cash position of RUB 1,965.2 mn and pays generous dividends; at a P/E LTM of 7.4 and a dividend yield of 12.7% the share looks rather attractive than not – but only if profit stops lagging revenue.
Key takeaways
— Revenue rose 15.8% over nine months, the fastest growth line in the report
— EBITDA added 16.5%, but the margin stayed at 51.7% – cost growth ate the entire operating leverage
— Net profit grew 11.5%, lagging revenue, as the net margin slipped to 36.7% from 38.1%
— The company holds a net cash position of RUB 1,965.2 mn, with negative debt load
— The 2026 dividend of RUB 16.28 per share yields 12.7% – above the 12.0% we consider fair for the name
— Our estimate for the current year's dividend is RUB 13.62 per share, or 10.6% yield, below last year's level
— At a P/E LTM of 7.4 and EV/EBITDA LTM of 4.9 the share is modestly valued, and the portal model implies +29% upside
Attractiveness
Key figures, RUB bn
| Metric | 9M 2025 | 9M 2026 | Change |
|---|---|---|---|
| Revenue | 6.79 | 7.86 | +15.8% |
| EBITDA | 3.49 | 4.06 | +16.5% |
| Operating profit | 3.20 | 3.75 | +17.1% |
| Net profit | 2.58 | 2.88 | +11.5% |
| EBITDA margin | 51.4% | 51.7% | +0.3 pp |
| Net margin | 38.1% | 36.7% | -1.4 pp |
Revenue rose 15.8% over nine months, the fastest growth line in the report
Revenue for the nine months of 2026 came in at RUB 7,862.9 mn, 15.8% more than a year earlier. That is the highest growth rate among the key lines of the report: EBITDA added 16.5%, while net profit grew only 11.5%.
There is no separate quarterly disclosure for the third quarter in the facts, so intra-period dynamics cannot be relied upon. The only quarterly reference point is the first quarter of 2026 with revenue growth of 20.6% year on year, but it belongs to a different period and does not describe the current trend.
What matters more for a holder is that revenue is growing faster than profit, meaning the company is expanding turnover at the cost of some deterioration in profitability. The question is whether this is temporary or the new normal.
EBITDA added 16.5%, but the margin stayed at 51.7% – cost growth ate the entire operating leverage
EBITDA for the nine months of 2026 reached RUB 4,062.4 mn, up 16.5% year on year. The EBITDA margin was 51.7% against 51.4% a year earlier – a symbolic gain of just over a third of a percentage point.
Formally the company held the margin but did not improve it, even though revenue grew at a double-digit pace. This means operating costs increased almost proportionally to revenue, and the scale effect did not materialise.
For an investor this is a signal that further revenue growth alone does not guarantee profit growth. If costs continue to rise at the same pace, the margin will stay on a plateau and profit will lag turnover.
Net profit grew 11.5%, lagging revenue, as the net margin slipped to 36.7% from 38.1%
Net profit for the nine months of 2026 was RUB 2,883.0 mn, 11.5% more than a year earlier. That is the slowest growth rate among the three key lines – revenue added 15.8%, EBITDA – 16.5%.
The net margin slipped to 36.7% from 38.1% a year earlier. The cause is not operating efficiency, which held its level, but what lies below operating profit: likely growth in interest expenses or other items not disclosed in the facts.
The gap between EBITDA growth and net profit growth – 5 percentage points – indicates that pressure on profit comes from the financial block rather than from core operations. For a holder this matters: if interest rates stay high, profit will continue to lag operating results.
The company holds a net cash position of RUB 1,965.2 mn, with negative debt load
Net debt as of 30 September 2026 was minus RUB 1,965.2 mn, meaning the company has a net cash position. The net debt to EBITDA LTM ratio is minus 0.44, meaning cash exceeds the entire annual operating cash flow.
Over the six months since 30 June 2026 net debt changed from minus RUB 2.1 bn to minus RUB 2.0 bn, so the cash cushion shrank by RUB 0.1 bn. Over the twelve months since 31 December 2025 net debt changed from minus RUB 1.0 bn to minus RUB 2.0 bn, so the cash position strengthened by RUB 0.9 bn.
Negative debt load is a strength of the company. It provides a margin of safety and allows high dividends to be maintained even with a temporary deterioration in profit. However, the direction of change over the past six months – a shrinking cash cushion – is worth keeping an eye on.
The 2026 dividend of RUB 16.28 per share yields 12.7% – above the 12.0% we consider fair for the name
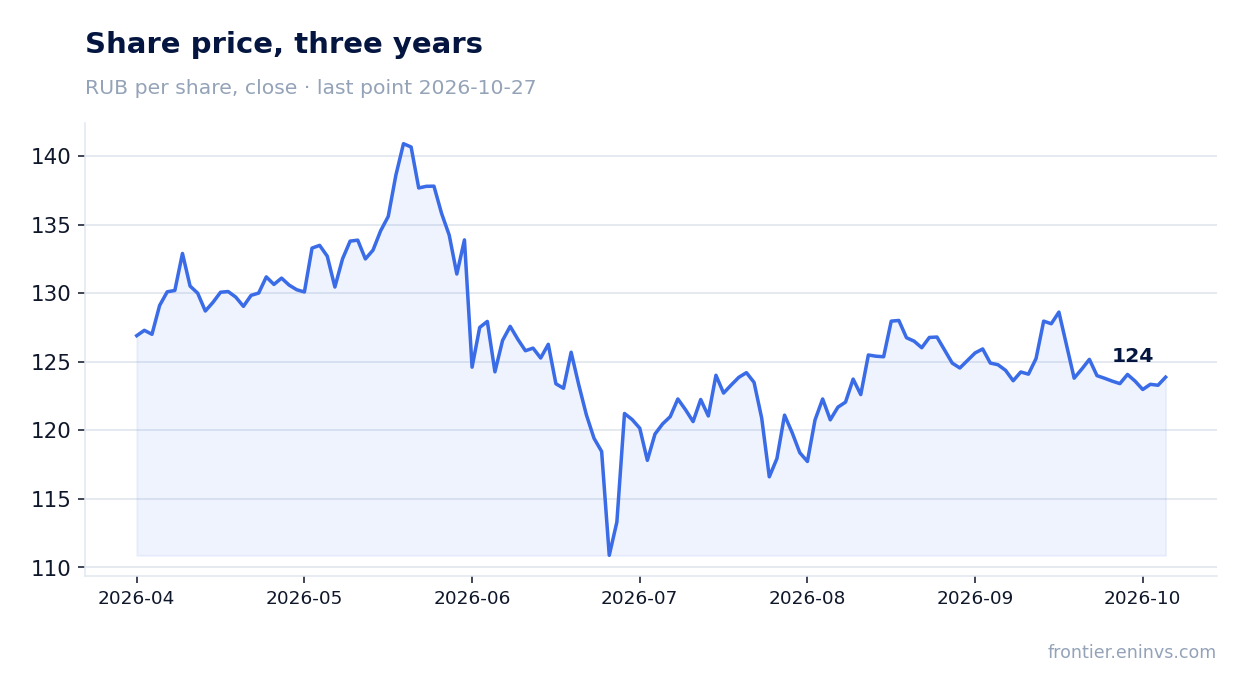
Over the last twelve months the company paid RUB 16.28 per share; at the 2026 ex-date this payment yielded 12.9% at a price of RUB 126.2. The current trailing dividend yield is 12.7%.
Our estimate for the current financial year's dividend is RUB 13.62 per share, implying a 10.6% yield at the current price. This is our own calculation: we take net profit for the last twelve months and multiply by 0.78 – the share of profit paid out last year. The board decides, and the estimate may change.
The 12.7% yield exceeds the 12.0% level we consider fair for the name and is noticeably below the 14.0% key rate. At the same time, our estimate of the future dividend implies a lower payout, which could reduce the yield to 10.6%.
The dividend could be smaller if profit continues to lag revenue or if the company decides to allocate more funds to development. Negative net debt provides room for manoeuvre, but rising interest expenses could constrain profit and therefore the payout base.
Our estimate for the current year's dividend is RUB 13.62 per share, or 10.6% yield, below last year's level
Our estimate for the current financial year's dividend is RUB 13.62 per share. It is built on net profit for the last twelve months and a payout ratio of 0.78, which the company actually used last year. This is our calculation, not a board decision.
At the current price such a payment yields 10.6% – below last year's 12.7% and below the 12.0% we consider fair for the name. The decline is because net profit over the last twelve months was lower than last year's base, while we kept the payout ratio unchanged.
If net profit for the nine months of 2026 – RUB 2,883.0 mn – proves representative for the full year, the dividend may come closer to our estimate than to last year's level. However, the company has a net cash position and could afford to pay more if the board decides to support the yield.
For a holder the key question is not the size of the past payment but the company's ability to sustain profit. If the net margin continues to decline, the dividend will have to be either cut or funded from the accumulated cash cushion.
At a P/E LTM of 7.4 and EV/EBITDA LTM of 4.9 the share is modestly valued, and the portal model implies +29% upside
According to our data, P/E LTM is 7.4 and EV/EBITDA LTM is 4.9. These are low multiples for a company with an EBITDA margin above 50% and a net cash position. For comparison with its own history we do not have a three-year average in the facts, so we cannot say whether the current level is above or below its historical range.
The portal model, which compares EBITDA growth with a target multiple and market capitalisation, implies upside to fair value of +29%. This is our own model estimate, not a market consensus and not a target price.
Market capitalisation is RUB 22,964.8 mn. With a net cash position of RUB 1,965.2 mn and EBITDA LTM of RUB 4,492.2 mn, the company looks undervalued relative to its ability to generate profit. However, the low multiple may reflect the risk of profit decline that we see in the report.
The share is held in our live model strategies on the portal – RU Growth-potential (quality). This is a fact, not an argument for the verdict: inclusion follows from the strategy's screen.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 23.0 bn ₽ |
| P/E (LTM) | 7.4 |
| EV/EBITDA (LTM) | 4.9 |
| P/B | 6.24 |
| Net debt / EBITDA (LTM) | -0.44 |
| ROE | 103.8% |
| Dividend yield (12m) | 12.7% |
Bottom line
The strong side of the report is double-digit growth in revenue and EBITDA while keeping the margin above 50%, plus a net cash position of RUB 1,965.2 mn that provides a margin of safety. The weak side is that net profit grew only 11.5%, the net margin slipped to 36.7% from 38.1%, and the gap between operating and net results points to pressure from financial expenses. The dividend of RUB 16.28 per share yields 12.7%, but our estimate for the next payout is RUB 13.62, or 10.6%, below the fair level. At a P/E LTM of 7.4 and portal model upside of +29% the share looks rather attractive, but the key question for a holder is whether profit, and with it the dividend, will hold.
Open the company's financial profile BTBR →
See also: market overview · valuation map · stock screeners