DOM.RF: quarterly profit up 22.2%, but business growth slowed by nearly half
On 28 September DOM.RF reported results for the second quarter of 2026. Net interest income reached RUB 52,154 mn, up 29.6% year on year, while net profit came in at RUB 28,705 mn (+22.2%). The growth rate of net interest income decelerated from 42.6% in the first quarter, and net profit as a share of net interest income fell to 55.0% from 58.3% a year earlier. At the current price the share looks attractive: the dividend yield of 12.2% is well above the 11.6% we consider fair, and the portal's model implies 36% upside.
Key takeaways
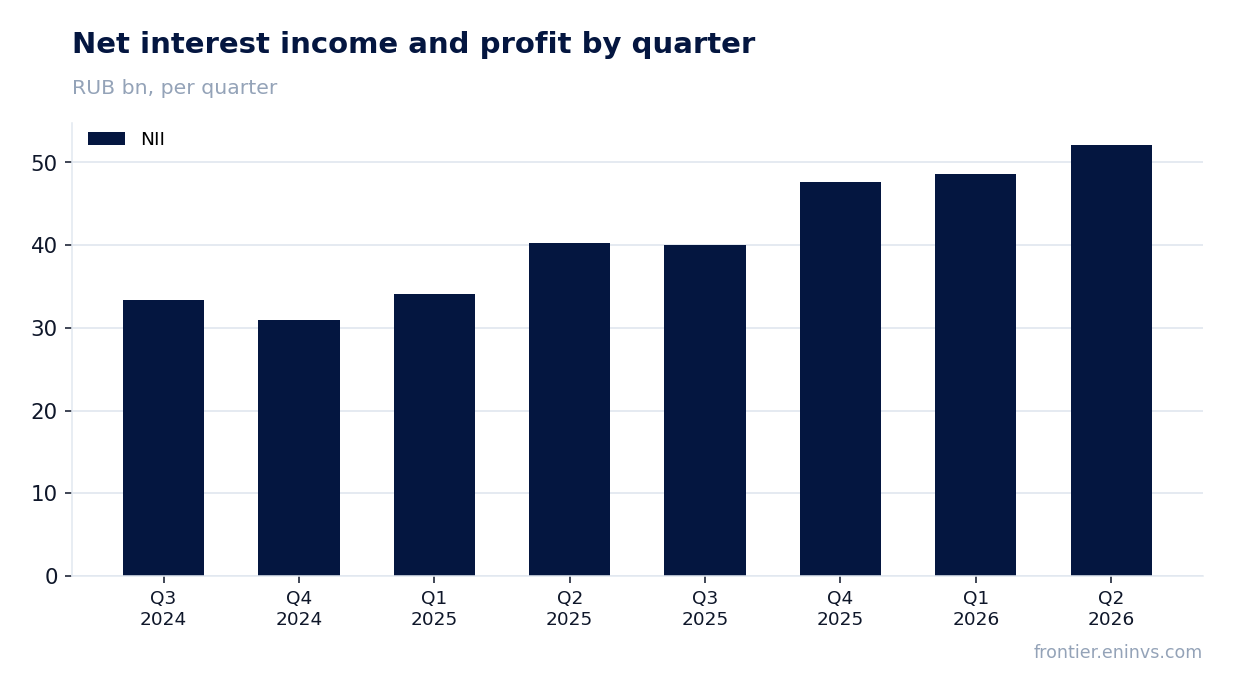
— Net interest income grew 29.6%, but markedly slower than a quarter earlier
— Fee and commission income added more than half to the year-ago level
— Net profit as a share of net interest income fell to 55.0% from 58.3%
— The 12.2% dividend yield exceeds the 11.6% we consider fair
— The portal's model implies 36% upside for the share
— The stock trades at a P/E of 3.4 with a return on equity of 23.9%
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | 40.2 | 52.2 | +29.6% |
| Net profit | 23.5 | 28.7 | +22.2% |
| Capex | 0.80 | 5.19 | +550.9% |
| Net margin | 58.3% | 55.0% | -3.3 pp |
Net interest income grew 29.6%, but markedly slower than a quarter earlier
Net interest income in the second quarter of 2026 reached RUB 52,154 mn, up 29.6% year on year. This is the main revenue source for DOM.RF, and its absolute level was the highest in recent quarters.
However, the growth rate decelerated: in the first quarter of 2026 it was 42.6%. The slowdown reflects both the high base of last year and a general cooling of credit activity. For a bank focused on mortgages and housing construction projects, this is a sensitive signal.
The comparison with the previous quarter shows that net interest income continues to grow, but no longer accelerates. The report does not disclose how much of the slowdown is due to the key rate and how much to lending volumes. For an investor, the fact itself matters: the business is growing, but the pace is easing.
Fee and commission income added more than half to the year-ago level
Fee and commission income in the second quarter of 2026 amounted to RUB 15,646 mn versus RUB 6,128 mn a year earlier. That is a 2.6-fold increase, significantly outpacing the dynamics of net interest income.
The share of fees in total income is growing: a year ago they accounted for about 15% of net interest income, now almost 30%. This is a positive shift, as fee income is less sensitive to interest rates and more stable.
The report does not detail which fees drove this increase. However, the very fact of a substantial rise in the fee component indicates diversification of revenue sources. For a bank dependent on mortgage lending, this reduces vulnerability to rate cycles.
Net profit as a share of net interest income fell to 55.0% from 58.3%
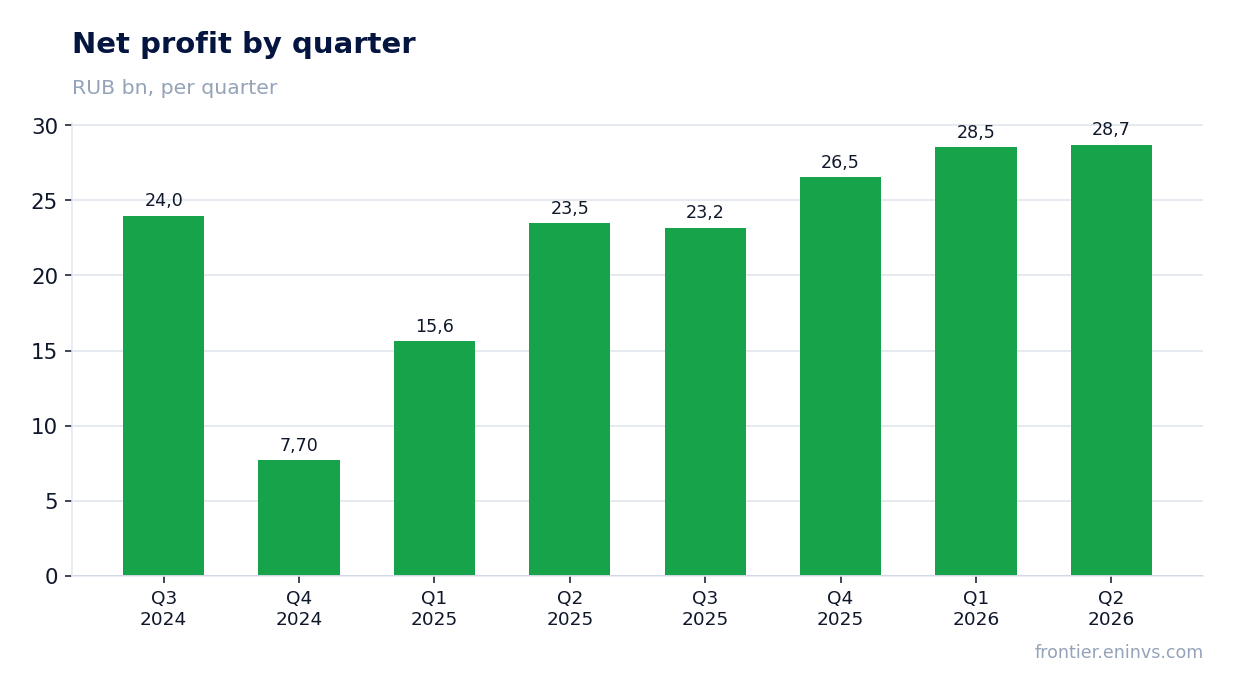
Net profit in the second quarter of 2026 reached RUB 28,705 mn, up 22.2% year on year. However, its share in net interest income fell to 55.0% from 58.3% a year earlier.
This means that expenses or provisions grew faster than income. The report does not disclose the cost structure, but a 3.3 percentage point decline in profit conversion is a notable signal. The bank may have increased provisioning or operating expenses.
For an investor, it is important that profit is growing, but the efficiency of its generation from core income is declining. If the trend continues, it could limit the ability to sustain high dividends without capital growth.
The 12.2% dividend yield exceeds the 11.6% we consider fair
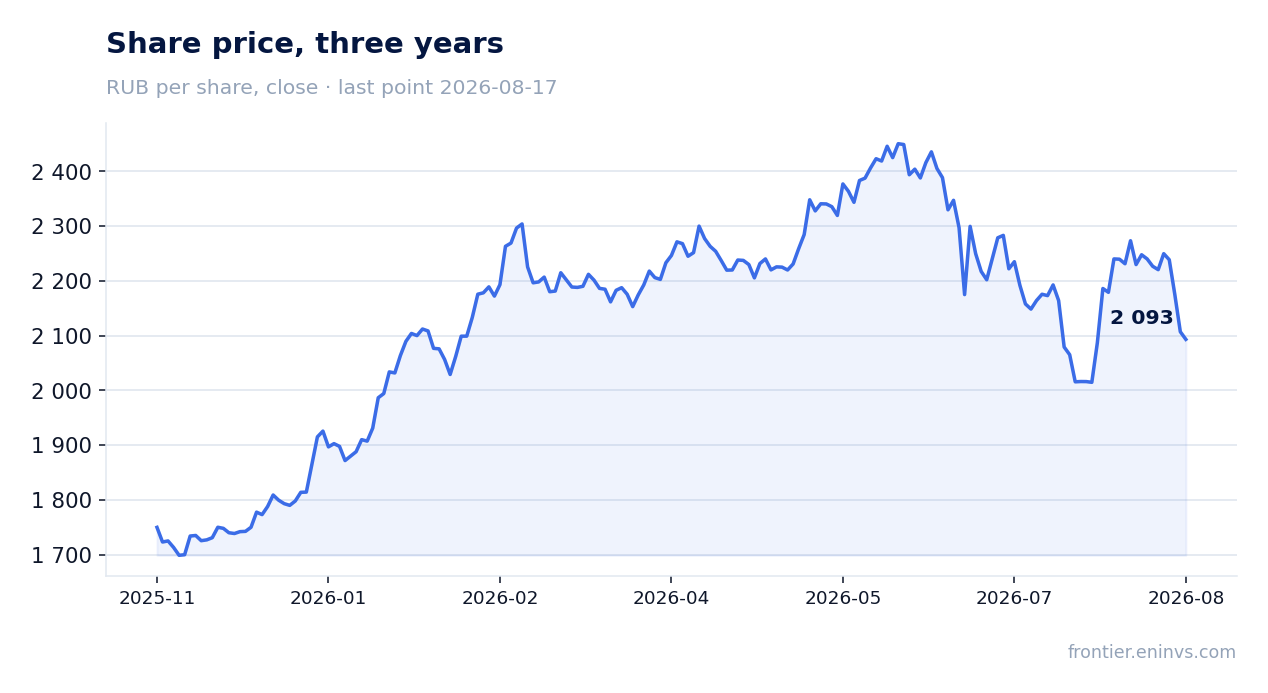
Over the last 12 months DOM.RF paid RUB 246.88 per share, which at the current price gives a dividend yield of 12.2%. This is above the 11.6% we consider fair and significantly above the key rate of 14.0%.
Our model estimates the next dividend at RUB 283.12 per share, corresponding to a forward yield of 13.9%. The forecast relies on a payout ratio of 0.5 of profit. If annual profit falls short of expectations, the dividend could be lower.
Historical yield is also high: in 2026 the payout was RUB 246.88 at an ex-date price of RUB 2,065.1, giving 12.0%. The current yield is close to that level, confirming the stability of the dividend policy.
A risk to the dividend is a decline in profit or an increase in capital expenditures. In the report, capital expenditures for the quarter were RUB 5,194 mn, higher than a year earlier. If investments grow, this could limit payouts.
The portal's model implies 36% upside for the share
According to the portal's model, the fair value of DOM.RF shares is 36% above the current price. This estimate is based on comparing return on equity (23.9%) and the price-to-book ratio. The model is not a market consensus and reflects our own view.
The stock trades at a P/E of 3.4 for the last 12 months. This is a low multiple, which may reflect both banking sector risks and expectations of slowing growth. At the same time, ROE of 23.9% remains high.
The 36% upside suggests that the market underestimates the sustainability of profit and dividend payments. However, if the slowdown in net interest income continues, the multiple may remain low.
The stock trades at a P/E of 3.4 with a return on equity of 23.9%
The P/E multiple for the last 12 months is 3.4. For comparison, return on equity is 23.9%. This combination means the market values the bank very cheaply relative to its ability to generate profit.
Such a low P/E may be related to concerns about asset quality or slowing growth. However, current results do not show a sharp deterioration: profit is growing, albeit slower than income.
The report does not disclose capital dynamics, but with ROE of 23.9% and a payout ratio of 0.5, the bank can sustain growth without a significant capital increase. This makes the stock interesting for income-oriented investors.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 369 bn ₽ |
| P/E (LTM) | 3.4 |
| P/B | 0.78 |
| ROE | 23.9% |
| Dividend yield (12m) | 12.2% |
Bottom line
Bottom line: DOM.RF delivered 22.2% profit growth and record quarterly net interest income, but growth rates decelerated and the efficiency of converting income into profit declined. The dividend yield of 12.2% and forward estimate of 13.9% make the stock attractive for income-oriented investors, especially given the fair yield of 11.6%. The portal's model points to 36% upside, confirming undervaluation. However, to maintain its appeal, the bank needs to stabilise income growth and control expenses.
Open the company's financial profile DOMRF →
See also: market overview · valuation map · stock screeners