DOM.RF: Q3 2026 profit rose 2.7x, and whether that jump repeats is the whole question
On 30 September DOM.RF released its results for the third quarter of 2026. Net profit came in at RUB 62,280 mn, up 168.8% year on year, with capital expenditure of RUB 2,264 mn; over the trailing twelve months profit accumulated to RUB 146,052 mn and net interest income to RUB 200,400 mn. At 2.63 times trailing earnings and a 16.8% return on equity the share looks undervalued, while an 11.5% trailing dividend yield keeps holders interested, so the stock appears rather attractive, although the durability of the quarterly profit jump is still to be confirmed.
Key takeaways
— Q3 2026 profit rose 168.8% year on year to RUB 62,280 mn, the strongest quarter in the available history
— Trailing twelve-month net interest income reached RUB 200,400 mn and remains the main source of profit
— A 16.8% return on equity at 2.63 times earnings leaves room to fair value
— The dividend over the last twelve months was RUB 246.88 per share, a yield of 11.5%
— Our estimate for the next payout is RUB 297.66 per share, a 13.9% yield on the current price
— Capital expenditure of RUB 2,264 mn in the quarter is small against profit and does not constrain payouts
— On the portal's model the share has 50% upside to fair value
Attractiveness
Key figures, RUB bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net interest income | 52.0 | — | — |
| Net profit | 23.2 | 62.3 | +168.8% |
| Capex | 1.55 | 2.26 | +45.8% |
| Net margin | 44.6% | — | — |
Q3 2026 profit rose 168.8% year on year to RUB 62,280 mn, the strongest quarter in the available history
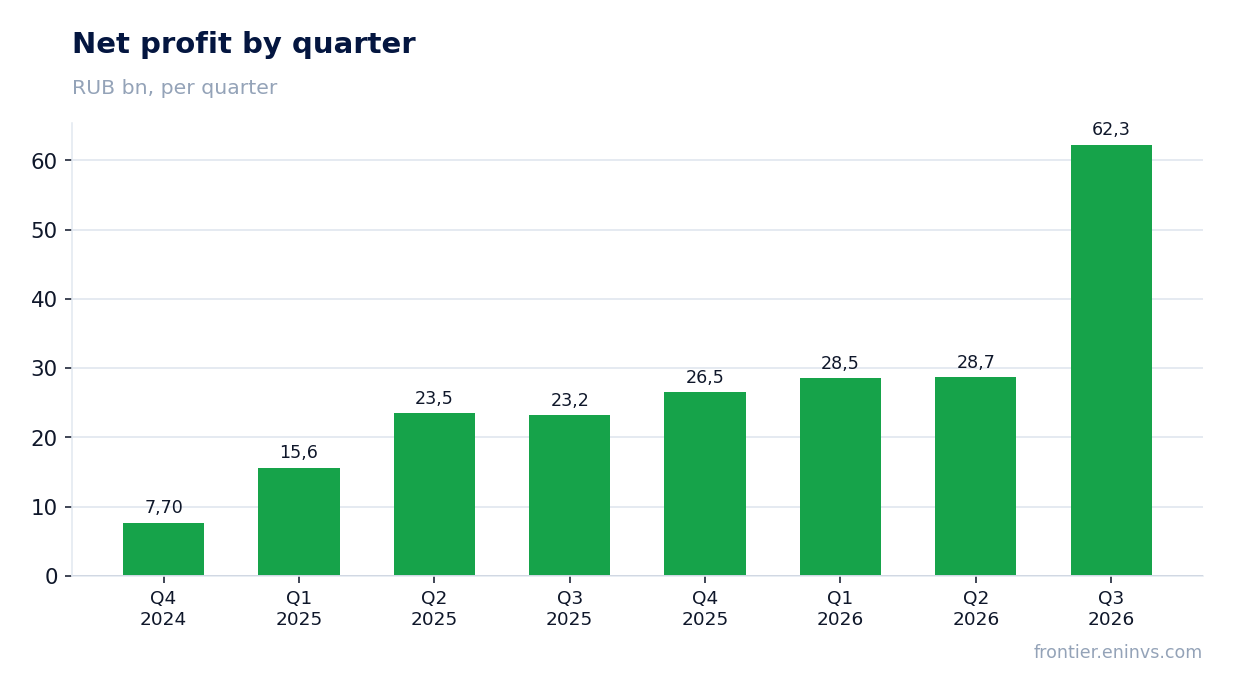
DOM.RF's net profit for the third quarter of 2026 was RUB 62,280 mn against RUB 23,168 mn a year earlier, a rise of 168.8%. This is the highest quarterly result in the available history: the previous peak was RUB 28,705 mn in the second quarter of 2026, so the new level is more than double it.
The gap cannot be explained by the interest business alone. Trailing twelve-month net interest income is RUB 200,400 mn and forms the profit base, but it does not produce a 2.7-fold jump in a single quarter. There was therefore a sizeable one-off contribution in the reported quarter whose nature the disclosed data do not specify; that is why the durability of the result is the main question for the report.
For a holder this means the quarter's profit cannot be mechanically carried into future periods. If the one-off does not repeat, profit returns to a level closer to RUB 28–30 bn a quarter, which is still above last year's figures but changes the assessment of the annual result.
Trailing twelve-month net interest income reached RUB 200,400 mn and remains the main source of profit
Over the last twelve months DOM.RF's net interest income was RUB 200,400 mn. This is the group's main revenue stream, and it noticeably exceeds the profit accumulated over the same period of RUB 146,052 mn, meaning the interest business covers costs and generates profit with a margin.
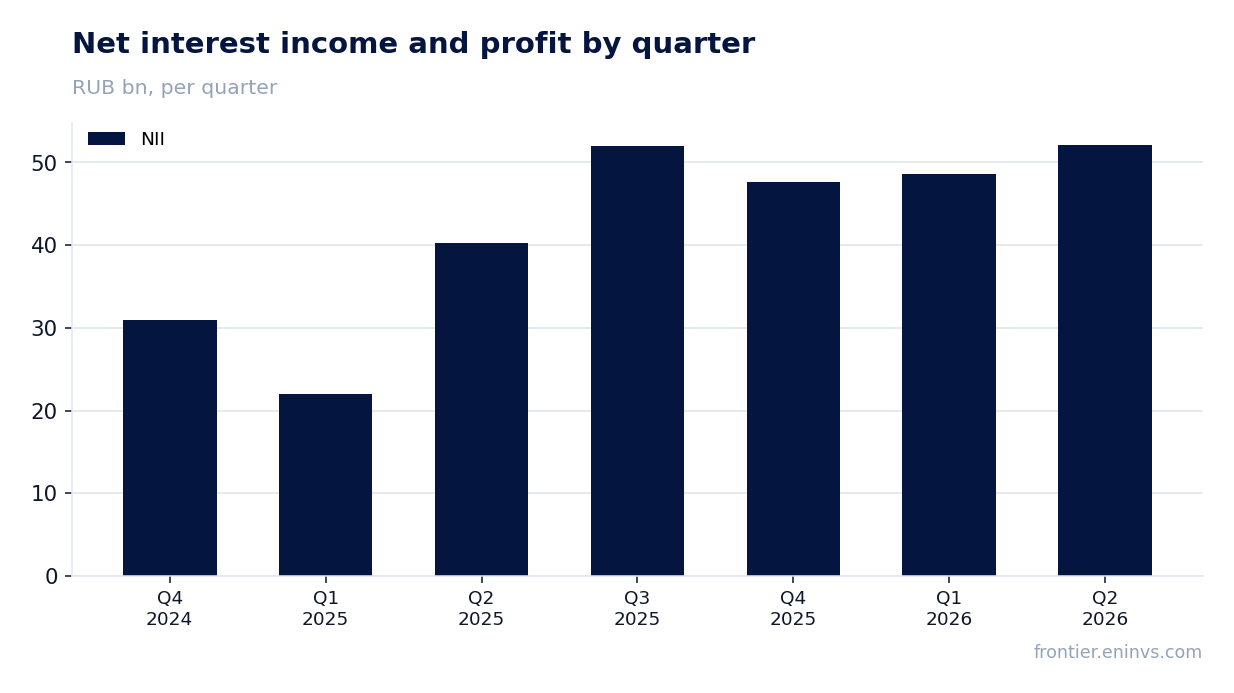
The quarterly path of net interest income in the available history is positive: from RUB 22,042 mn in the first quarter of 2025 to RUB 52,154 mn in the second quarter of 2026. The growth was sequential, without dips, and this is the stable part of the result, unlike the one-off contribution to third-quarter profit.
For valuing the share it is this base that matters: it determines what the company can earn in a normal regime. With the key rate at 14.0% the interest margin remains wide, and that supports both profit and the dividend base.
A 16.8% return on equity at 2.63 times earnings leaves room to fair value
DOM.RF's return on equity is 16.8% and the share trades at 2.63 times trailing twelve-month earnings. The combination of high return on capital and a low multiple is the main argument for the stock: the market pays less for a ruble of profit than the company earns on a ruble of capital.
On the portal's model, which sets return on equity against price to book, the share has +50% upside to fair value. This is our own estimate, not a market consensus and not a target price; it shows how far the current price diverges from the profitability of the business.
The caveat is that the calculation rests on trailing twelve-month profit, which already includes the strong third quarter. If its one-off contribution does not repeat, the profit base falls and the multiple turns out above 2.63. The room to fair value remains, but it becomes smaller.
The dividend over the last twelve months was RUB 246.88 per share, a yield of 11.5%
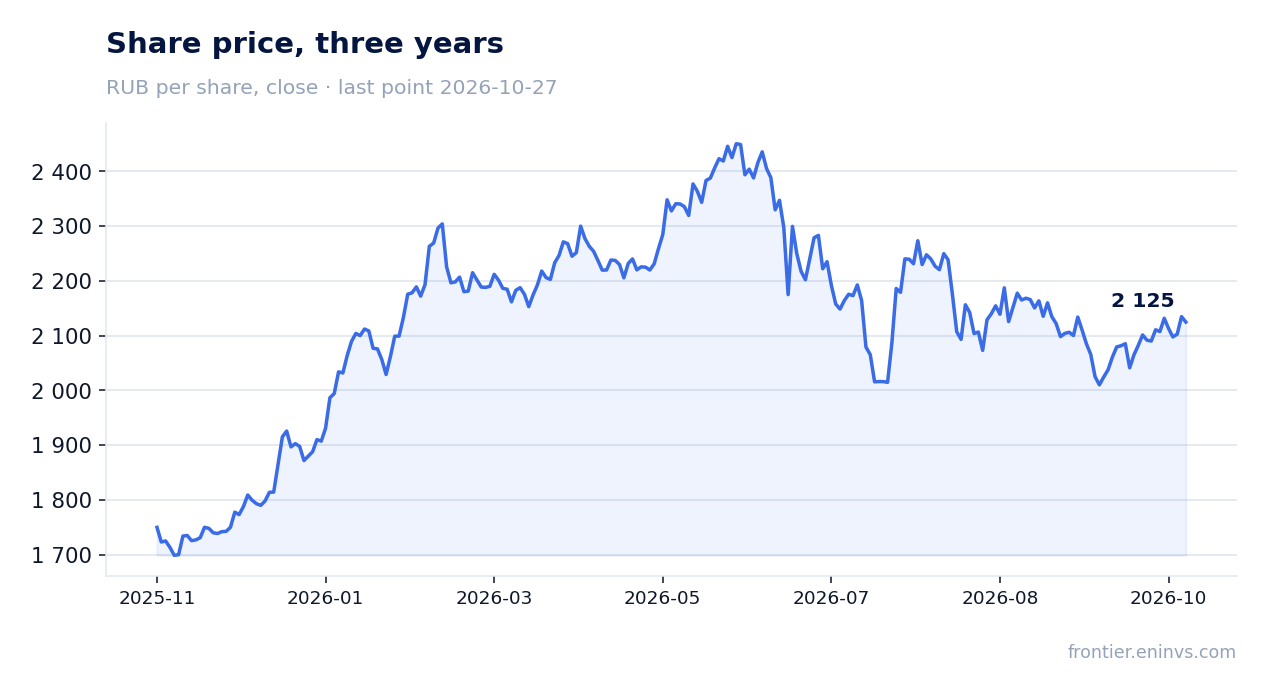
Over the last twelve months DOM.RF paid RUB 246.88 per share; at the ex-date price of RUB 2,065.1 that is a 12.0% yield, and at the current price 11.5%. The payout for 2026 has already been made, and for a holder it is the main source of return on invested capital.
Our estimate for the next payout is RUB 297.66 per share, which at the current price gives 13.9%. The estimate rests on a payout ratio of about half of profit; with trailing twelve-month profit of RUB 146,052 mn such a ratio provides a base sufficient for a payout of that size.
A yield of 11.5–13.9% is comparable to the 14.0% key rate and close to the 12.0% level we consider fair for this name. In other words, the market prices the dividend almost neutrally to the rate: there is almost no risk premium in the price, but no discount either.
The payout would be smaller if the one-off contribution of the third quarter does not repeat and the profit base falls, or if the payout ratio is reduced. With a ratio of about half of profit and profit excluding the one-off quarter, the dividend could come in below our estimate, and the yield would move towards 10–11%.
Capital expenditure of RUB 2,264 mn in the quarter is small against profit and does not constrain payouts
DOM.RF's capital expenditure in the third quarter of 2026 was RUB 2,264 mn. Against profit of RUB 62,280 mn this is a small figure, about 3.6% of the quarterly result, and it does not pressure the dividend base.
In earlier quarters spending was higher: RUB 5,194 mn in the second quarter of 2026 and RUB 3,580 mn in the first. The decline in the reported quarter means the company did not step up investment and channelled what it earned into profit and payouts.
For a banking model this is a normal picture: capital expenditure is not the main constraint, capital adequacy is. The capex-to-dividend link is therefore weaker here than for industrial companies, and the payout depends above all on profit.
On the portal's model the share has 50% upside to fair value
On the portal's model, which sets return on equity against price to book, the share has +50% upside to fair value. With a market capitalisation of RUB 384,476 mn and trailing twelve-month profit of RUB 146,052 mn, the market values the business at 2.63 times annual earnings.
That valuation is below what a 16.8% return on capital would imply: at a sustained level of profitability the market usually pays more for earnings. The gap is what the model captures.
The room, however, rests on profit that includes the strong third quarter. If profit returns to a normal level, fair value shifts down and the 50% upside shrinks. It is the durability of profit, not the multiple itself, that will decide whether this room is realised.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 384 bn ₽ |
| P/E (LTM) | 2.6 |
| P/B | 0.82 |
| ROE | 16.8% |
| Dividend yield (12m) | 11.5% |
Bottom line
The strength of the report remains the interest business: trailing twelve-month net interest income of RUB 200,400 mn and a 16.8% return on equity form a stable base that does not depend on a single quarter. The weak spot is third-quarter profit of RUB 62,280 mn: the 168.8% rise almost certainly contains a one-off contribution, and without it the result returns to RUB 28–30 bn a quarter. The dividend of RUB 246.88 per share and our RUB 297.66 estimate give 11.5–13.9% yields, close to the 14.0% key rate and to the 12.0% level we consider fair. The question for a holder now is whether the one-off repeats and whether the company holds the profit base; at 2.63 times earnings and with 50% model upside the share looks rather attractive, but without confirmation of profit durability in the next report that conclusion will remain open.
Open the company's financial profile DOMRF →
See also: market overview · valuation map · stock screeners