Family mortgage from 1 October: 10-12% for families with one child. What this means for developers
On 24 September the Ministry of Finance approved new terms for the family mortgage. They apply to contracts signed from 1 October 2026. The single 6% rate is going away. The rate and the loan limit now depend on the number of children and the region: from 2% for families with five children to 10% for a family with one child in the regions and 12% in Moscow, St Petersburg and their regions. Source: the [Ministry of Finance release](https://minfin.gov.ru/ru/press-center/?id_4=40636-utverzhdeny_izmeneniya_v_programmu_semeinaya_ipoteka).
For developers this means a 14-33% hit to new-build sales across the market, and it hits the mass segment of Moscow and the Moscow region hardest. For the shares the news is largely priced in; the main risk now is fourth-quarter sales.
- A family with one child pays 46% more in the regions and 72% more in the capitals. At an unchanged payment, the bank will approve a loan 32-42% smaller.
- Such families make up 40% to 70% of family mortgage buyers. The low estimate comes from Samolet, the high one from ERZ.
- September will be strong, October-December weak. Buyers are rushing to close deals at 6% before 1 October, and third-quarter reports will show this.
- Samolet is more vulnerable than the others: mass-market housing in the Moscow region, mortgages in most deals, large bond repayments in January-February 2027.
- The market reacted calmly, within 3% over two days. Since May Samolet is down 56%, Etalon 35%, LSR 21%, against minus 13% for the index.
The rate now depends on the number of children, and the subsidy is capped at 15 years
Until 30 September the terms are the same for everyone: 6% a year, a limit of RUB 6 mn in the regions and RUB 12 mn in Moscow, St Petersburg, and the Moscow and Leningrad regions. At least one child must be under 7.
From 1 October a scale is introduced. In the regions: one child – 10% and up to RUB 6 mn, two – 8% and up to RUB 8 mn, three – 6% and up to RUB 10 mn, four – 4%, five or more – 2%, with a limit of RUB 10 mn in both cases. In the four capital regions rates are 2 pp higher and limits larger: 12% and RUB 12 mn for one child, 10% and RUB 15 mn for two, and 8%, 6% and 4% with an RUB 18 mn limit for large families.
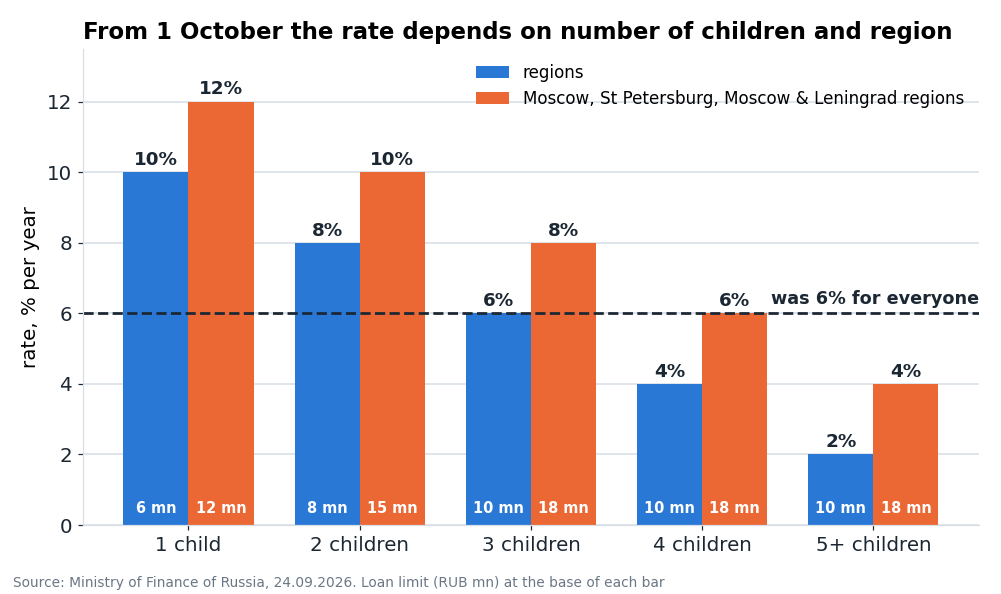
Two more changes. The subsidy to the bank is paid for no longer than 15 years. What the borrower's rate will be after 15 years on a 30-year loan, the Ministry of Finance did not specify. Loans for building a private house and buying a plot for it remain at 6% for everyone. Loans already issued are not affected.
A family with one child loses a third of its purchasing power
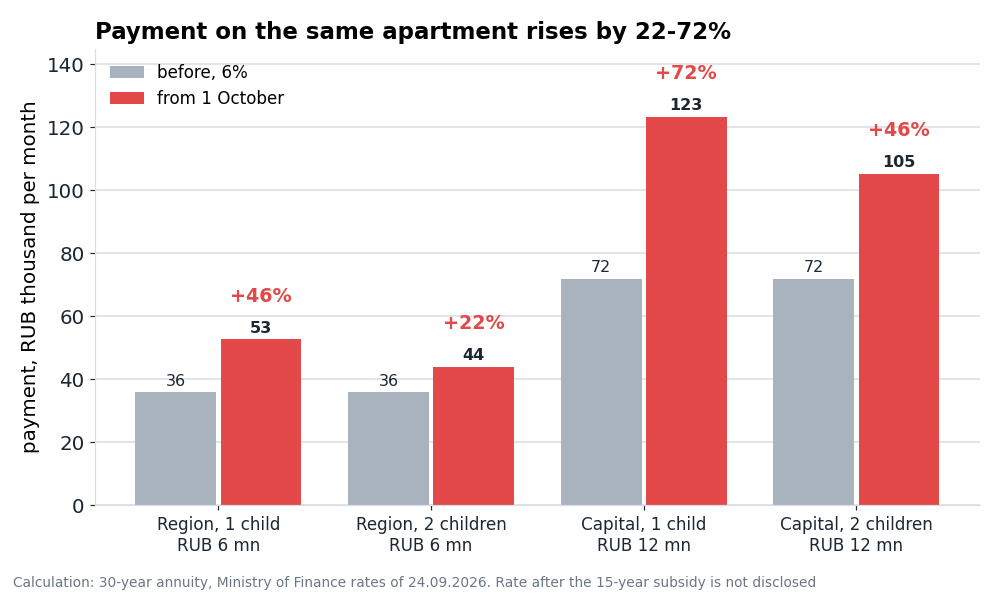
Take a 30-year loan. In a region RUB 6 mn at 6% cost RUB 35.97 thousand a month; at 10% it is RUB 52.65 thousand, 46% more. In Moscow RUB 12 mn at 12% instead of 6% means RUB 123.4 thousand instead of 71.9 thousand, up 72%. A family with two children in a region pays 22% more on the same loan, in the capital 46%.
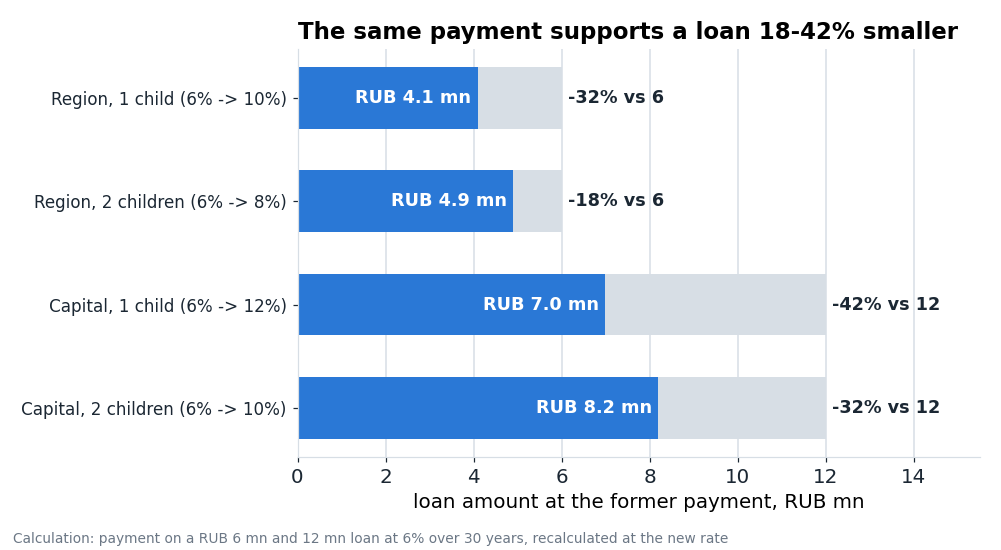
A bank approves a loan by income, so the reverse calculation matters more. A family that could carry a payment of RUB 36 thousand will get not RUB 6 mn but RUB 4.1 mn at 10%. In the capital a payment of RUB 72 thousand at 12% supports RUB 7 mn instead of 12. Such a family will have to buy a smaller or cheaper apartment, or add its own money.
At the same time 10-12% is still below the market. The Bank of Russia key rate is [14%](https://www.cbr.ru/press/keypr/), and a market mortgage as of 22 September costs about 18.7% on average. Demand from families with one child will not vanish, but it will shrink in amount and in the number of deals.
The new-build market may lose 14-33% of sales
The family mortgage is the main source of demand for new builds. In August RUB 137.2 bn was issued under it, more than half of all mortgage issuance. The key question is what share of these buyers is raising one child. Estimates differ here.
- ERZ: about 70% of new-build buyers under the family mortgage are families with one child, about 25% have two, about 5% are large families. Sales to the first group will fall by 2-3 times, and the whole new-build market by roughly 20% ([RIA Realty](https://realty.ria.ru/20260924/erz-2120075535.html)).
- Samolet: 40-45% of the company's family mortgage deals are families with one child (The Moscow Times).
A back-of-the-envelope calculation. By ERZ's estimate, the family mortgage accounts for about 70% of new-build sales. If the share of families with one child among its borrowers is from 40% to 70%, and their demand falls by half or to a third, the market loses from 14% to 33% of sales. The upper bound does not take into account that large families will receive a lower rate and a bigger limit. ERZ does account for this increase and gets minus 20%, within our range.
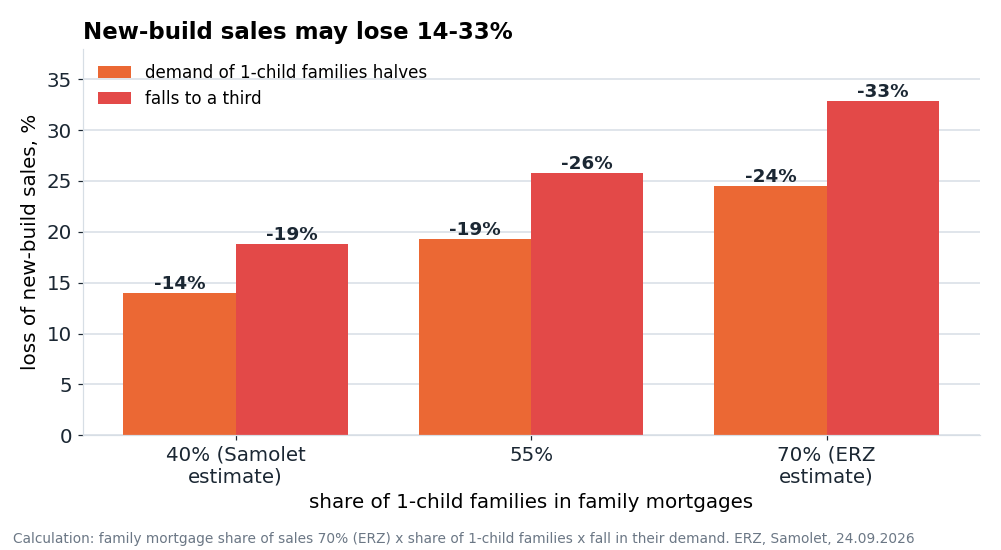
The blow will come unevenly. The last week of September is a window for deals at 6%, and the third quarter will come out strong for developers. The demand failure will show in the October-December data. It already happened at the start of 2026: before the tightening of rules from 1 February (one subsidised mortgage per family), sales under equity participation agreements picked up noticeably.
Mass-market housing in Moscow and the Moscow region suffers most
For a developer sales are not only revenue. Buyers' money accumulates in escrow accounts, and the more of it there is, the cheaper the bank gives project financing. Weak sales mean more debt at the full rate and pressure on margins. The second channel is discounts and rate subsidies from their own pocket, with which developers will try to retain buyers with one child.
- Samolet – the most vulnerable. A mass segment, with the main market in Moscow and the Moscow region, where the rate for a family with one child is now 12%. According to the Investor Day in January, mortgages were in 62-72% of deals. The company itself rated its 1H2026 sales as worse than the market, and the net debt to EBITDA ratio is about 4. In January-February 2027 the repayment of P13 and the put offer on P11 fall due, about RUB 15.7 bn after buybacks at past offers (RUB 44.5 bn for the full issue volumes). Reports of weak fourth-quarter sales will come out in exactly these months.
- PIK – also a capital mass segment, so the sales risk is similar. But the news is almost invisible in PIK shares: the stock has stood still since May at around RUB 536-540.
- LSR – St Petersburg and Moscow, with a mortgage share of sales of 60% in 1H2026. Both of the company's key markets fall under the capital scale.
- Etalon – more business class and the regions. In expensive apartments the family mortgage covers a smaller part of the purchase, so dependence on it is lower. For Etalon the debt situation matters more than the programme parameters.
Large families receive a bigger limit: in the capital a family with three children can borrow RUB 18 mn at 8% instead of RUB 12 mn at 6%, and with four children RUB 18 mn at the same 6%. But these are about 5% of buyers, and this will not close the failure in the main mass.
Developer shares priced in the news in advance
The programme parameters had been discussed since spring, and the reform was originally due to start on 1 July. When it was postponed to 1 October on 29 June, Samolet rose 12% in a day and PIK 7%. The publication of the parameters itself on 24 September passed quietly. Over 24-25 September Samolet fell 2.1%, LSR 2.1%, Etalon 2.7%, and PIK rose 0.4%.
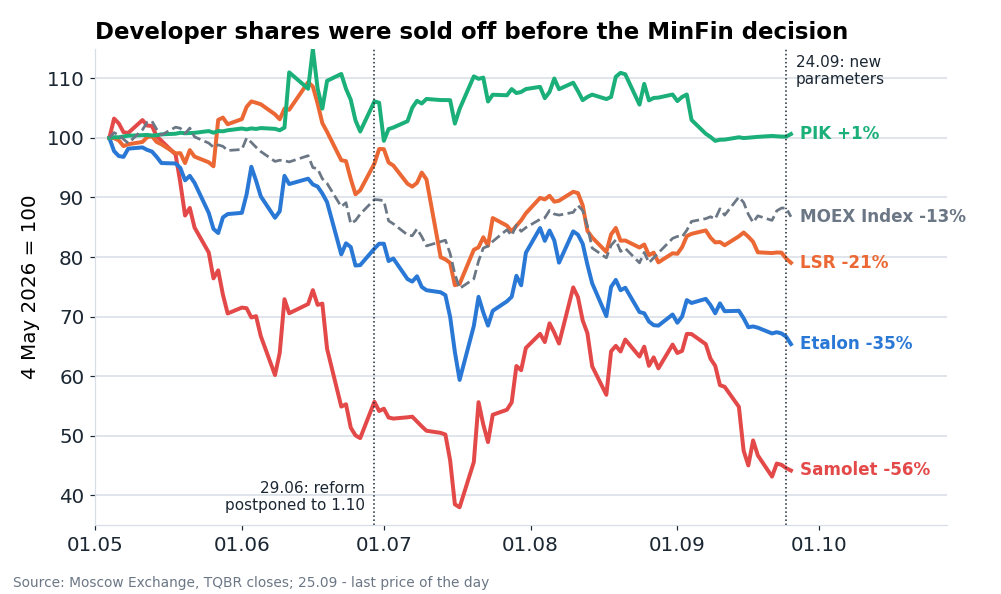
The market is already pricing in weak sales. The new risk for shares and bonds is if the fall in October-December proves deeper than 20%. The first data on this will appear in November: October mortgage issuance from the Bank of Russia and DOM.RF, and sales under equity participation agreements from Rosreestr.
A cut in the key rate will bring buyers back, but will barely make construction cheaper
The subsidised rate of 10-12% for a family with one child is not much lower than a market mortgage with a key rate of around 10%. Samolet said in August that a market mortgage would start working at precisely such a key rate level. On 11 September the Bank of Russia held the rate at 14%, and the next meeting is on 23 October. The faster the rate goes down, the sooner families with one child return to the market, this time with a market mortgage.
The key rate has little effect on the cost of project loans. Banks already lend the escrow-covered part of the debt at a preferential rate, and in the second quarter the average project financing rate fell by only 0.03 pp. What gets more expensive for the developer is the uncovered part, which grows when sales fall. We analysed this channel in the [second article, on developer bonds](https://telegra.ph/Developer-Bonds-Family-Mortgage-09-25).
For the budget the reform is a saving on subsidies to banks, in addition to the budget package for 2027-2029. We [analysed the tax part of the package separately](https://telegra.ph/Corporate-Taxes-2027-Miners-09-24).
Conclusion
From 1 October the family mortgage ceases to be a mass programme. For a family with one child the payment rises by 46-72%, and the available loan amount falls by a third or more. The new-build market may lose 14-33% of sales, hitting mass-market housing in Moscow and the Moscow region hardest. The shares have largely priced in the news. The main test is sales for October-December, and for Samolet it coincides with bond repayments in early 2027.
Tickers
SMLT, PIKK, LSRG, ETLN. Extended company cards are on our portal.
Weekly analysis is on the Telegram channel Enhanced Investments.
See also: market overview · valuation map · stock screeners