SCF Group: Q2 2026 revenue up 74.9%, but net debt turned positive for the first time in two years
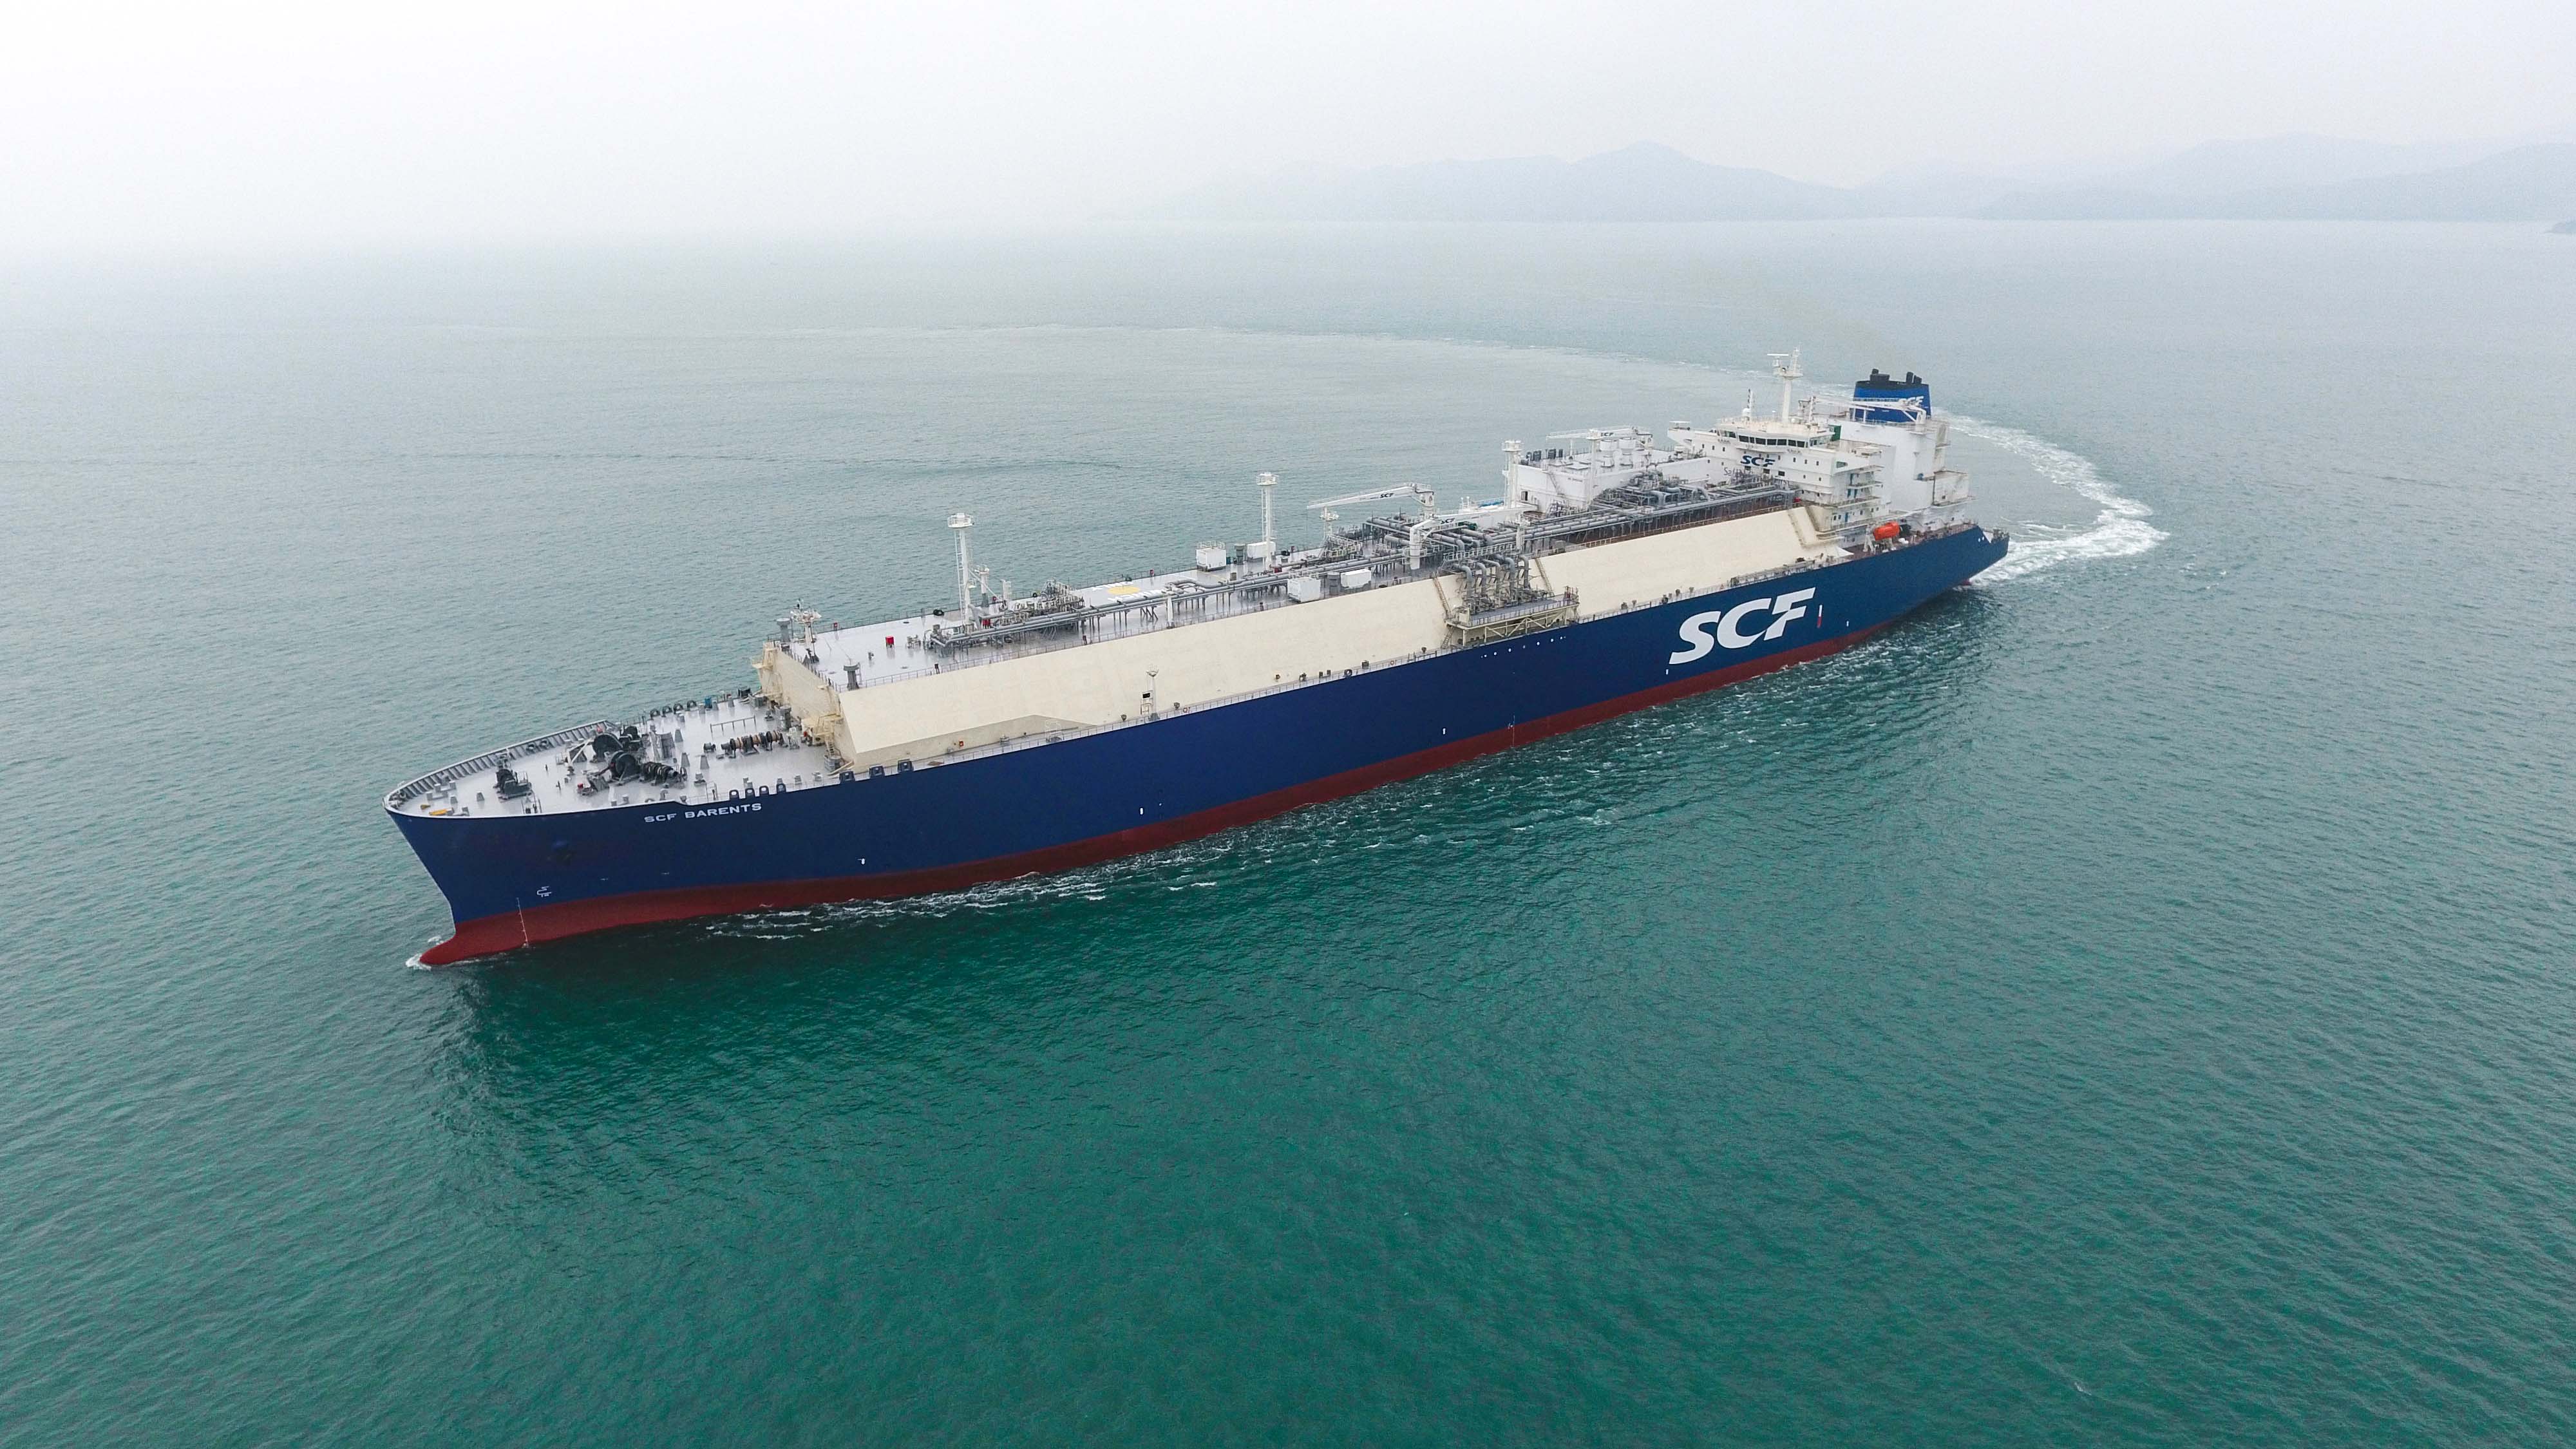
28 августа 2026 года СовКомФлот раскрыл результаты за второй квартал 2026 года: выручка выросла на 74,9% год к году, до 41,6 млрд руб., EBITDA – на 79,9%, до 22,9 млрд руб., чистая прибыль – на 676,9%, до 13,8 млрд руб. Рост произошёл на фоне восстановления ставок фрахта и увеличения объёмов перевозок, однако компания впервые за последние два года показала положительный чистый долг в 50,9 млрд руб. против отрицательного (нетто-кэш) годом ранее. Акции выглядят привлекательно: по модели портала потенциал роста составляет 17%, а мультипликатор EV/EBITDA (2,3x) находится ниже среднего за три года (2,25x), что с учётом сильной динамики показателей и восстановления рынка оправдывает позитивную оценку.
Key takeaways
— Выручка во втором квартале 2026 года выросла на 74,9% – до 41,6 млрд руб., что стало лучшим квартальным показателем за последние два года
— EBITDA-маржа достигла 55,1% против 53,6% годом ранее, чему способствовал рост тайм-чартерного эквивалента на фоне восстановления ставок
— Чистая прибыль выросла на 676,9% – до 13,8 млрд руб., что отражает не только операционный рывок, но и отсутствие обесценения судов, которое было годом ранее
— Операционный денежный поток за квартал составил 26,8 млрд руб., что почти вдвое выше EBITDA и обеспечивает прочную основу для обслуживания долга
— Чистый долг вырос на 35,2 млрд руб. за квартал и составил 50,9 млрд руб., что стало первым положительным значением с 2024 года
— Дивиденды за последние 12 месяцев не выплачивались, но компания объявила дивиденды в июне 2026 года на сумму 11,4 млрд руб., что может сигнализировать о возобновлении выплат
— По модели портала акции имеют потенциал роста 17%, что делает их привлекательными на фоне исторически низкого EV/EBITDA
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 23.8 | 41.6 | +74.9% |
| EBITDA | 12.7 | 22.9 | +79.9% |
| Operating profit | 4.61 | 14.2 | +207.1% |
| Net profit | 1.78 | 13.8 | +676.9% |
| Operating cash flow | 7.40 | 26.8 | +261.6% |
| EBITDA margin | 53.6% | 55.1% | +1.5 pp |
| Net margin | 7.5% | 33.2% | +25.7 pp |
Revenue in Q2 2026 grew 74.9% to RUB 41.6 bn, the best quarterly figure in two years
In Q2 2026, SCF Group's revenue reached RUB 41.6 bn, up 74.9% year-on-year. This is the highest quarterly figure since Q3 2024, when revenue was RUB 40.4 bn. Growth accelerated from Q1 2026 (+33.5% YoY), indicating a sustained market recovery.
The main driver was higher time-charter equivalent (TCE), which in the H1 report rose to USD 809.0 mn from USD 501.6 mn a year earlier. This reflects both higher freight rates and improved fleet utilisation. The company does not disclose segment breakdown, but the trend is clear: after two years of decline, revenue has returned to growth.
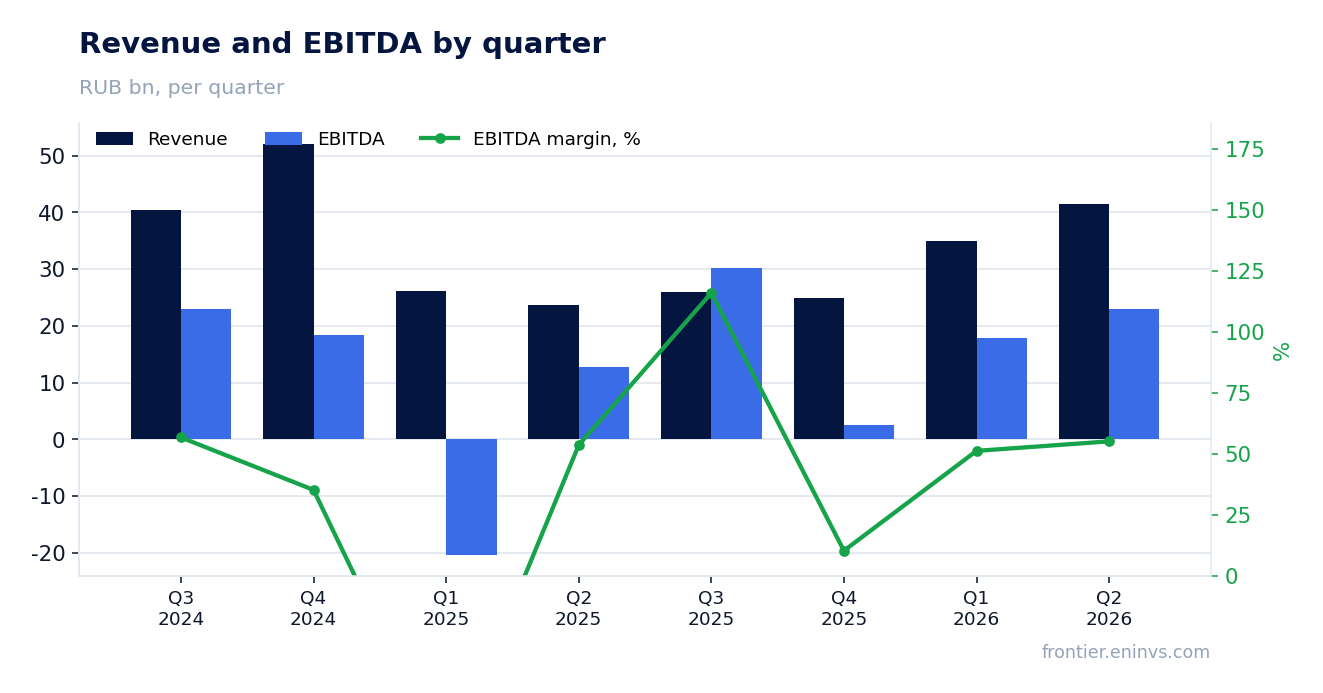
EBITDA margin reached 55.1% versus 53.6% a year earlier, helped by higher time-charter equivalent amid recovering rates
EBITDA in Q2 2026 reached RUB 22.9 bn, up 79.9% year-on-year. EBITDA margin stood at 55.1% versus 53.6% in Q2 2025. The margin improvement came as revenue grew faster than operating expenses, which rose only 21% (from USD 97.7 mn to USD 118.5 mn for the quarter).
Operating profit increased to RUB 14.2 bn from RUB 4.6 bn a year earlier, confirming the effectiveness of operating leverage. In H1 2026, operating profit was USD 310.9 mn versus a loss of USD 346.4 mn in H1 2025, which included vessel impairment of USD 358.2 mn.
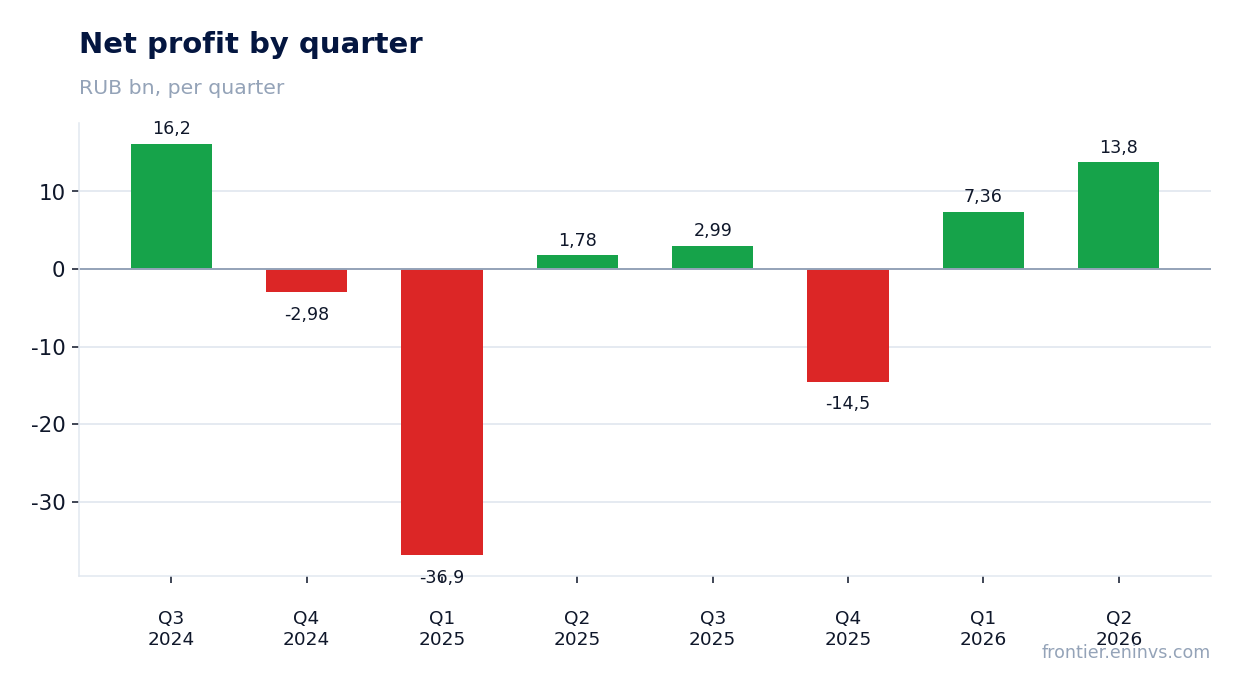
Net profit surged 676.9% to RUB 13.8 bn, reflecting not only the operational leap but also the absence of vessel impairment that occurred a year earlier
Net profit in Q2 2026 reached RUB 13.8 bn versus RUB 1.8 bn a year earlier. The 676.9% growth came from two factors: operating profit tripled, and last year's result was burdened by vessel impairment of USD 35.8 mn for the quarter (USD 358.2 mn for the half-year). In H1 2026, no impairment was recorded.
Net margin reached 33.2% versus 7.5% a year earlier. Earnings per share for H1 was USD 0.119 versus a loss of USD 0.182 a year earlier. Return on equity (ROE) for the last twelve months stood at 14.5%, above the market average.
Operating cash flow for the quarter was RUB 26.8 bn, almost double EBITDA, providing a solid base for debt service
Operating cash flow (OCF) in Q2 2026 reached RUB 26.8 bn, 2.1 times EBITDA for the same period. Over the last twelve months, OCF stood at RUB 31.9 bn, significantly exceeding capital expenditures (which are not disclosed but, judging by the cash flow statement, include acquisition of financial investments and other investments).
Strong operating cash flow ensures comfortable debt service: interest expenses for H1 were USD 46.2 mn, covered more than tenfold by operating cash flow. This gives the company a safety margin to finance its investment programme and pay dividends.
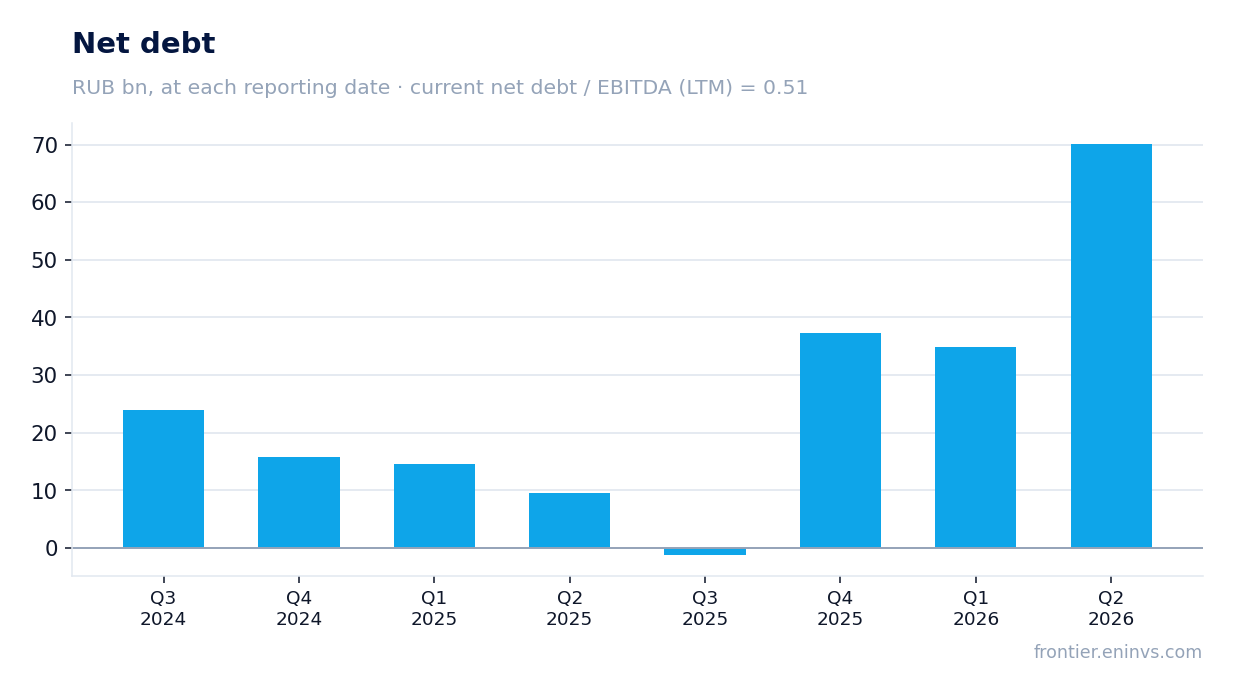
Net debt increased by RUB 35.2 bn over the quarter to RUB 50.9 bn, the first positive reading since 2024
At the end of Q2 2026, SCF Group's net debt stood at RUB 50.9 bn versus a negative value of -RUB 26.4 bn a year earlier. Over the quarter, debt increased by RUB 35.2 bn, and over the last twelve months by RUB 60.6 bn. This means the company has shifted from a net-cash position to real debt.
The increase in debt is related to higher loans and borrowings: in the statement of financial position, long-term loans rose from USD 851.9 mn at end-2025 to USD 1,131.0 mn at 30 June 2026. The company also redeemed exchange-traded bonds in yuan for USD 232.2 mn but raised new loans to finance investments. Despite this, leverage remains moderate: with EBITDA for the last twelve months around RUB 104.6 bn (sum of quarterly EBITDA), net debt/EBITDA is approximately 0.5x.
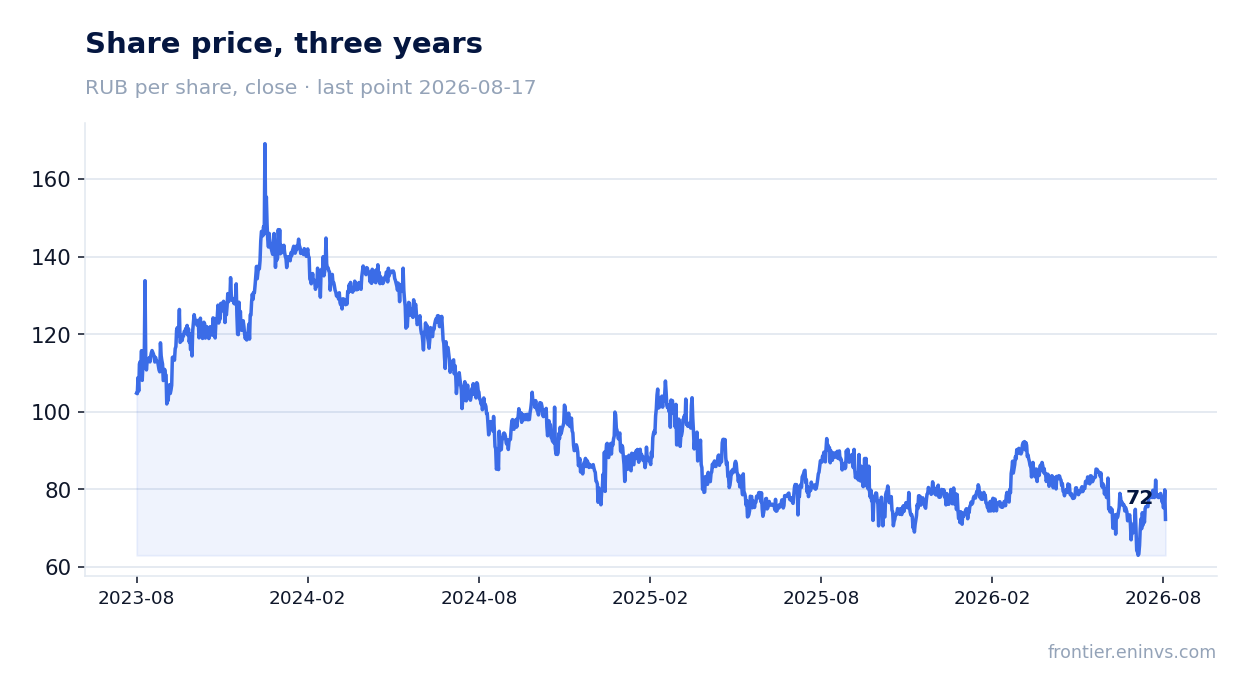
No dividends were paid over the last 12 months, but the company declared dividends in June 2026 of RUB 11.4 bn, potentially signalling a resumption of payouts
Over the last twelve months, SCF Group paid no dividends, due to sanctions and the need to preserve liquidity. However, on 26 June 2026, the company declared dividends totalling RUB 11,367 mn (equivalent to USD 150.3 mn), paid in July 2026. This is the first dividend since 2024.
Our model estimates the next payout at RUB 0.0 per share, reflecting uncertainty about dividend policy. With a fair yield of 7.0% and a payout ratio of 0.6 of profit, the shares could offer a dividend yield of about 4.1% at the current price (calculated as 0.6 * net profit for 12 months / market cap). However, actual resumption of payouts will depend on the company's ability to generate free cash flow after investments.
According to the portal's model, the shares have 17% upside, making them attractive given historically low EV/EBITDA
Our fundamental value-creation model (the portal's model) indicates that SCF Group's shares have an upside of +17% to fair value. This is based on EBITDA growth times the target multiple, compared with the current market capitalisation. The current EV/EBITDA is 2.25x (three-year average), significantly below the average for global tanker companies.
With a market capitalisation of RUB 192.2 bn and EV/EBITDA at 2.25x, the company is valued at a discount to its own history: over the past three years, the average EV/EBITDA was roughly the same, but now EBITDA is growing at double-digit rates. If the market recovery continues, the multiple could expand, providing additional upside.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 192 bn ₽ |
| P/B | 0.52 |
| Operating cash flow (LTM) | 31.9 bn |
| ROE | 14.5% |
Bottom line
СовКомФлот отчитался за второй квартал 2026 года с сильным ростом выручки и прибыли, что подтверждает восстановление рынка после двухлетнего спада. EBITDA-маржа достигла 55,1%, а операционный денежный поток почти вдвое превысил EBITDA, обеспечивая прочную основу для обслуживания долга. Однако компания впервые за два года показала положительный чистый долг, что требует внимания к инвестиционной программе и её влиянию на свободный денежный поток. При текущем EV/EBITDA 2,25x и потенциале роста 17% по модели портала акции выглядят привлекательно, но ключевым фактором останется устойчивость ставок фрахта и способность компании генерировать денежные средства после капитальных затрат.
Open the company's financial profile FLOT →
See also: market overview · valuation map · stock screeners