GLORAX announced a buyback: at what price, for whom and how much will be bought
On 20 August the shares of GLORAX (GLRX) rose 18.5% to RUB 41.9 after the board of directors called an extraordinary shareholder meeting with a reorganisation on the agenda. The market read the news as a buyback announcement. A buyback will indeed take place, but it works differently from a conventional one, and the company has not yet named the price.
Below we work out who is entitled to the buyback, what the legal minimum price is, how many shares can realistically be bought, and what you need to do to take part. All figures are taken from primary sources: documents on the issuer's website, the text of the Joint-Stock Companies Law, Moscow Exchange data and statements from the state register of accounting reports.
Only those who vote against the reorganisation or do not vote at all will get the buyback
On 18 August (minutes dated 19 August) the board called an absentee vote, and ballots are accepted until 5 October 2026. The agenda has 13 items. The first is a reorganisation through the merger of LLC "Specialised Developer NTVO". The rest are approvals of major transactions, guarantees and supplementary agreements with Sberbank and DOM.RF Bank.
Article 75 of the Joint-Stock Companies Law gives a shareholder who voted against the reorganisation, or did not take part in the vote, the right to demand a buyback of their shares. The company does not buy anything in the exchange order book. It is obliged to buy the shares at a fixed price from everyone who files a demand, and this is the fundamental difference from an ordinary buyback.
The calendar from here is rigid and set by law. Demands are accepted for 45 days after the meeting's decision, that is until 19 November. The buyback and payment itself take place within the following 30 days, from 20 November to 19 December 2026.
The price has not been announced yet, but by law it cannot fall below about RUB 44.5
On the issuer's website, in the shareholder meetings section, there is not yet a notice of the October meeting, and the latest document relates to the annual meeting of 30 June. The buyback price is also not named in the board's disclosure.
Its floor, however, is set by paragraph 3 of Article 75. The price cannot be lower than the weighted average exchange price for the six months preceding the date of the decision to call the meeting. The weighted average price is turnover in roubles divided by turnover in shares, that is an average price weighted by volumes, not a simple average of quotes.
A calculation from Moscow Exchange data for the window 18 February - 17 August 2026 gives RUB 44.57. The method was checked on the previous buyback of the same stock: for the window of 3-9 February it gives RUB 61.65 against the official RUB 61.46, that is it overstates by about 0.3%. With this adjustment the reference range is RUB 44.3-44.6, which is 11-14% above current quotes.
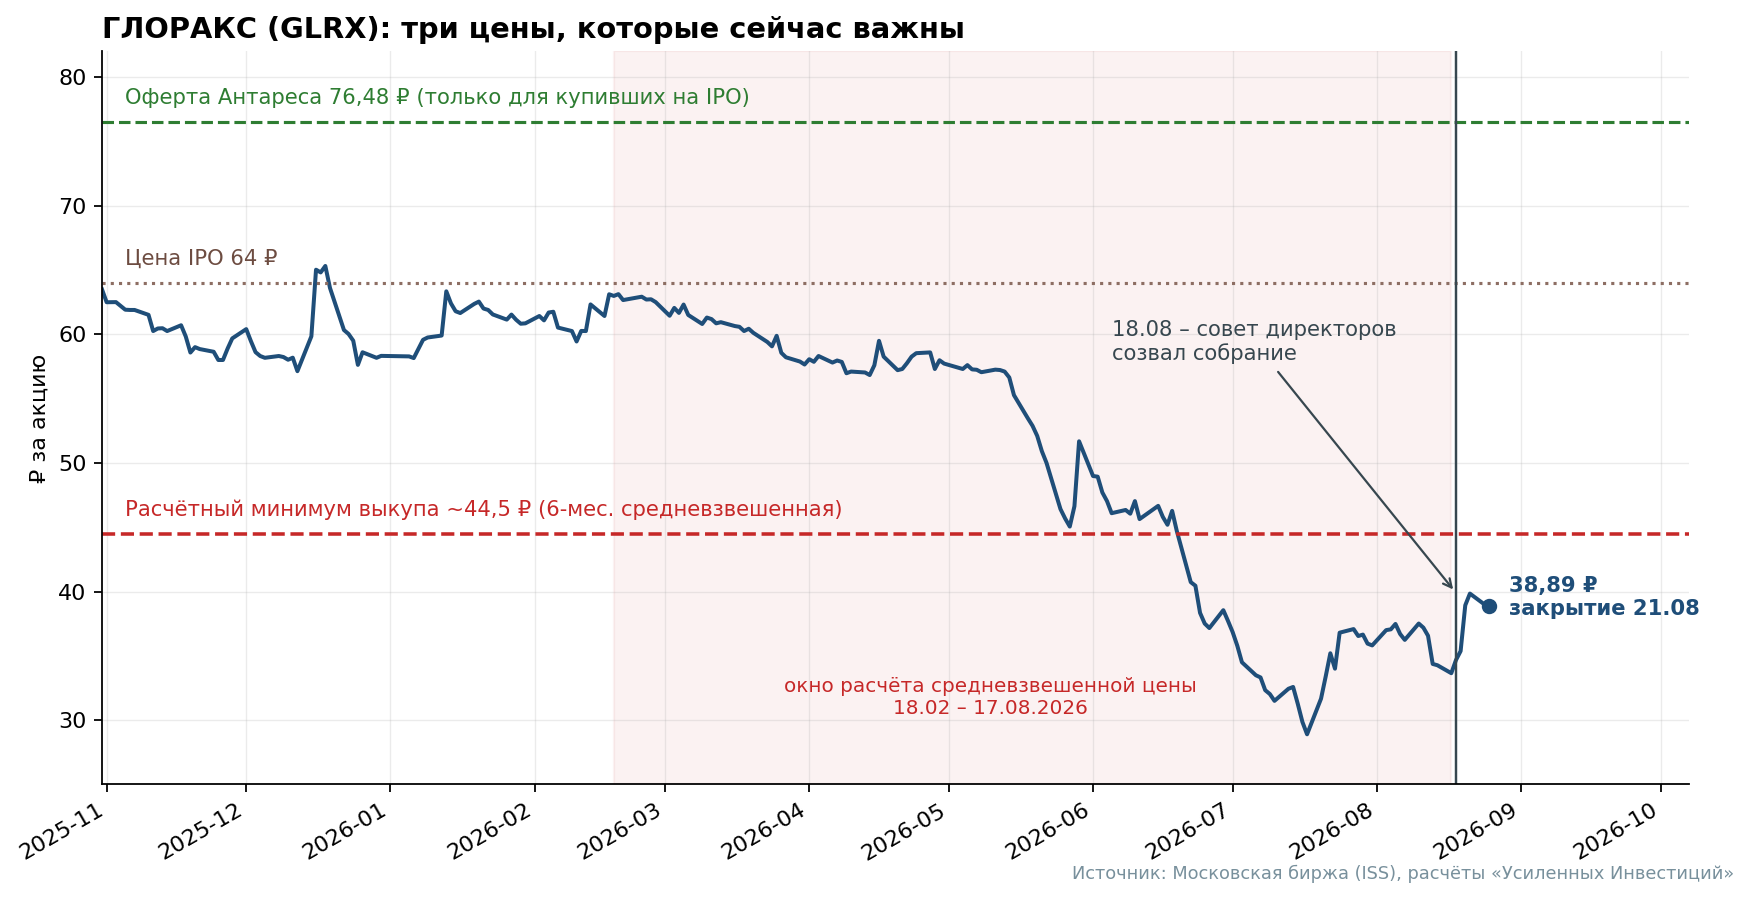
Last year's precedent is useful in another way too. Then the board set not a number but a formula: the weighted average price for 3-9 February, but not below RUB 43. The actual result was RUB 61.46. The six-month rule did not apply that time because the stock had traded for less than six months. Now it does apply, so RUB 44.3-44.6 should be read as a lower bound, not a forecast.
The notice with the price will come out after the register has closed
The record date for the list of shareholders entitled to vote is 31 August 2026. The same list determines who may demand a buyback. With T+1 settlement the last trading day to get into the register is Friday, 28 August.
For a reorganisation item, the notice of the meeting is published no later than 30 days before the end of ballot acceptance, that is by 5 September. This leaves a time gap. The decision to buy has to be made before 28 August, while the official buyback price will be known only in early September. Until then the only thing to rely on is the legal minimum.
The 10% net assets cap covers about a third of the free-floating shares
The law does not promise a full buyback. Under paragraph 5 of Article 76, the total amount the company directs to the buyback cannot exceed 10% of the net asset value on the date of the meeting's decision. Net assets are assets minus liabilities under the Russian accounts of the PJSC itself, without group consolidation. If more demands come in than the cap, shares are bought pro rata to the demands submitted.
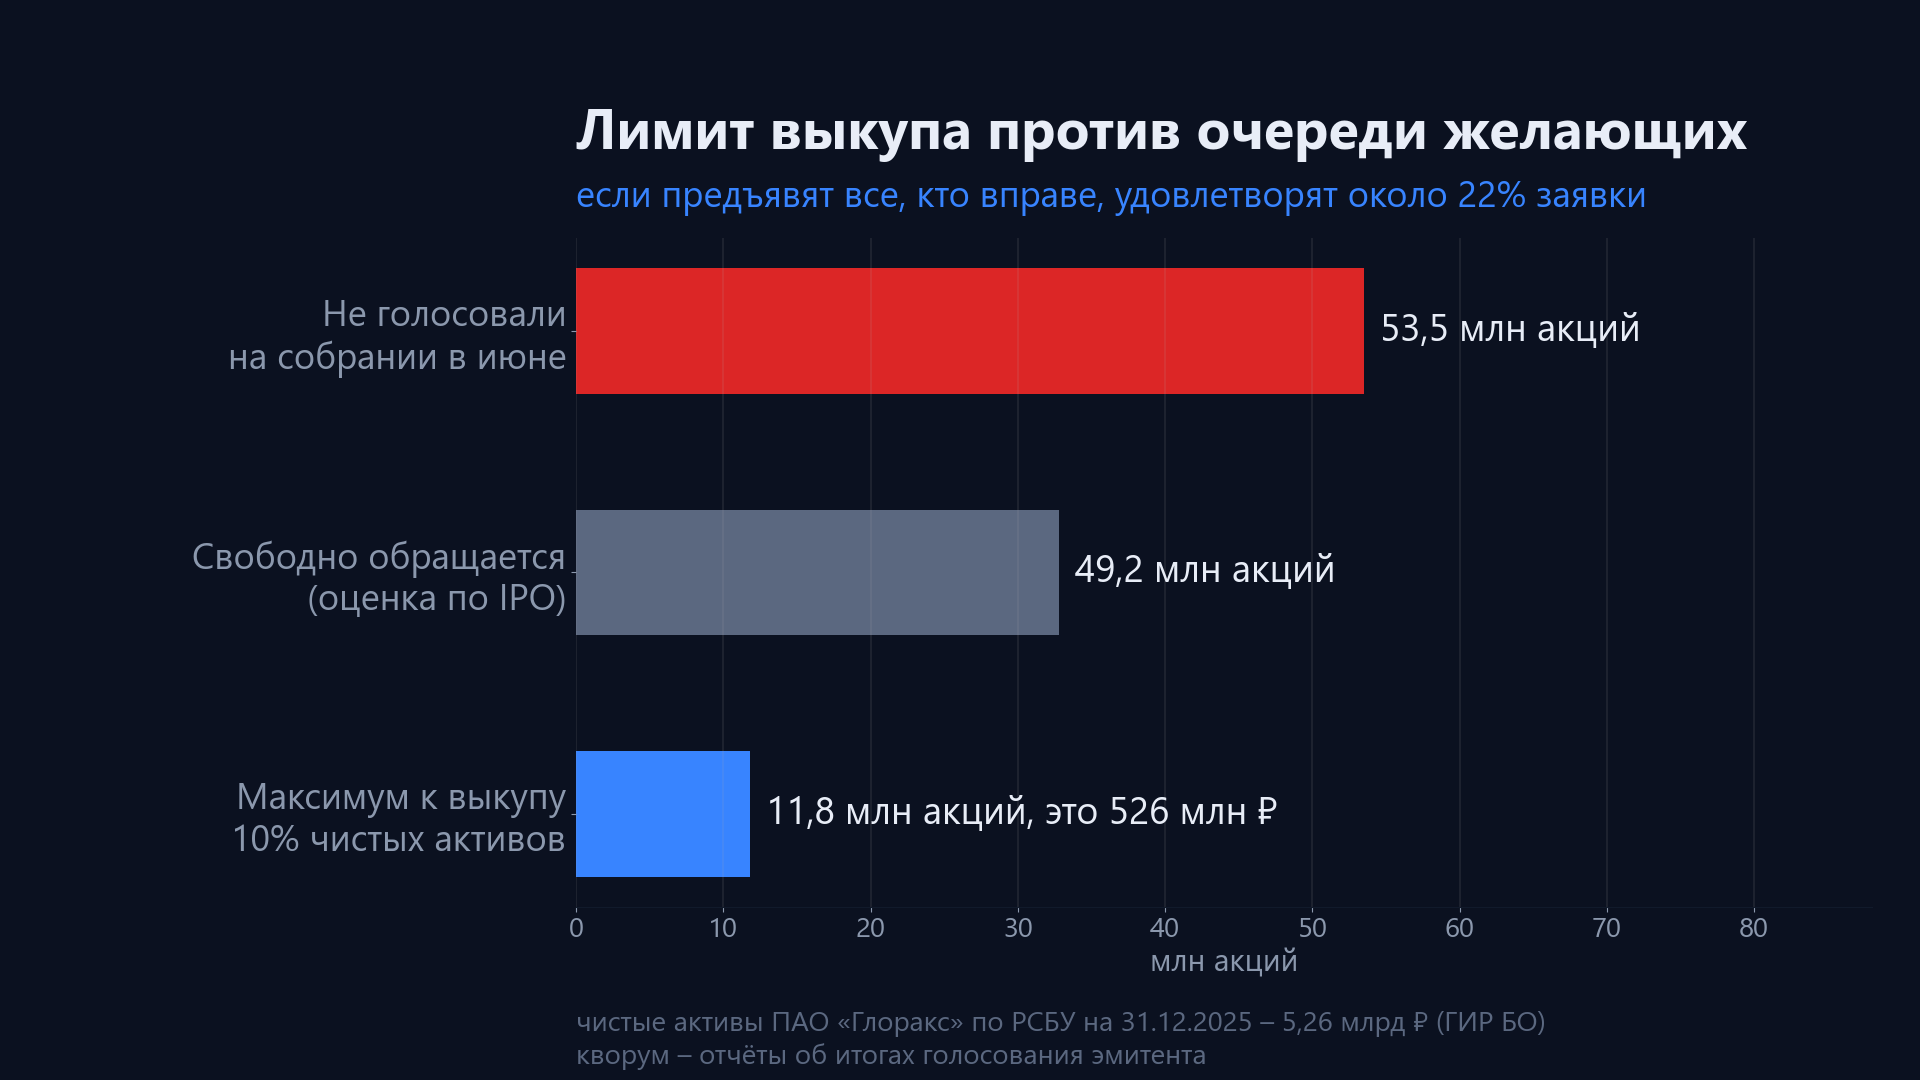
The net assets of PJSC GLORAX at 31 December 2025 were RUB 5.26 bn (state information resource for accounting statements). The cap is accordingly about RUB 526 mn. At a price of RUB 44.5 this is about 11.8 mn shares, or 4.2% of share capital.
Free float is 49.2 mn shares, or 17.4%, per the company's own data as of 30 June 2026. Right after the IPO free float was 11.6%, and the growth came after the lock-up ended. The cap covers about a quarter of this volume.
A caveat on the figure, confirmed by the company. The cap is calculated from net assets on the date of the meeting's decision, that is on 5 October, and they will be determined by a separate accounting statement. So RUB 526 mn is a reference based on end-2025 data, and the actual cap will be known only in October and may differ.
The queue for the buyback is wider than the free market: 53.5 mn shares did not vote at the last meeting
The right to demand a buyback goes to those who voted against or did not take part in the vote. So the upper bound of the queue can be measured in advance, from the quorum of previous meetings. The company publishes voting results reports on its website.
The extraordinary meeting of 18 December 2025, which had similar major transactions with the right of buyback: voting shares 282,812,500, participating 248,437,500, quorum 87.85%, zero votes "against" on all thirteen items. Disinterested shares in the transactions were 46,875,000, of which 12,500,000 voted. From this the structure unfolds: the controlling group holds 235,937,500 shares, or 83.43%, and it voted entirely "for".
The annual meeting of 30 June 2026: 229,332,500 shares participated, quorum 81.09%, 53,475,809 shares did not vote, which is 18.9% of capital. Over half a year the non-voting pool grew from 34.4 mn to 53.5 mn. The company explained this as follows: the founder allocated shares from his stake for management motivation, they were transferred to top managers in early 2026 with a lock-up until the end of April, and after it ended these shares, under Moscow Exchange rules, began to be counted in free float. The employees did not sell them to the market.
If the picture repeats in October, about 53 mn shares will have the right to demand a buyback against a cap of 11.8 mn. The maximum satisfaction ratio if everything is tendered is 22%. A separate risk is visible in the same data: disinterested shares are 46.88 mn, free float is about 32.8 mn, which leaves a block of about 14 mn shares outside the exchange and outside the controlling group. In December 12.5 mn of it voted. If this holder does not vote in October, it alone will use up the entire cap.
The February buyback collected 4,191 shares, and this is the best indicator of turnout
This stock has already had a buyback: demands were accepted from 19 December to 2 February, the price was RUB 61.46, and the transaction was recorded in the register on 4 March. The company did not separately disclose how many shares were tendered, but it can be seen indirectly. Between the two meetings the number of voting shares changed from 282,812,500 to 282,808,309, a difference of 4,191 shares, which are the shares that ended up with the company, since a company does not vote with its own shares.
That is, with 34.4 mn shares entitled to a buyback, about four thousand were tendered. The reason is understandable: the price of RUB 61.46 was at the market level, and the shares were blocked for a month. Now the estimated premium to the market is 11-14%, so the figures will be of a different order, but the measurement itself is useful, because it was made on exactly this shareholder base, not by analogy with other issuers.
The exception for merging a wholly owned subsidiary does not apply in this case
Since the end of 2024 Article 75 has contained a provision that can nullify the whole story. The right to demand a buyback does not arise if a wholly owned subsidiary whose assets do not exceed 2% of the parent's assets is merged into the company.
The test is passed here. The assets of LLC "SZ NTVO" at the end of 2025 are RUB 19.42 bn against RUB 21.63 bn for PJSC GLORAX. This is incomparably more than 2%, so the exception does not apply and the buyback right arises. An additional margin of safety comes from the major transactions on the agenda. In December 2025 the same items already gave rise to a buyback right, because the subject was obligations exceeding 50% of the book value of assets.
To take part in the buyback you need to do four things
- Be in the register on 31 August 2026. With T+1 settlement this means buying no later than Friday, 28 August.
- Not vote for the reorganisation. The right is kept both by those who vote against and by those who do not take part in the vote. A vote "for" removes the right.
- File a buyback demand through your broker in the window from 5 October to 19 November. Shareholders recorded directly in the register send the demand to the registrar, JSC "NRK - R.O.S.T.".
- Wait for settlement on 20 November - 19 December. From the moment of filing the demand the shares are blocked and cannot be sold before settlement, and the demand can be withdrawn only in full.
IPO participants have a more expensive option: RUB 76.48 in November
A second mechanism, which is hardly written about in the news, works in parallel. At the placement in October 2025 an irrevocable offer was issued. LLC "Specialised Developer Antares" undertook to buy the shares at 1.195 times the placement price, that is at RUB 76.48.
The trigger condition is this: on at least one of five consecutive main trading sessions of the control period, the weighted average price is below the placement price of RUB 64. The control period starts 365 days after the start of trading, that is approximately 2-9 November 2026. With quotes around RUB 40 the condition is practically certain to be met.
The circle of participants is narrow. The offer is addressed to those who bought shares at the IPO itself, and for shares bought on the exchange in the first 30 days of trading it applies, in the company's wording, "to a limited extent" - see the text of the offer itself for the exact limit. Continuous holding of the shares until the end of the acceptance period is required, so margin loans, repo transactions and lending of shares break this condition. It is impossible to buy the stock today and get into this offer.
An important detail for those entitled to both options: they cannot be used at the same time. An Article 75 buyback demand is filed from 5 October to 19 November, and from the moment of filing the shares are blocked on the account, so in mid-November they can no longer be used to submit a targeted order in the "Buyback: targeted orders" mode. IPO holders rationally choose the offer at RUB 76.48, and in doing so they do not claim any of the 10% net assets cap.
One more detail for those who have held shares since the placement. The offeror is not the issuer itself but its wholly owned subsidiary. The press release on the IPO results of 31 October 2025 says this directly: "Offeror: LLC SZ Antares, a 100% subsidiary of the Company". That is, the obligation under the offer stays inside the group, and it is performed from the group's own resources.
Some figures are closed, and we have requested them from the company
The annual report and the list of affiliated persons with the names of holders above 5% are disclosed on the Interfax portal, which is currently behind bot protection, and they are not on the issuer's website. So the questions have been sent directly to IR: when the notice of the meeting with the price and buyback procedure will come out, whether the price will be a number or a formula, what the net asset value is at the latest reporting date and on what date the cap will be determined, whether the post-IPO stabilisation package was sold and what the free float is now, who owns a stake above 5%, and when the control dates and the exact dates of the control period and acceptance period under the offer will be disclosed. We will publish the answers.
IR confirmed the price methodology and the capital structure
The questions were sent to the IR of PJSC GLORAX, and answers were received on 26 August. The main points of them.
- The price will be fixed and determined according to the requirements of the law, that is not lower than the weighted average price of the shares on the Moscow Exchange for the six months preceding the date of the decision to hold the meeting. This is exactly the methodology used for the calculation above.
- The notice with the price will come out within the period set by law, that is not earlier than the law requires, and after the register closes on 31 August.
- The 10% cap will be calculated from net assets on the date of the meeting's decision on the basis of an accounting statement. The estimate of RUB 526 mn from 2025 statements is a reference, not the final figure.
- The stabilisation package was bought back in the first month of trading and was not returned to the market. It is now a treasury stake of 1.55% of capital held at a subsidiary. The first IR answer was different, and the company clarified the wording on 27 August.
- The only holder of more than 5% is Andrey Birzhin with 74.5% as of 30 June 2026. Exactly 5% more is held by Alexander Andrianov, 1.5% by management including shares in the process of transfer under the motivation programme, 1.6% is the treasury stake held by LLC "Glorax-Nedvizhimost M", and 17.4% is in free float.
- The control dates under the offer are not disclosed in advance. A description of the mechanism is on the company's website in the investor materials section.
- On whether blocking of shares when filing an Article 75 demand prevents simultaneous acceptance of the offer, the company promised to come back with a comment from its lawyers. Until then the conclusion that the two mechanisms are incompatible remains our reading of the documents.
The capital structure also closes a question that was previously left hanging. The non-voting pool of 53.5 mn shares almost exactly matches the sum of free float and the treasury stake at the subsidiary, 49.2 plus 4.5 mn. That is, there is no separate large holder in the capital able to use up the whole cap alone.
What could go wrong
- The official price will become known only after the register closes, while the decision to buy is made earlier.
- With a pro rata buyback, part of the stake will remain in hand and be exposed to a possible fall in quotes after the event.
- The money is tied up for about four months, and the cost of funding eats a noticeable part of the premium.
- The buyback right arises only if the meeting approves the reorganisation. The vote is still ahead.
- The cap is calculated from net assets on 5 October, while the available statements are as of the end of 2025.
Conclusion
The story offers a clear exit at a price above the market, but limited in volume and with a rigid calendar. The legal minimum buyback price is about RUB 44.5 against RUB 39-40 on the exchange. The 10% net assets cap is about 11.8 mn shares, whereas 53.5 mn did not vote at the last meeting, so with mass tendering the buyback will be partial, down to 22% of an order. The company will calculate the exact cap on 5 October. The nearest significant date is Friday, 28 August, the last day to buy to get into the register. The official price should be expected in the first days of September together with the notice of the meeting.
Company card with multiples and primary sources of the statements: frontier.eninvs.com/company/RU_GLRX.
More analytics in the Telegram channel Усиленные Инвестиции @eninv.
Sources
- [Irrevocable offer of PJSC GLORAX dated 23.10.2025](https://cms-investors.glorax.com/assets/472f963d-58d0-4d15-8cd6-5a59e9fb57a1.pdf)
- [Notice of the extraordinary meeting of 18.12.2025 with the terms of the previous buyback](https://cms-investors.glorax.com/assets/965e7a78-a2ea-48b6-b0f3-f65bd2dfe95d.pdf)
- [Article 75 of the Joint-Stock Companies Law](https://www.consultant.ru/document/cons_doc_LAW_8743/090869d6592ba6baba0520a47449033eba3d5f4d/)
- [Article 76 of the Joint-Stock Companies Law](https://www.consultant.ru/document/cons_doc_LAW_8743/be6f50663ce49b77221ca7e2928d8dd8d6fc0e53/)
- Quotes and turnover - Moscow Exchange (ISS). Statements of PJSC GLORAX, LLC "SZ NTVO" and LLC "SZ Antares" - GIR BO of the Federal Tax Service.
See also: market overview · valuation map · stock screeners