Rushydro: profit up 80%, but capex eats the entire gain
On 28 August Rushydro released its Q2 2026 results. Revenue rose 18.7% year on year to RUB 176.2 bn, EBITDA – by 50.1% to RUB 68.8 bn, net profit – by 80.4% to RUB 22.8 bn. The EBITDA margin climbed to 39.0% from 30.9% a year earlier. Yet capital expenditures for the quarter reached RUB 55.1 bn – more than the entire operating cash flow of RUB 58.0 bn – and the company has not paid dividends for four years. The shares trade at a P/E of 1.16 and EV/EBITDA of 3.47 – cheap by historical standards, but net debt at 3.04 EBITDA and the absence of payouts make the stock attractive only to a patient investor willing to wait for a dividend turnaround.
Key takeaways
— Revenue rose 18.7% year on year, but the pace was roughly unchanged from the first quarter
— EBITDA gained 50.1% on faster tariff growth and a lower share of fuel costs
— Net profit rose 80.4%, but RUB 4.4 bn of it came from one-off items
— Operating cash flow of RUB 58.0 bn does not cover capital expenditures of RUB 55.1 bn
— Debt rose to RUB 767.4 bn, with net debt/EBITDA LTM at 3.04
— No dividends for the fourth year, and the fair yield of 10.5% remains out of reach
— The shares trade at a P/E of 1.16 and EV/EBITDA of 3.47 – below historical levels
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 148 | 176 | +18.7% |
| EBITDA | 45.8 | 68.8 | +50.1% |
| Operating profit | 36.2 | 56.3 | +55.6% |
| Net profit | 12.7 | 22.8 | +80.4% |
| Operating cash flow | 30.9 | 58.0 | +87.7% |
| Capex | 56.5 | 55.1 | -2.4% |
| EBITDA margin | 30.9% | 39.0% | +8.1 pp |
| Net margin | 8.5% | 13.0% | +4.5 pp |
Revenue rose 18.7% year on year, but the pace was roughly unchanged from the first quarter
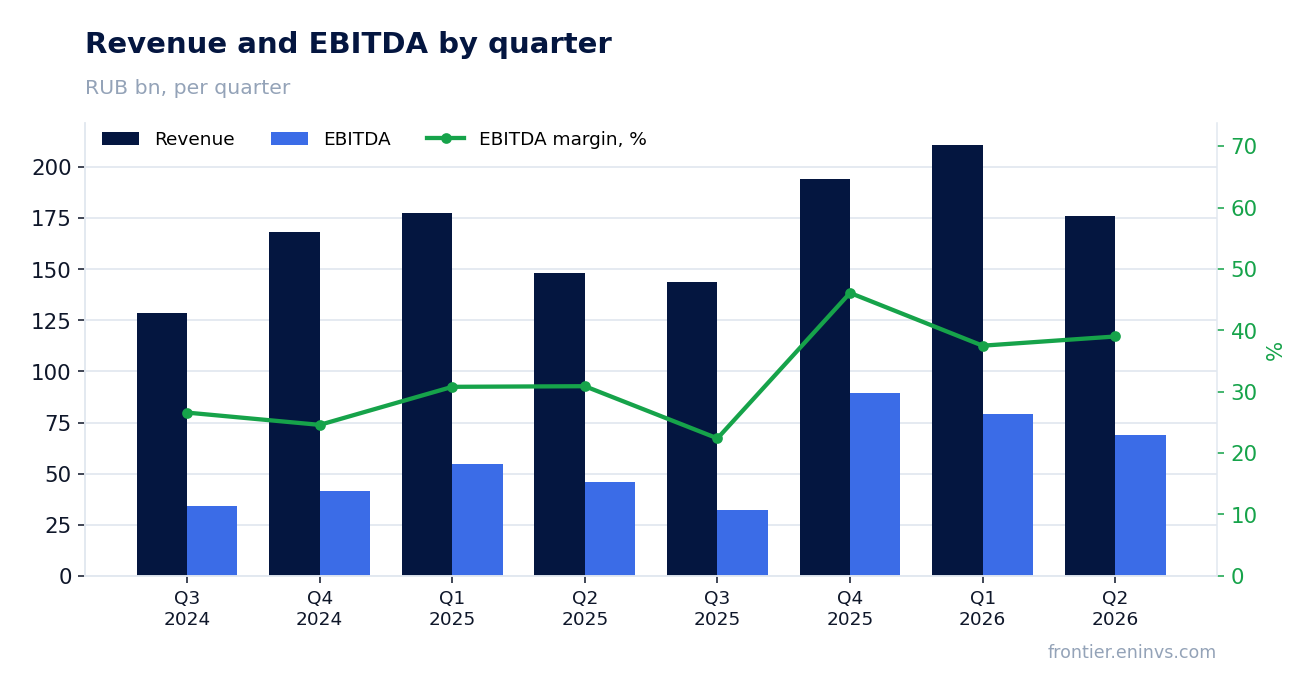
Revenue in the second quarter of 2026 amounted to RUB 176.2 bn, up 18.7% year on year. In the first quarter growth was 19.0% – the pace was roughly unchanged. The company has maintained high dynamics for four consecutive quarters: in Q4 2025 revenue added 15.2%, in Q3 – 12.1%.
The main contribution came from the Generation segment, where half-year revenue increased to RUB 146.8 bn from RUB 120.3 bn a year earlier. The Sales segment added to RUB 133.6 bn from RUB 105.6 bn, and Far East Energy Companies – to RUB 178.0 bn from RUB 153.3 bn. Revenue growth in generation is linked to higher sales of electricity on the wholesale market and capacity.
Government subsidies for the half-year rose to RUB 41.1 bn from RUB 32.3 bn a year earlier, also supporting total revenue. Excluding subsidies, growth would have been more modest, but the company does not disclose revenue excluding subsidies separately.
EBITDA gained 50.1% on faster tariff growth and a lower share of fuel costs
EBITDA in the second quarter of 2026 reached RUB 68.8 bn, up 50.1% year on year. The EBITDA margin rose to 39.0% from 30.9% in Q2 2025. Such margin growth is the result of faster growth in electricity and capacity tariffs relative to fuel costs.
In the Generation segment, half-year EBITDA amounted to RUB 105.0 bn versus RUB 80.4 bn a year earlier. The Far East Energy Companies segment showed EBITDA growth to RUB 38.0 bn from RUB 10.9 bn, linked to increased subsidies and tariffs in the Far East. The Sales segment remains low-margin: EBITDA of RUB 5.7 bn versus RUB 4.0 bn.
Operating expenses excluding depreciation and other non-cash items for the half-year rose to RUB 278.4 bn from RUB 259.7 bn, i.e. by 7.2% – significantly slower than revenue. This provided the main increase in EBITDA.
Net profit rose 80.4%, but RUB 4.4 bn of it came from one-off items
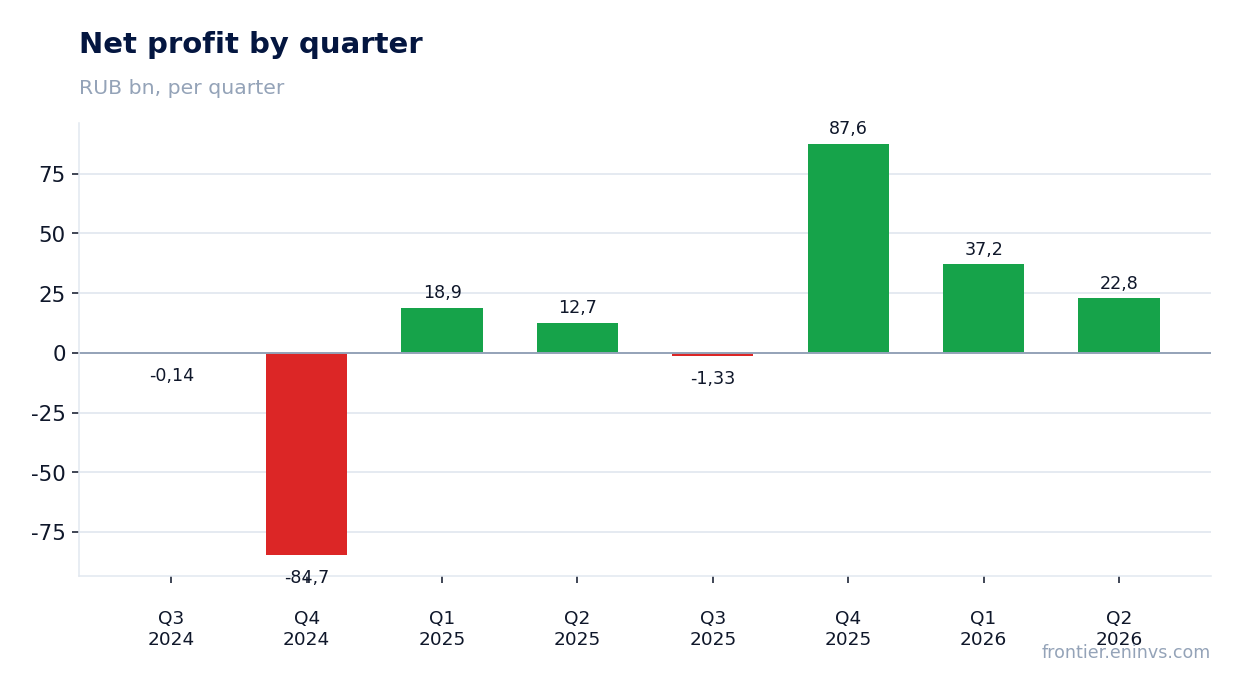
Net profit in the second quarter of 2026 amounted to RUB 22.8 bn, up 80.4% year on year. The net margin rose to 13.0% from 8.5%. However, the income statement reflects one-off items that distort the picture.
Impairment loss on financial assets amounted to RUB 0.9 bn, impairment loss on property, plant and equipment – RUB 2.2 bn. These items reduced profit but are non-cash. At the same time, the discounting effect on long-term receivables from government subsidies brought RUB 2.1 bn of income, and profit from disposal of fixed assets – RUB 1.4 bn for the half-year.
Excluding these one-off items, net profit would have been closer to RUB 20 bn. Nevertheless, even adjusted profit is significantly higher than last year, indicating a fundamental improvement in operating efficiency.
Operating cash flow of RUB 58.0 bn does not cover capital expenditures of RUB 55.1 bn
Operating cash flow in the second quarter of 2026 amounted to RUB 58.0 bn, up 87.7% year on year. However, capital expenditures for the same period reached RUB 55.1 bn, meaning almost the entire operating flow went to investments. Free cash flow was minimal – about RUB 2.9 bn.
For the first half of 2026, capital expenditures amounted to RUB 122.9 bn versus RUB 101.5 bn a year earlier. The bulk of investments falls on the Generation segment – RUB 115.2 bn for the half-year. The company continues to finance the construction of hydroelectric power plants and the modernization of existing capacities.
This ratio of operating flow to capital expenditures means the company does not generate enough free funds to pay dividends. As long as the investment programme remains a priority, dividend payments are likely to be postponed.
Debt rose to RUB 767.4 bn, with net debt/EBITDA LTM at 3.04
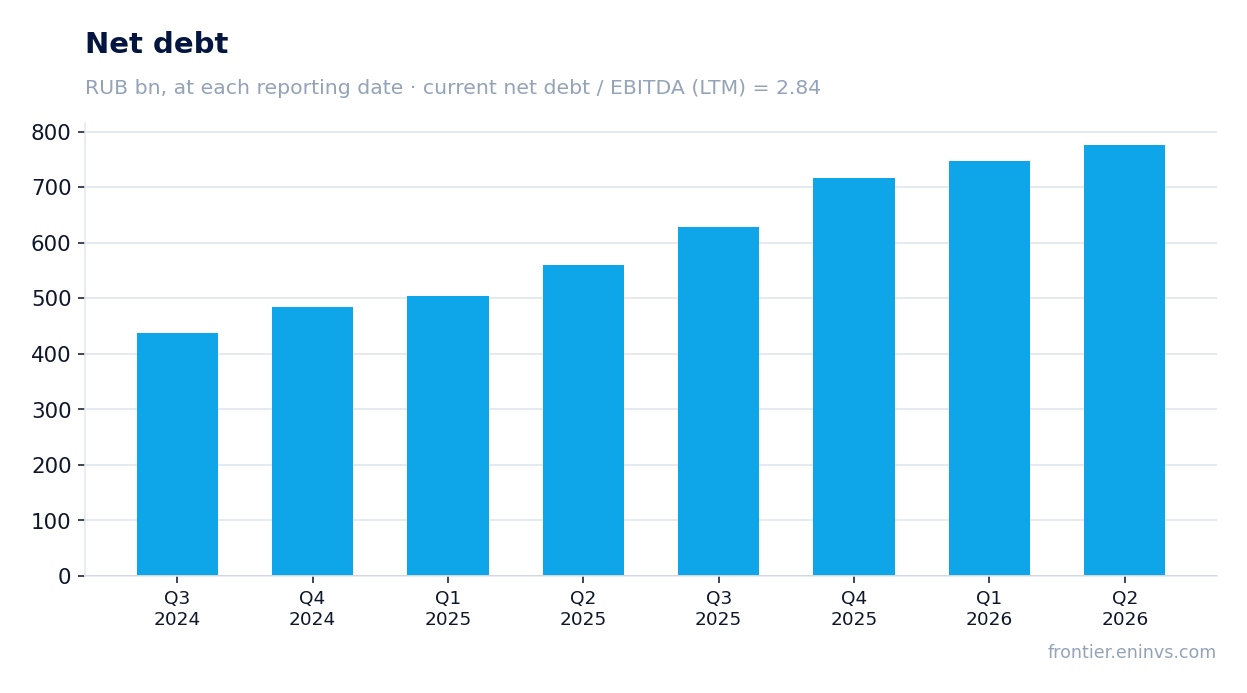
Net debt as of 30 June 2026 amounted to RUB 767.4 bn, up from RUB 737.4 bn as of 31 March 2026 (+RUB 29.9 bn). Over the year, debt grew significantly: from RUB 553.2 bn as of 30 June 2025 to RUB 767.4 bn as of 30 June 2026 (+RUB 214.2 bn).
The net debt/EBITDA LTM ratio stands at 3.04. This is a moderate level for a highly capital-intensive company, but it limits dividend payment capacity. Financial expenses for the half-year amounted to RUB 35.4 bn, comparable to net profit for the same period.
The bulk of debt is concentrated in the Generation segment – RUB 598.7 bn out of RUB 842.3 bn total borrowings. The company actively raises both short-term and long-term loans: during the half-year, proceeds from long-term borrowings amounted to RUB 251.7 bn, short-term – RUB 79.4 bn.
No dividends for the fourth year, and the fair yield of 10.5% remains out of reach
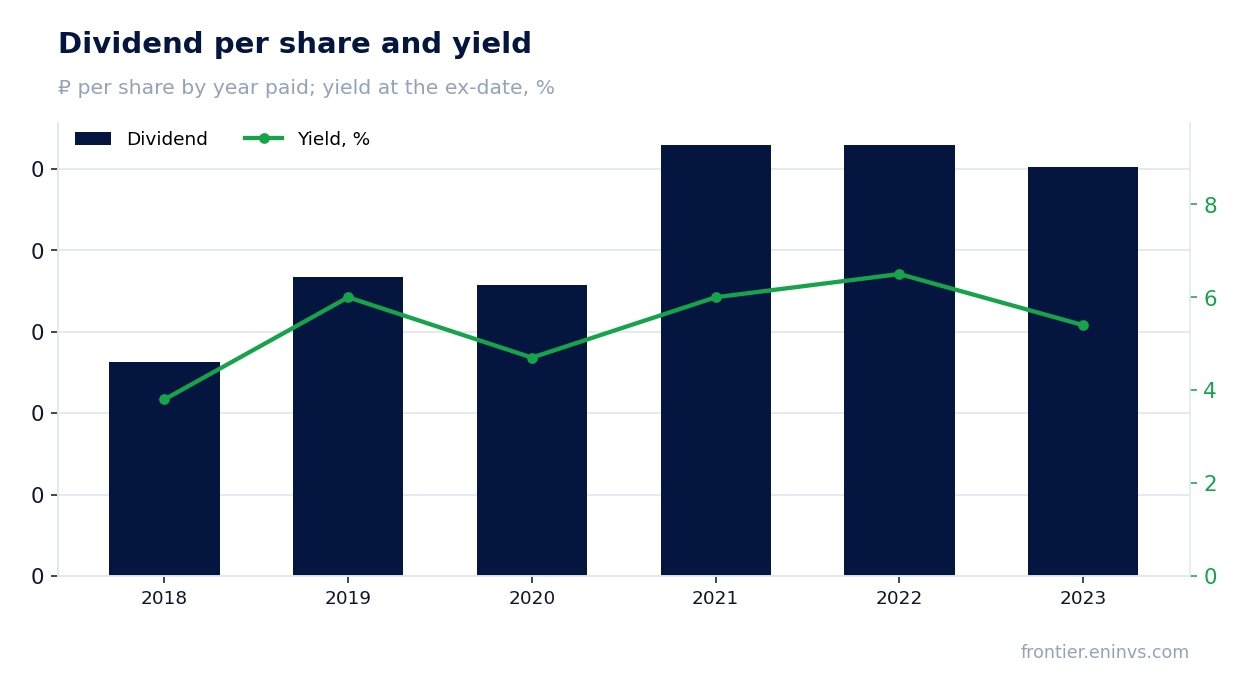
No dividends have been paid over the last 12 months. The last payment was for 2023 – RUB 0.0503 per share with a yield of 5.4% at the ex-date. Since then, the company has not paid dividends despite profit growth. No payouts are planned for 2026 either.
Our estimate of the fair dividend yield for this stock is 10.5%. At the current price of RUB 0.3396, this would correspond to a dividend of about RUB 0.0357 per share. However, with a payout ratio of 0.3 of profit and LTM profit of RUB 146.3 bn, the payout potential is about RUB 43.9 bn, or RUB 0.0996 per share – a 29.3% yield, significantly above the fair level. But the company prefers to direct funds to investments.
The central bank key rate is 14.0%. For the dividend yield to be competitive, it must exceed this rate adjusted for risk. The current yield of 0% does not meet this condition. To resume payments, the company must either cut the investment programme or increase debt burden, which at the current level of 3.04 EBITDA is risky.
The shares trade at a P/E of 1.16 and EV/EBITDA of 3.47 – below historical levels
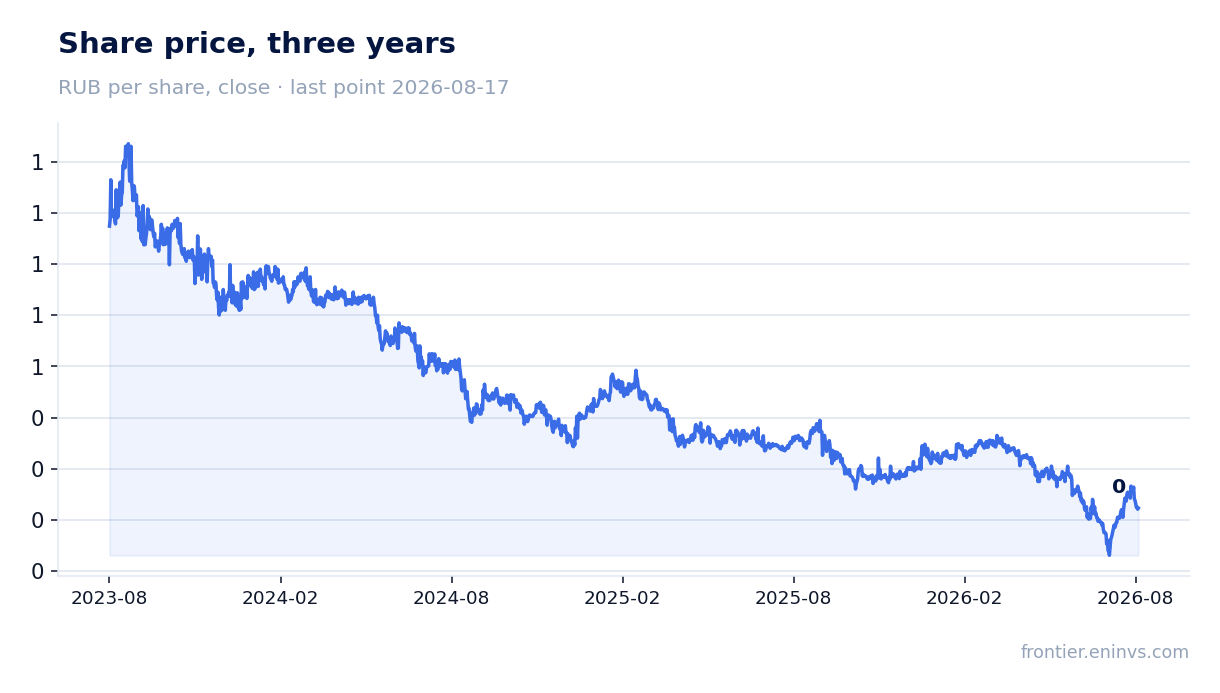
The P/E LTM multiple is 1.16, extremely low. For comparison, in 2021–2023 the company's P/E typically ranged from 4 to 6. The current level reflects both high LTM profit (RUB 146.3 bn) and low market capitalization (RUB 169.6 bn).
EV/EBITDA LTM is 3.47. This is also below historical values, which in past years were 5–7. Low multiples are explained by high debt: EV includes net debt of RUB 767.4 bn, which increases the denominator. The market values the company cheaply due to the absence of dividends and high capital expenditures.
ROE is 12.0%, which is decent for a capital-intensive business. However, without dividends, this return does not materialize for shareholders. As long as the company does not start returning capital, low multiples may persist.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 170 bn ₽ |
| P/E (LTM) | 1.2 |
| EV/EBITDA (LTM) | 3.5 |
| P/B | 0.24 |
| Net debt / EBITDA (LTM) | 3.04 |
| Operating cash flow (LTM) | 209 bn |
| ROE | 12.0% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2018 | 0.03 | 3.8% |
| 2019 | 0.04 | 6.0% |
| 2020 | 0.04 | 4.7% |
| 2021 | 0.05 | 6.0% |
| 2022 | 0.05 | 6.5% |
| 2023 | 0.05 | 5.4% |
Bottom line
Rushydro delivered strong operating results: revenue rose 18.7%, EBITDA – 50.1%, net profit – 80.4%. However, the entire operating cash flow goes to capital expenditures, and debt reached RUB 767.4 bn with a net debt/EBITDA ratio of 3.04. No dividends have been paid for four years, and the fair yield of 10.5% remains out of reach. The shares trade at a P/E of 1.16 and EV/EBITDA of 3.47 – cheap, but value realization requires either a dividend policy turnaround or completion of the investment programme. Verdict: neutral.
Open the company's financial profile HYDR →
See also: market overview · valuation map · stock screeners