Mosgorlombard: H1 net profit up 32.9%, but net interest income swung to -136.8%
Мосгорломбард 25 августа раскрыл результаты за первое полугодие 2026 года: чистая прибыль выросла на 32,9% год к году, до 860,2 млн руб. за последние 12 месяцев, при этом процентные доходы за полугодие упали на 136,8% – до отрицательных значений. На фоне этих противоречивых сигналов акция выглядит привлекательно: P/E LTM составляет 2,27, ROE – 53,2%, а дивидендная доходность за последние 12 месяцев – 13,99%, что выше нашей справедливой оценки в 10,5%.
Key takeaways
— Net interest income for H1 swung to -136.8% YoY – a reversal after two years of growth
— LTM net profit reached RUB 860.2 mn, with ROE at 53.2%
— Trailing 12-month dividend is RUB 0.28 per share, yield 13.8% vs. our fair 10.5%
— P/E LTM of 2.27 – the stock trades at a discount to its own historical multiples
— On the portal's model, the stock's upside is +55% to the current price
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Net interest income | 0.36 | -0.13 | -136.8% |
| Operating profit | 0.64 | 0.75 | +17.7% |
| Net profit | 0.41 | 0.55 | +32.9% |
| Capex | 0.05 | — | — |
| Net margin | 114.0% | — | — |
Net interest income for H1 swung to -136.8% YoY – a reversal after two years of growth
In H1 2026, Mosgorlombard's net interest income fell 136.8% YoY. This means the figure turned negative – the company pays more on liabilities than it earns on lending. For comparison, in Q3 2023 net interest income was RUB 187.76 mn, and in Q4 2023 it was RUB 216.78 mn, when the business was steadily profitable.
The reason for this reversal is not disclosed in the report, but it coincides with a period of high key rate, when funding costs rise faster than loan yields. If the trend continues, it will pressure margins in the coming periods. For now, the company compensates with growth in net profit from other items.
LTM net profit reached RUB 860.2 mn, with ROE at 53.2%
For the trailing twelve months (sum of two half-years to June 30, 2026), Mosgorlombard's net profit reached RUB 860.2 mn. This is a high level: return on equity is 53.2%, indicating extremely efficient use of capital. For comparison, in Q4 2023 net profit was RUB 111.36 mn, so the business has grown substantially over two years.
Net profit growth for H1 2026 was +32.9% YoY. This means the company is increasing profit despite the decline in interest income – likely due to fee and commission income, other operating items, or one-off factors. Details are not disclosed in the report, but the fact of growth matters to shareholders.
Trailing 12-month dividend is RUB 0.28 per share, yield 13.8% vs. our fair 10.5%
Over the last 12 months, Mosgorlombard paid RUB 0.28 per share, giving a dividend yield of 13.8%. Our model estimates a fair yield for this name at 10.5%, meaning the current yield is noticeably higher – the stock provides more cash flow than we consider necessary to compensate for risk.
The payout ratio is only 0.26 of profit – the company distributes just a quarter of earnings, retaining the rest for growth. This suggests the high payout level may be sustainable, and our model's next payout estimate is the same RUB 0.28 per share, implying a forward yield of 13.8%.
P/E LTM of 2.27 – the stock trades at a discount to its own historical multiples
Mosgorlombard trades at a P/E LTM of 2.27 with a market cap of RUB 1,949.71 mn. This is an extremely low multiple, especially for a company with ROE above 50%. Even if profit is adjusted for one-off factors, the valuation remains attractive.
The company's own history shows that multiples were higher in the past – for example, in 2023 with quarterly profit of RUB 16–111 mn, the capitalization was comparable or higher. The current discount likely reflects market concerns about declining interest income, but if profit stays at current levels, the stock is undervalued.
On the portal's model, the stock's upside is +55% to the current price
Our financial model, based on the ratio of ROE to P/B, shows that the fair value of Mosgorlombard's share is 55% above the current price. This means the market does not fully appreciate the company's ability to generate profit on capital.
The share is held in the portal's 'Banks & financials' (potential) strategy – this is a fact, but not an argument for a recommendation. The strategy selects stocks by its own criteria, and the current undervaluation is one reason for its presence on the list.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1.95 bn ₽ |
| P/E (LTM) | 2.3 |
| P/B | 1.10 |
| ROE | 53.2% |
| Dividend yield (12m) | 14.0% |
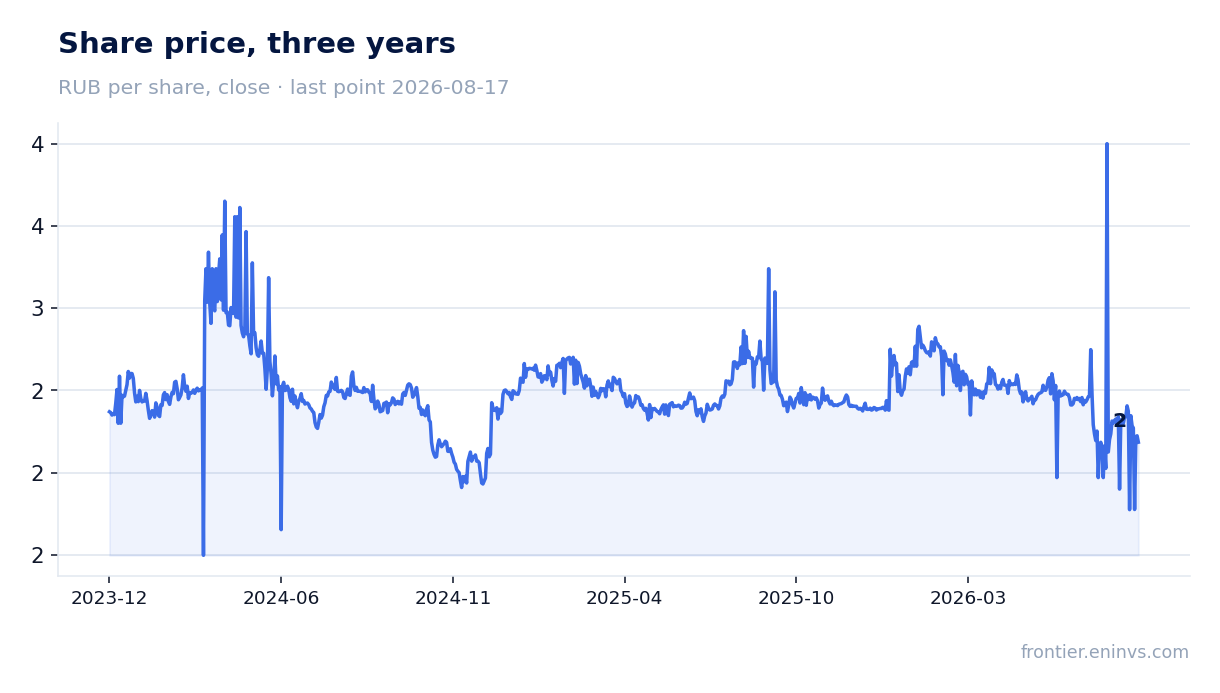
Bottom line
Mosgorlombard showed strong net profit growth in H1 2026 (+32.9% YoY), but this happened against a backdrop of a dramatic decline in net interest income (–136.8%), raising questions about sustainability. The company maintains high return on equity (53.2% LTM) and pays generous dividends (13.8% over 12 months), yet the payout ratio is only 0.26 – meaning the company could pay more if it wished. With P/E LTM of 2.27 and +55% upside on the portal's model, the stock looks attractive, but the key risk is further compression of interest margin. If net interest income recovers in the next report, the valuation could be revised upward; if not, current profit may prove to be peak.
Open the company's financial profile MGKL →
See also: market overview · valuation map · stock screeners