Mosgorlombard: profit up by a third, but it pays out more than it earns
On 3 November Mosgorlombard reported results for the second quarter of 2026. Net profit for the quarter came to RUB 275.3 mn, up 32.9% year on year, with interest income at RUB 617.8 mn and fee and commission income at RUB 684.7 mn. The stock trades at an LTM P/E of 0.73 and a dividend yield of 52.8%, yet it has fallen 71.1% since the release. The dividend record and the valuation look attractive, but the sustainability of payouts at that ratio is the central question, so the verdict on the share at the current price is rather attractive.
Key takeaways
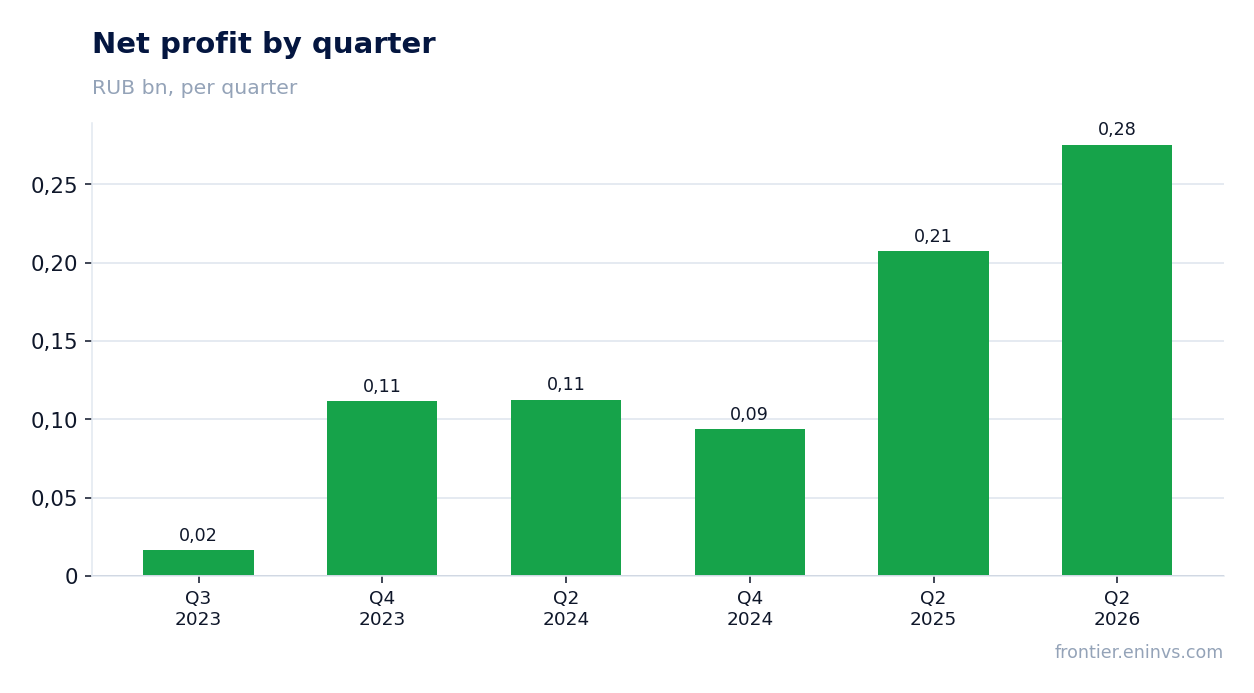
— Net profit for the second quarter of 2026 rose 32.9% to RUB 275.3 mn
— Fee and commission income of RUB 684.7 mn overtook interest income of RUB 617.8 mn for the first time
— Payouts of RUB 0.28 per share over the last 12 months give a 52.8% yield — five times the fair 10.5%
— An LTM P/E of 0.73 and an ROE of 46.5% price the stock below its own earnings
— On the portal's model the upside to fair value is +209%
— The share has lost 71.1% since the release, so the market has already priced doubt about the dividend
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | 0.18 | — | — |
| Net profit | 0.21 | 0.28 | +32.9% |
| Capex | 0.02 | — | — |
| Net margin | 114.0% | — | — |
Net profit for the second quarter of 2026 rose 32.9% to RUB 275.3 mn
Profit for the reported quarter came to RUB 275.3 mn against RUB 207.2 mn a year earlier — growth of 32.9%. This is the only valid gauge of momentum: the quarterly series in the facts ends early and has gaps, so its quarters cannot be compared with one another.
Profit rested on revenue: interest income reached RUB 617.8 mn and fee and commission income RUB 684.7 mn. Fee income was the larger of the two this quarter, which for a pawnshop business means a shift toward services that earn a commission rather than only interest on loans.
Profit of RUB 275.3 mn on that revenue implies a high margin, but the facts give no cost breakdown, so the source of the margin cannot be named. What matters more for a holder is that profit is rising while the share has fallen 71.1% since the release — the market is pricing the durability of future payouts, not the current quarter.
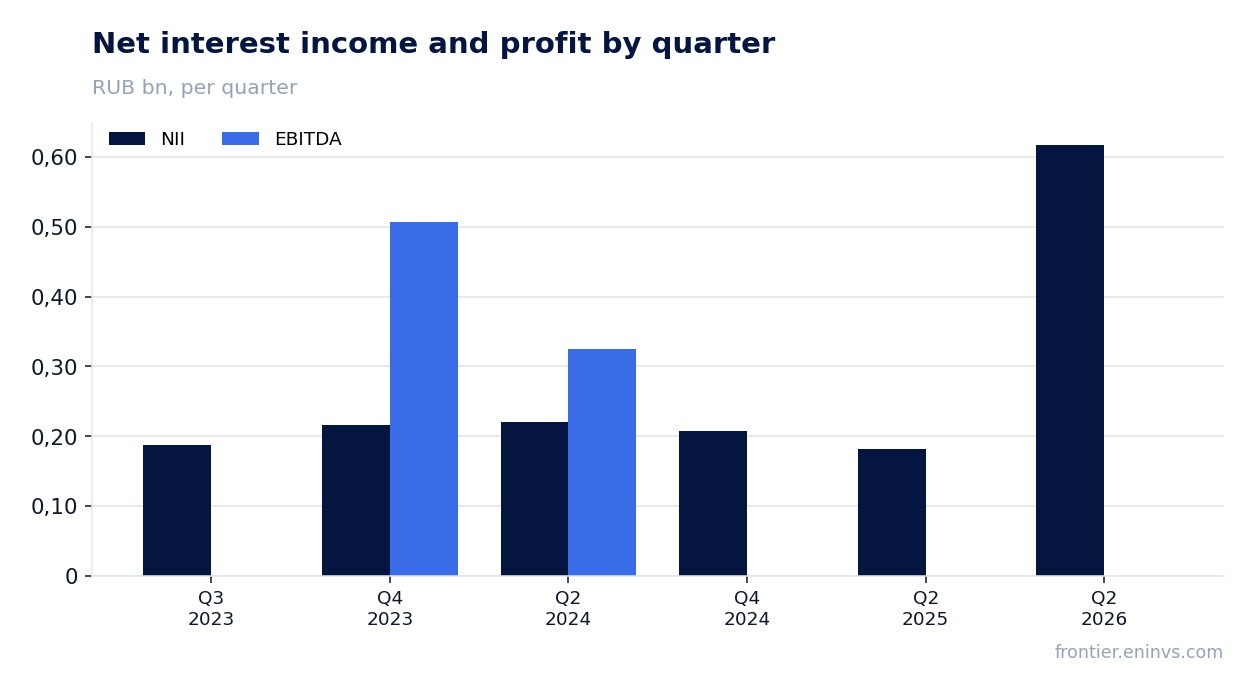
Fee and commission income of RUB 684.7 mn overtook interest income of RUB 617.8 mn for the first time
In the reported quarter fee and commission income came to RUB 684.7 mn and interest income to RUB 617.8 mn. Fees supplied more than half of combined revenue, which changes the revenue profile: interest on loans used to be the base, and now charges for services matter at least as much.
That structure is usually more resilient to the policy rate: fees do not depend on the 14.0% key rate as directly as interest income does. But it is also less predictable — the volume of fee-generating business is set by client flow, not by the size of the loan book.
A comparison with earlier periods is not possible: in the facts, fee income in earlier quarters was a few million roubles, but those figures belong to a different base and a different scale of business. It is enough to say that in the reported quarter fees became the main source of revenue.
Payouts of RUB 0.28 per share over the last 12 months give a 52.8% yield — five times the fair 10.5%
Over the last 12 months RUB 0.28 per share was paid, the dividend for 2026 by ex-date. The current yield is 52.8%, against the 10.5% we consider fair for this name. The fivefold gap is the main argument for the share.
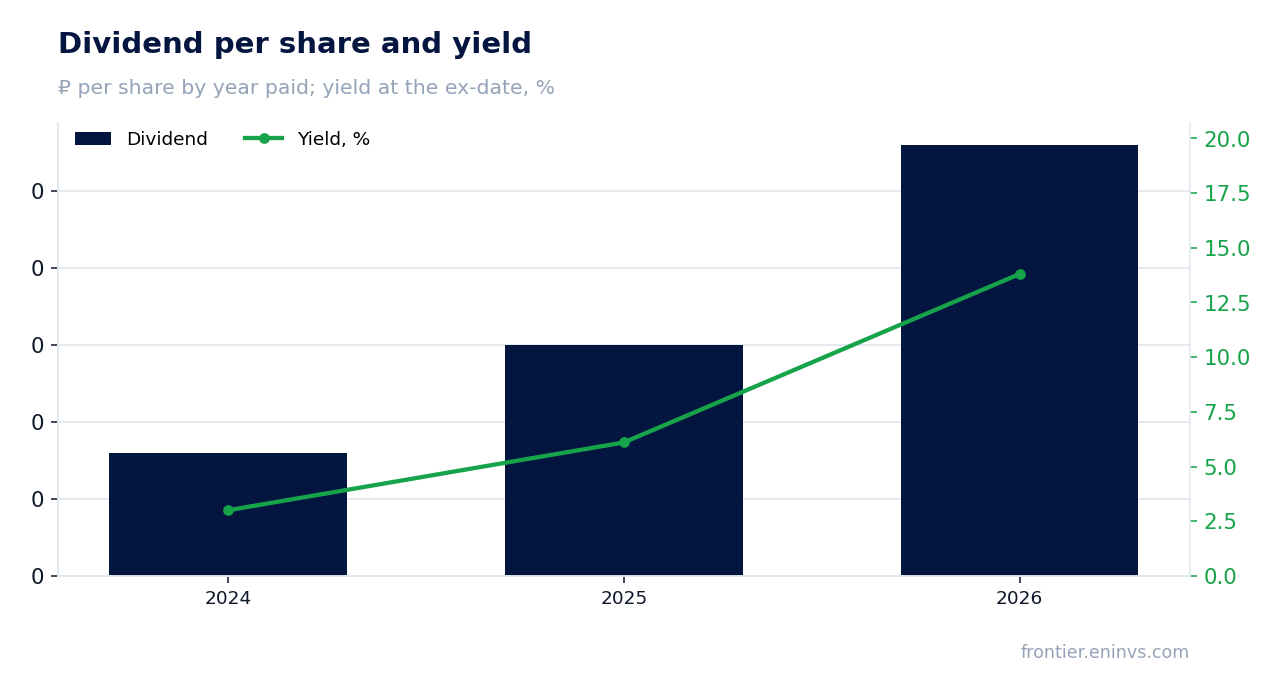
The payout record is rising: RUB 0.08 for 2024, RUB 0.15 for 2025 and RUB 0.28 for 2026. The yield at the ex-date rose from 3.0% to 6.1% and then 13.8% — the payout grew faster than the price fell, which kept the yield up even as the share declined.
Our estimate for the coming year is the same RUB 0.28 per share: the model assumes a payout of 0.22 of profit, and the amount already paid equals the annual estimate. Everything rests on the payout ratio and the profit base: with profit of RUB 724.0 mn over the last 12 months, a payout of 0.22 of it looks affordable, but any one-off item in profit puts it in question at once.
The benchmark is the 14.0% key rate. A 52.8% yield is three times that, and that is not a normal risk premium but the market's signal that a payout of this size is not seen as sustainable. A smaller payout could come from lower profit, one-off write-offs or a policy shift toward retaining capital.
An LTM P/E of 0.73 and an ROE of 46.5% price the stock below its own earnings
Market capitalisation is RUB 527.0 mn against profit of RUB 724.0 mn over the last 12 months. That gives an LTM P/E of 0.73: the market pays less for the company than it earned in a year. With a return on equity of 46.5%, such a valuation means the market does not believe the profit will repeat.
A comparison with its own history is not possible: the facts contain no three-year average multiple. Even without it, the discount to earnings is unusually deep — at an ROE of 46.5% the equity pays back in a little over two years if the profit holds.
For a bank or a broker a cheap P/E often reflects asset-quality risk rather than undervaluation. This looks like the same case: profit is high, but the stock trades at 0.73 of it precisely because the market prices the risk that it falls.
On the portal's model the upside to fair value is +209%
On the portal's model, which sets return on equity against price to book, the upside of the share to fair value is +209%. This is our own estimate, not a market consensus and not a target price.
The model rests on profit and equity — the same quantities that give the P/E of 0.73 and the ROE of 46.5%. If profit is durable, the discount really is anomalous; if profit is one-off, the model overstates fair value.
The market has knocked the share down 71.1% since the release, and that gap with the model is not a model error but a difference in assumptions about future profit. Only the next report can show which side is right.
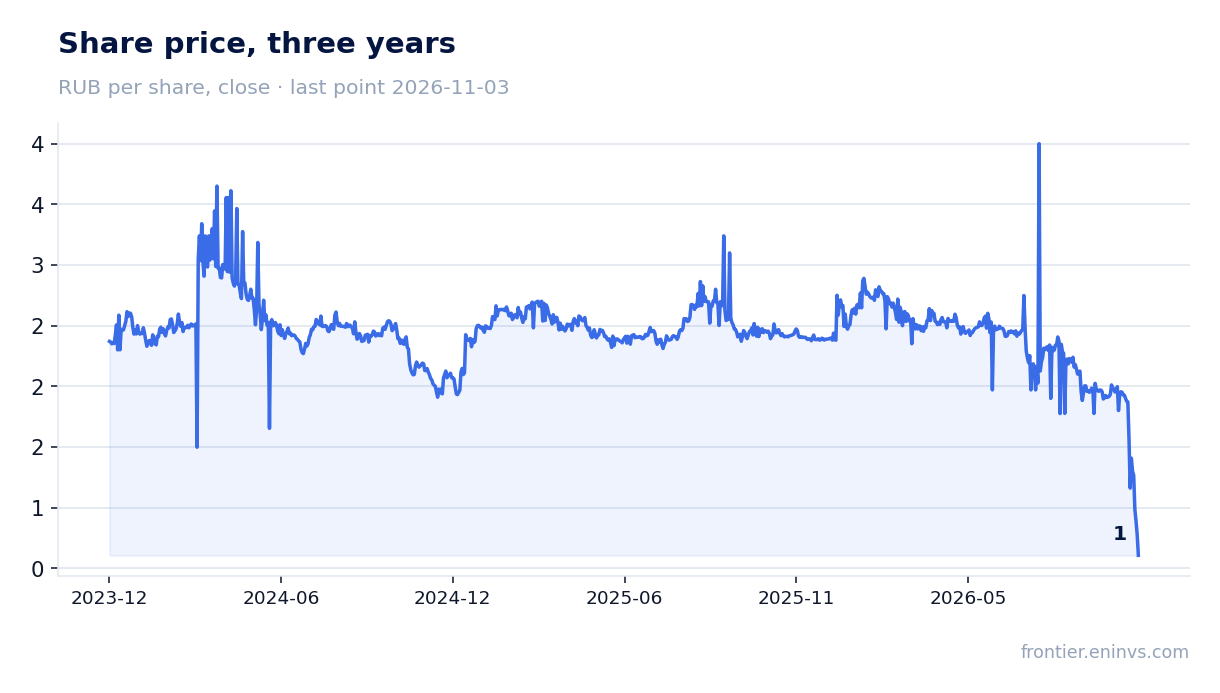
The share has lost 71.1% since the release, so the market has already priced doubt about the dividend
On the release day the share added 1.0%, and from the release to 3 November 2026 it lost 71.1%. The close before the release was RUB 2.1005. A fall of that size alongside 32.9% profit growth means the market re-rated not the result but the risk to payouts.
The market's logic shows in the yield: 52.8% against a 14.0% key rate is the price of fear, not a premium. If investors believed the RUB 0.28 payout would hold, the stock would not trade at 0.73 of earnings.
What to watch in the next report: whether fee income stays above interest income and whether profit remains at a level where a payout of 0.22 of it does not require giving up capital. Confirmation of both would remove the main argument against the share.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 0.53 bn ₽ |
| P/E (LTM) | 0.7 |
| P/B | 0.30 |
| ROE | 46.5% |
| Dividend yield (12m) | 52.8% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2024 | 0.08 | 3.0% |
| 2025 | 0.15 | 6.1% |
| 2026 | 0.28 | 13.8% |
Bottom line
What was strong in the report belongs to the current quarter: profit rose 32.9% to RUB 275.3 mn, and fee income of RUB 684.7 mn overtook interest income for the first time. What was weak is what sits behind the price: the share has lost 71.1% since the release, and a 52.8% yield against a fair 10.5% says the market does not believe the payout will repeat. A P/E of 0.73 and an ROE of 46.5% make the stock cheap, and the portal's model shows +209% upside, but that discount is the price of profit risk, not a gift. Verdict: rather attractive — the dividend and the valuation outweigh, but only as long as profit holds at the level from which 0.22 is paid.
Open the company's financial profile MGKL →
See also: market overview · valuation map · stock screeners