Novatek: revenue and EBITDA grow, but net profit declines due to taxes
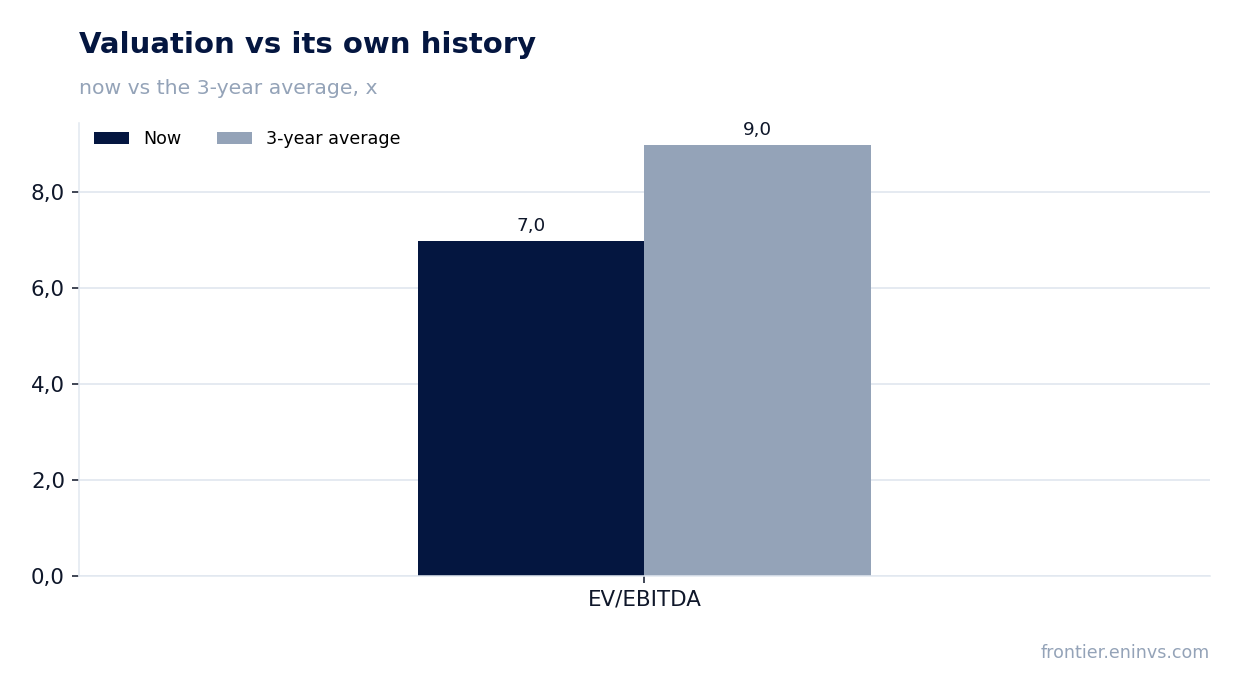
On July 24, Novatek released its results for the first half of 2026. Revenue increased by 4.0% to RUB 836.3 billion, EBITDA by 5.3% to RUB 225.9 billion, but net profit fell by 2.8% to RUB 218.7 billion due to higher tax payments. At the current price, the shares look attractive: the EV/EBITDA multiple (7.5x) is below its own three-year average (9.0x), and the dividend yield (8.5%) is close to the fair level (10.5%), supporting upside potential according to the portal's model.
Key takeaways
— Revenue for the first half increased by 4.0% to RUB 836.3 billion, driven by higher hydrocarbon sales
— EBITDA grew by 5.3% to RUB 225.9 billion, with margin at 27.0% versus 26.7% a year earlier
— Net profit declined by 2.8% to RUB 218.7 billion due to higher taxes, unrelated to operating performance
— Operating cash flow for the half-year amounted to RUB 172.2 billion, down from RUB 195.7 billion a year earlier
— Debt burden remains negative: net debt is -RUB 39.3 billion, and the ratio to EBITDA for 12 months is -0.1
— Dividend yield for 12 months is 8.5%, below the fair level of 10.5% for the company
— According to the portal's model, the share has upside potential to fair value of 104%
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 804 | 836 | +4.0% |
| EBITDA | 215 | 226 | +5.3% |
| Operating profit | 155 | 171 | +10.1% |
| Net profit | 227 | 221 | -2.8% |
| Operating cash flow | 196 | 172 | -12.0% |
| EBITDA margin | 26.7% | 27.0% | +0.3 pp |
| Net margin | 28.3% | 26.4% | -1.9 pp |
Revenue for the first half increased by 4.0% to RUB 836.3 billion, driven by higher hydrocarbon sales
For the first half of 2026, Novatek's revenue amounted to RUB 836.3 billion, up 4.0% from the same period a year earlier. The main contribution came from hydrocarbon sales – RUB 816.6 billion, up 4.3% from the previous year. Other revenue declined by 7.1% to RUB 19.7 billion, but its share in the total is insignificant.
The growth in hydrocarbon sales reflects both pricing conditions and higher sales volumes. The company does not disclose segment details in the interim report, but the revenue dynamics are consistent with a moderate increase in gas and liquid hydrocarbon prices on export markets.
EBITDA grew by 5.3% to RUB 225.9 billion, with margin at 27.0% versus 26.7% a year earlier
EBITDA for the first half reached RUB 225.9 billion, up 5.3% from the previous year. The EBITDA margin expanded from 26.7% to 27.0%, indicating effective control over operating expenses. EBITDA growth outpaced revenue growth, leading to improved profitability.
The main factor was a slowdown in cost growth: materials, services and other expenses rose by 15.9% to RUB 40.5 billion, but this was offset by a 9.5% decline in other operating expenses to RUB 416.2 billion. As a result, operating profit increased by 10.1% to RUB 170.7 billion.
Net profit declined by 2.8% to RUB 218.7 billion due to higher taxes, unrelated to operating performance
Despite growth in operating metrics, net profit for the first half fell by 2.8% to RUB 218.7 billion. The reason is a sharp increase in tax payments: taxes other than income tax and other budget payments rose by 51.7% to RUB 153.5 billion, and current income tax expenses increased by 43.2% to RUB 60.1 billion.
The increase in tax payments is likely due to changes in tax legislation or one-off factors, but the company does not disclose details. As a result, net margin declined from 28.3% to 26.4%, despite improved operating efficiency.
Operating cash flow for the half-year amounted to RUB 172.2 billion, down from RUB 195.7 billion a year earlier
Operating cash flow for the first half of 2026 amounted to RUB 172.2 billion, down 12.0% from a year earlier (RUB 195.7 billion). The decline is due to higher tax payments and changes in working capital, which affected the cash position.
Investment spending fell to RUB 43.9 billion from RUB 70.9 billion, partially offsetting the decline in operating cash flow. Financial flow was negative at RUB 154.9 billion due to dividend payments, leading to a decrease in cash of RUB 26.3 billion over the half-year.
Debt burden remains negative: net debt is -RUB 39.3 billion, and the ratio to EBITDA for 12 months is -0.1
At the end of the first half of 2026, Novatek's net debt amounted to -RUB 39.3 billion, meaning cash exceeds debt obligations. The ratio of net debt to EBITDA for the last 12 months is -0.1, indicating an extremely low debt burden.
Over the last 12 months, net debt decreased by RUB 149.8 billion, reflecting strong cash flow and moderate capital expenditures. The company maintains financial stability, allowing it to sustain a generous dividend policy.
Dividend yield for 12 months is 8.5%, below the fair level of 10.5% for the company
Over the last 12 months, Novatek paid dividends of RUB 82.73 per share, providing a yield of 8.5%. Our model forecast assumes a similar payout in the next period, giving a forward yield of 8.5%.
However, the fair yield for this stock, in our view, is 10.5%, which is higher than the current level. This means the market is valuing the share at a premium to our target yield, and to achieve fair yield the price must decline or dividends must rise.
According to the portal's model, the share has upside potential to fair value of 104%
Our portal's model, based on repricing EBITDA at current commodity prices and a target EV/EBITDA multiple, shows that the share has upside potential to fair value of 104%. This significantly exceeds the current market price, making the stock attractive for long-term investors.
The share is included in the 'RU Commodity-Upside' strategy on our portal, reflecting its compliance with selection criteria based on commodity potential. However, it should be noted that the model is based on our assumptions and is not a market consensus.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 3 047 bn ₽ |
| P/E (LTM) | 17.0 |
| EV/EBITDA (LTM) | 7.5 |
| P/B | 1.07 |
| Net debt / EBITDA (LTM) | -0.10 |
| Operating cash flow (LTM) | 480 bn |
| ROE | 15.3% |
| Dividend yield (12m) | 8.1% |
| EV/EBITDA, 3-year average | 9.0 |
Bottom line
In the first half of 2026, Novatek demonstrated solid revenue and EBITDA growth, supported by margin expansion. However, net profit declined due to higher tax payments, a one-off factor unrelated to operating performance. The debt burden remains negative, and cash flow covers investments and dividends. At the current price, the share trades at a discount to its own history on EV/EBITDA, and the dividend yield is close to fair. Our verdict is that the share is attractive, with upside potential of 104% according to the portal's model, but tax policy remains a key risk.
Open the company's financial profile NVTK →
See also: market overview · valuation map · stock screeners