OZON: revenue accelerated to +62.7%, but EBITDA margin compressed to 13.8%
On November 25, OZON released its third-quarter 2026 results. Revenue rose 62.7% year on year to RUB 421.2 bn, EBITDA – by 49.4% to RUB 58.3 bn, but its margin fell to 13.8% from 15.1% a year earlier. Growth accelerated versus the second quarter (+46.8%), while leverage at 1.53x LTM EBITDA remains moderate. At the current price the share looks rather attractive: revenue growth is accelerating and a 5.9% dividend yield supports holders.
Key takeaways
— Q3 revenue grew 62.7% year on year to RUB 421.2 bn, an acceleration from 46.8% in Q2
— EBITDA rose 49.4% year on year, but its margin compressed to 13.8% from 15.1% a year earlier
— Net debt rose to RUB 278.8 bn on September 30, 2026 from RUB 239.3 bn on June 30, with net debt/LTM EBITDA at 1.53x
— Dividends paid over the last 12 months amounted to RUB 213.55 per share, a 5.9% yield
— The portal's model puts upside to fair value at +55%
— The share is held in the portal's live model strategies: RU AI conviction, RU AI long-short and RU Growth-stories
Attractiveness
Key figures, RUB bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 259 | 421 | +62.7% |
| EBITDA | 39.0 | 58.3 | +49.4% |
| Operating profit | 17.8 | — | — |
| Net profit | -157 | — | — |
| Operating cash flow | 173 | — | — |
| Capex | 13.5 | — | — |
| EBITDA margin | 15.1% | 13.8% | -1.3 pp |
| Net margin | -60.5% | — | — |
Q3 revenue grew 62.7% year on year to RUB 421.2 bn, an acceleration from 46.8% in Q2
OZON's Q3 2026 revenue reached RUB 421.2 bn, up 62.7% year on year. In Q2 growth was slower at 46.8%, so the current quarter shows acceleration. This is the highest growth rate in the last four quarters: 48.9% in Q1 2026 and 44.1% in Q4 2025.
The acceleration matters for valuation: it means the business is scaling faster than the previous quarters' trend implied. The absolute quarterly revenue increase of about RUB 162 bn is comparable to the company's entire quarterly revenue two years ago.
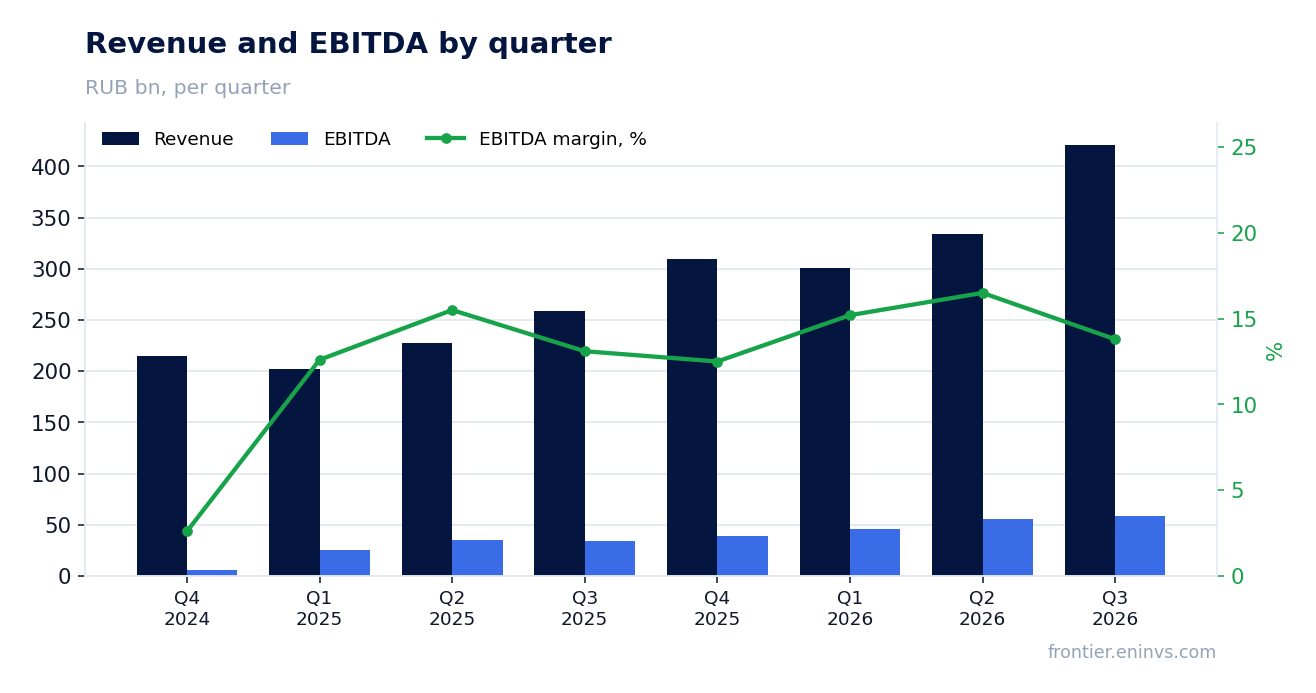
EBITDA rose 49.4% year on year, but its margin compressed to 13.8% from 15.1% a year earlier
Q3 2026 EBITDA came in at RUB 58.3 bn, up 49.4% year on year. However, EBITDA growth lags revenue growth (+62.7%), pushing the margin down to 13.8% from 15.1% in Q3 2025.
The 1.3 percentage point margin compression means costs are rising faster than revenue. The company did not disclose in the provided facts which cost line drove this, so we state the fact: EBITDA is growing in absolute terms, but efficiency per ruble of revenue declined. For an investor this signals that scaling is not yet accompanied by improving profitability.
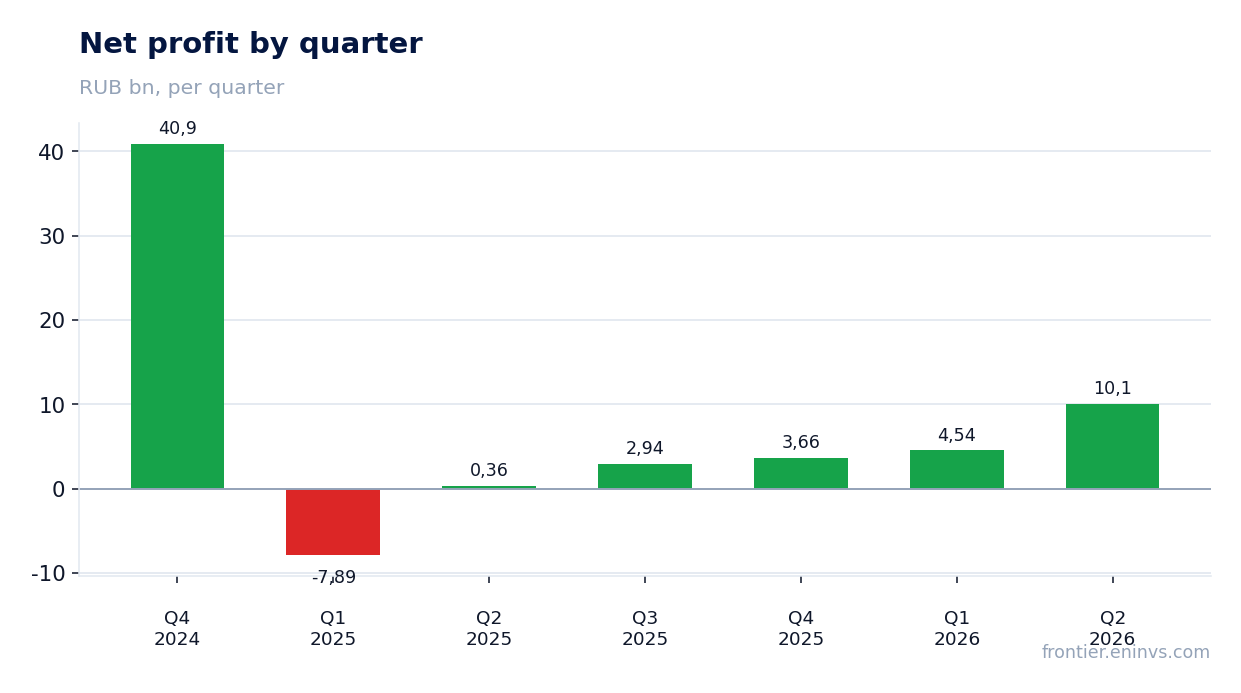
Net debt rose to RUB 278.8 bn on September 30, 2026 from RUB 239.3 bn on June 30, with net debt/LTM EBITDA at 1.53x
Net debt on September 30, 2026 stood at RUB 278.8 bn, up RUB 39.5 bn from RUB 239.3 bn on June 30, 2026. Over the year, from RUB 170.2 bn on September 30, 2025, debt rose by RUB 108.7 bn. Debt growth accompanies business expansion but requires monitoring.
The net debt to LTM EBITDA ratio is 1.53x. This is a moderate level that leaves room for further growth financing. The facts do not include earlier values of this ratio, so we do not assess its direction.
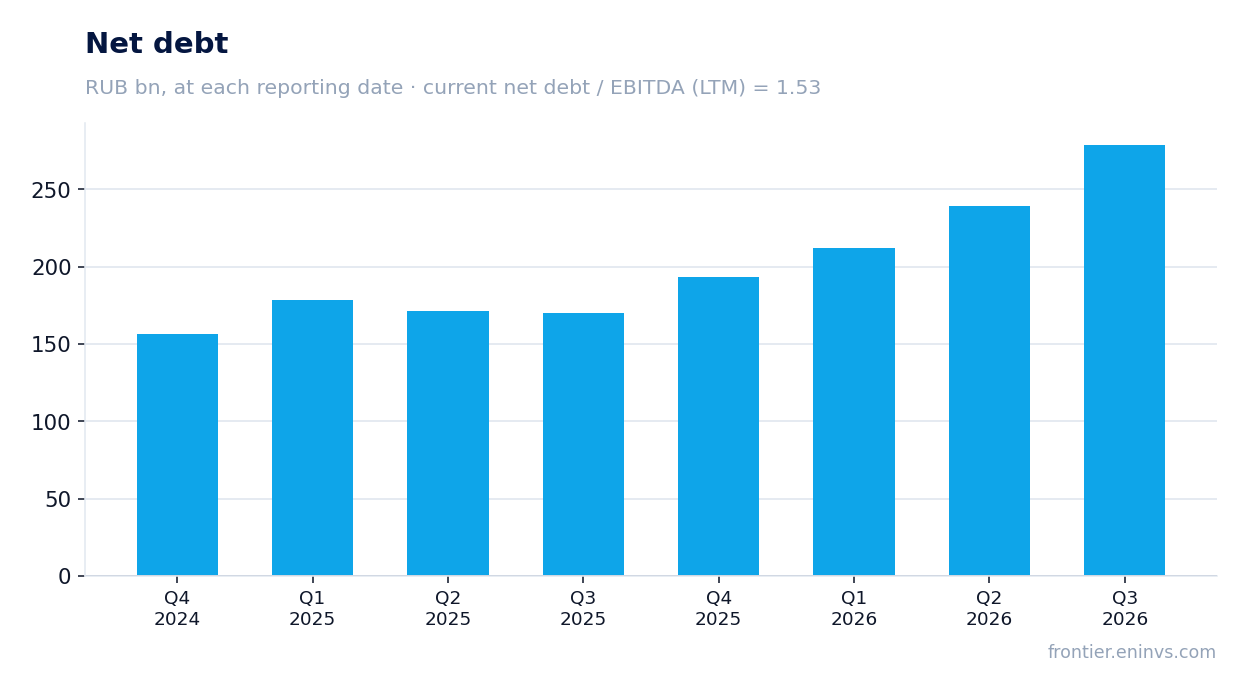
Dividends paid over the last 12 months amounted to RUB 213.55 per share, a 5.9% yield
Over the last 12 months OZON paid dividends of RUB 213.55 per share, giving a current yield of 5.9%. In 2026 the payout was RUB 70.0 per share with a 1.7% yield at the ex-date, and in 2025 – RUB 143.55 with a 3.4% yield.
For a dividend history these are substantial payments. The 5.9% yield is well above the 2025 and 2026 levels, reflecting both the dividend growth and the current share price. The company remains a growth story, and payouts may vary depending on profit and investment needs. Our estimate for the current year assumes payouts remain at the last-12-month level, provided profit and cash flow support them.
The portal's model puts upside to fair value at +55%
The portal's model, which compares EBITDA growth with a target multiple and market capitalization, puts the upside to fair value at +55%. This is the portal's own estimate, not a market consensus or a target price.
The current EV/EBITDA LTM multiple is 5.54x, and P/E LTM is 38.52x. For a growing company with accelerating revenue these levels look moderate, especially given the dividend yield. However, the facts do not include a comparison with the company's own multiple history, so we limit ourselves to stating current values.
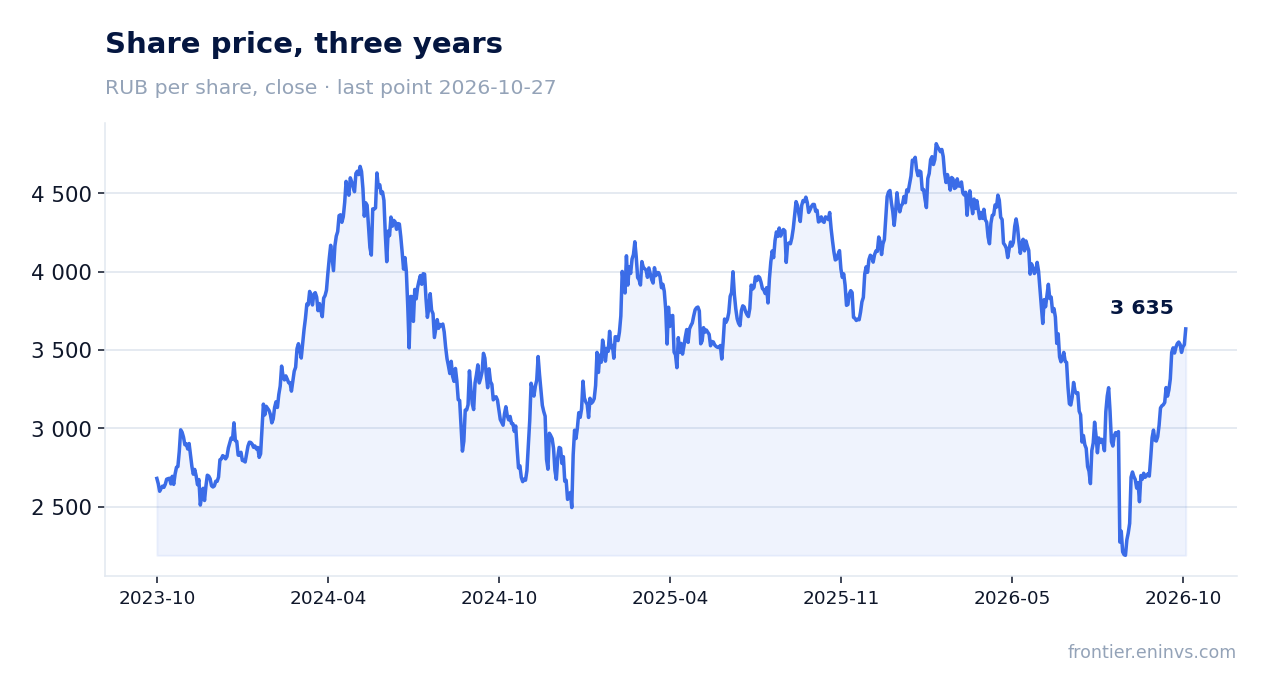
The share is held in the portal's live model strategies: RU AI conviction, RU AI long-short and RU Growth-stories
OZON is included in three live model strategies on the portal: RU AI conviction (Claude), RU AI long-short (market-neutral) and RU Growth-stories (GARP). Inclusion reflects passing these strategies' screens and is not an argument for the verdict.
For holders this means the share is present in model portfolios, but each investor makes their own buy or sell decision based on their goals and constraints.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 818 bn ₽ |
| P/E (LTM) | 38.5 |
| EV/EBITDA (LTM) | 5.5 |
| Net debt / EBITDA (LTM) | 1.53 |
| ROE | -26.2% |
| Dividend yield (12m) | 5.7% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2025 | 143.55 | 3.4% |
| 2026 | 70.00 | 1.7% |
Bottom line
The strong point of the report was revenue growth of 62.7% year on year with acceleration versus Q2. However, EBITDA grew slower at 49.4%, and the margin compressed to 13.8%. Leverage at 1.53x LTM EBITDA remains moderate, and a 5.9% dividend yield supports holders. The portal's model puts upside at +55%. Verdict – rather attractive: revenue acceleration and the dividend outweigh the margin compression, but margin sustainability remains the key question.
Open the company's financial profile OZON →
See also: market overview · valuation map · stock screeners