Positive: revenue up 38.9%, but profit was almost entirely eaten by interest and amortisation
On 27 July, Positive Group reported results for the second quarter of 2026. Revenue rose 38.9% year on year to RUB 6,127.5 mn, EBITDA reached RUB 1,006.6 mn against a negative figure a year earlier, while net profit was symbolic at RUB 24.2 mn, a 0.4% margin. The stock trades below its own three-year history on EV/EBITDA but still earns little: at the current price the share looks rather attractive than not, and the decisive question is whether shipment growth turns into sustainable profit.
Key takeaways
— Revenue rose 38.9% but decelerated from 45.6% a quarter earlier
— EBITDA turned positive, with a 16.4% margin replacing minus 20.4% a year earlier
— Net profit of RUB 24.2 mn was almost entirely absorbed by interest and amortisation
— Operating cash flow went negative at RUB 2,541.0 mn with capex of RUB 1,814.6 mn
— Net debt rose from RUB 7.0 bn on 31 March to RUB 13.1 bn on 30 June
— No dividends were paid over the last 12 months, and none are pencilled in for this year
— On EV/EBITDAC the stock trades at 10.1 against a three-year EV/EBITDA average of 15.5
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 4.41 | 6.13 | +38.9% |
| EBITDA | -0.90 | 1.01 | to profit |
| Operating profit | -1.61 | 0.14 | to profit |
| Net profit | -2.24 | 0.02 | to profit |
| Operating cash flow | 2.74 | -2.54 | -192.8% |
| Capex | 1.95 | 1.81 | -7.0% |
| EBITDA margin | -20.4% | 16.4% | +36.8 pp |
| Net margin | -50.8% | 0.4% | +51.2 pp |
Revenue rose 38.9% but decelerated from 45.6% a quarter earlier
In the second quarter of 2026, Positive Group's revenue reached RUB 6,127.5 mn, up 38.9% year on year. This is a strong result, but it is slower than the first quarter's 45.6% growth. The deceleration is a natural consequence of a high base: a year earlier revenue had already grown 42.0%.
The main contribution came from IT product licences: over the three months their sales were RUB 4,507.7 mn against RUB 3,221.4 mn a year earlier. Hardware-software systems grew to RUB 793.5 mn from RUB 264.6 mn, and information security services to RUB 820.8 mn from RUB 782.7 mn. Other revenue fell to RUB 5.4 mn from RUB 144.3 mn, but its share is small.
For the first half of 2026, revenue reached RUB 9,541.5 mn against RUB 6,757.0 mn a year earlier. Shipments over the six months were RUB 10,676.9 mn, above revenue: the difference between shipments and revenue is negative at minus RUB 366.6 mn, meaning part of sales is recognised in revenue later, as licences are renewed and services are rendered.
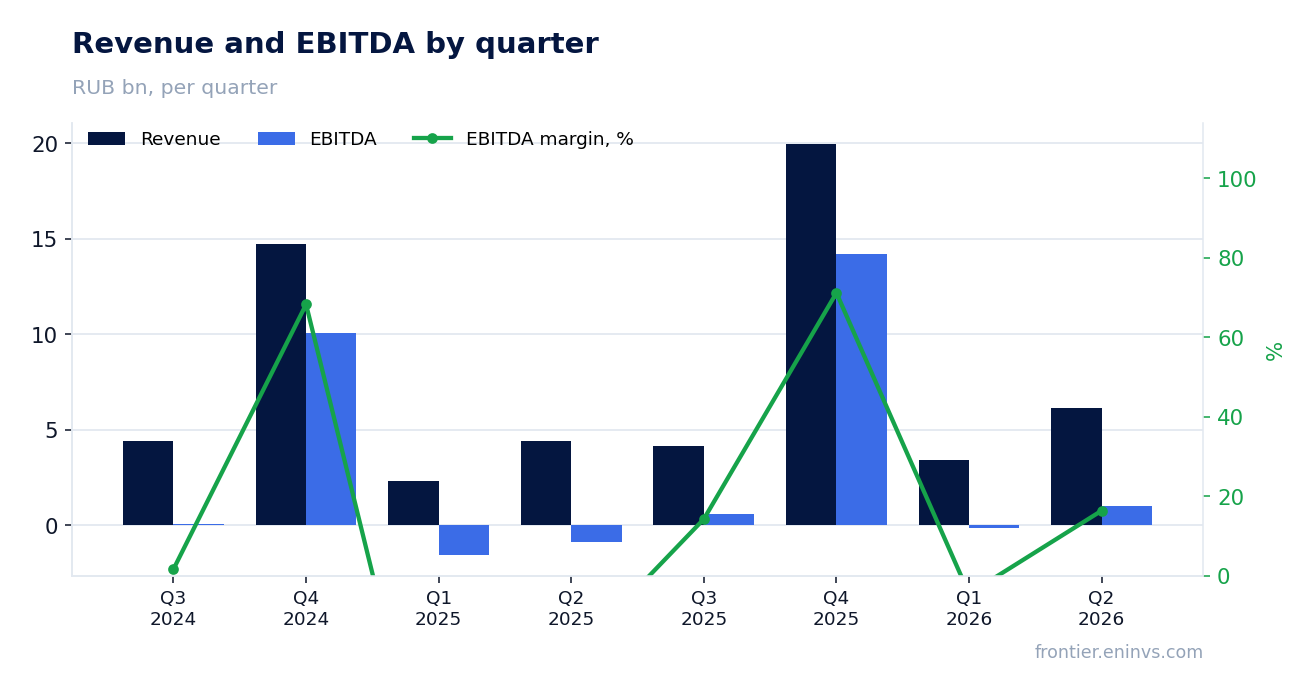
EBITDA turned positive, with a 16.4% margin replacing minus 20.4% a year earlier
In the second quarter of 2026, EBITDA was RUB 1,006.6 mn, with an EBITDA margin of 16.4%. A year earlier EBITDA was negative and the margin was minus 20.4%. Operating profit also turned positive at RUB 144.4 mn against a loss of RUB 1,613.6 mn a year earlier.
The margin improvement came with lower operating expenses: for the six months of 2026 they were RUB 8,140.1 mn against RUB 8,926.4 mn a year earlier. Research and development costs fell to RUB 2,001.7 mn from RUB 2,313.2 mn, and industry events and business development costs to RUB 854.2 mn from RUB 1,503.6 mn. Selling expenses, however, rose to RUB 2,977.2 mn from RUB 2,576.5 mn.
Gross profit for the quarter was RUB 4,738.5 mn against RUB 3,466.4 mn a year earlier. Cost of sales rose to RUB 1,389.1 mn from RUB 946.5 mn, partly due to amortisation of internally generated intangibles of RUB 652.7 mn against RUB 547.8 mn a year earlier.
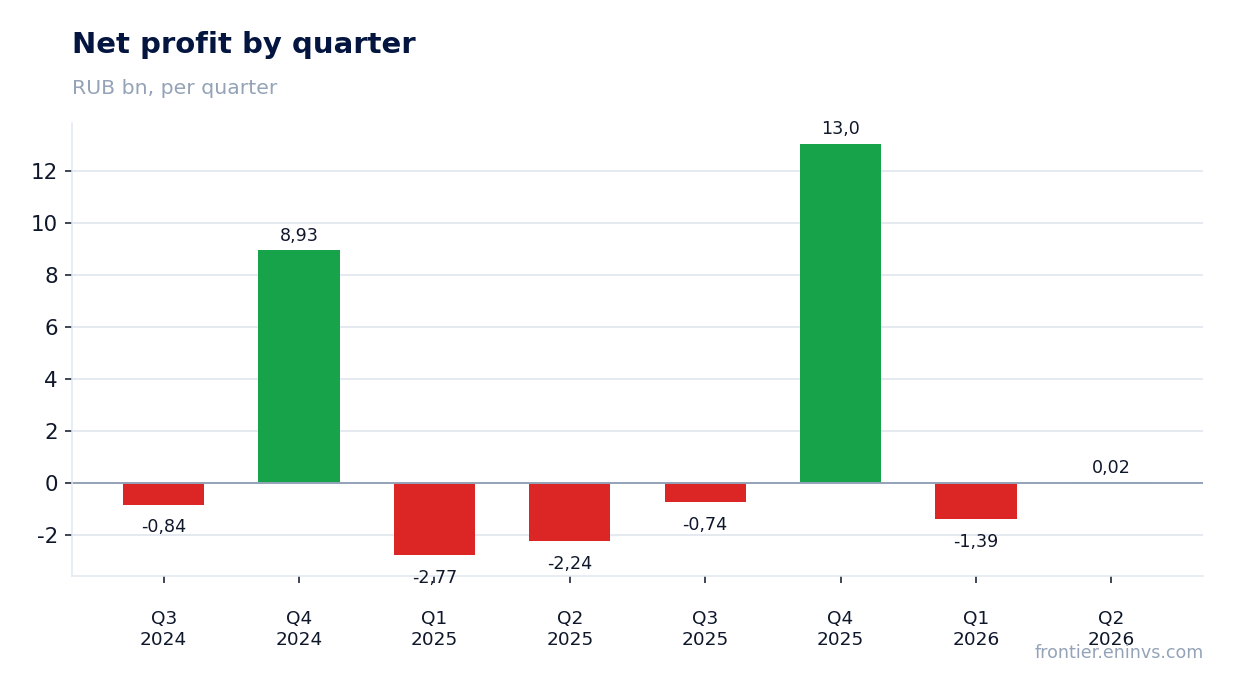
Net profit of RUB 24.2 mn was almost entirely absorbed by interest and amortisation
Net profit in the second quarter of 2026 was RUB 24.2 mn, a 0.4% margin. A year earlier there was a loss of RUB 2,242.4 mn with a minus 50.8% margin. Profit before tax was RUB 162.5 mn, income tax RUB 138.3 mn.
The main burden was interest expense: RUB 415.8 mn for the quarter against RUB 921.2 mn a year earlier. Interest income was RUB 427.9 mn against RUB 511.5 mn. Amortisation of internally generated intangibles for the quarter reached RUB 652.7 mn, comparable to operating profit.
For the first half of 2026, the net loss was RUB 1,364.2 mn against RUB 5,016.6 mn a year earlier. Loss per share was RUB 19.16 against RUB 70.44 a year earlier. The gap between quarterly profit and half-year loss is explained by seasonality: the bulk of sales falls in the fourth quarter.
Operating cash flow went negative at RUB 2,541.0 mn with capex of RUB 1,814.6 mn
In the second quarter of 2026, operating cash flow was negative at minus RUB 2,541.0 mn, with capital expenditure of RUB 1,814.6 mn. For comparison, a quarter earlier the flow was positive at RUB 16,190.6 mn, driven by payments from large contracts. For the first half of 2026, the flow was RUB 13,649.6 mn against RUB 5,476.9 mn a year earlier.
The negative flow in the second quarter reflects the seasonality of settlements: much of the first quarter's revenue was paid for, while new second-quarter shipments had not yet converted into cash. Trade and other receivables at 30 June 2026 were RUB 7,829.4 mn against RUB 24,153.3 mn at the end of 2025.
Capital expenditure was mainly directed at creating intangibles: over the six months of 2026 this absorbed RUB 3,609.8 mn against RUB 3,510.4 mn a year earlier. Purchases of property, plant and equipment amounted to only RUB 82.3 mn.
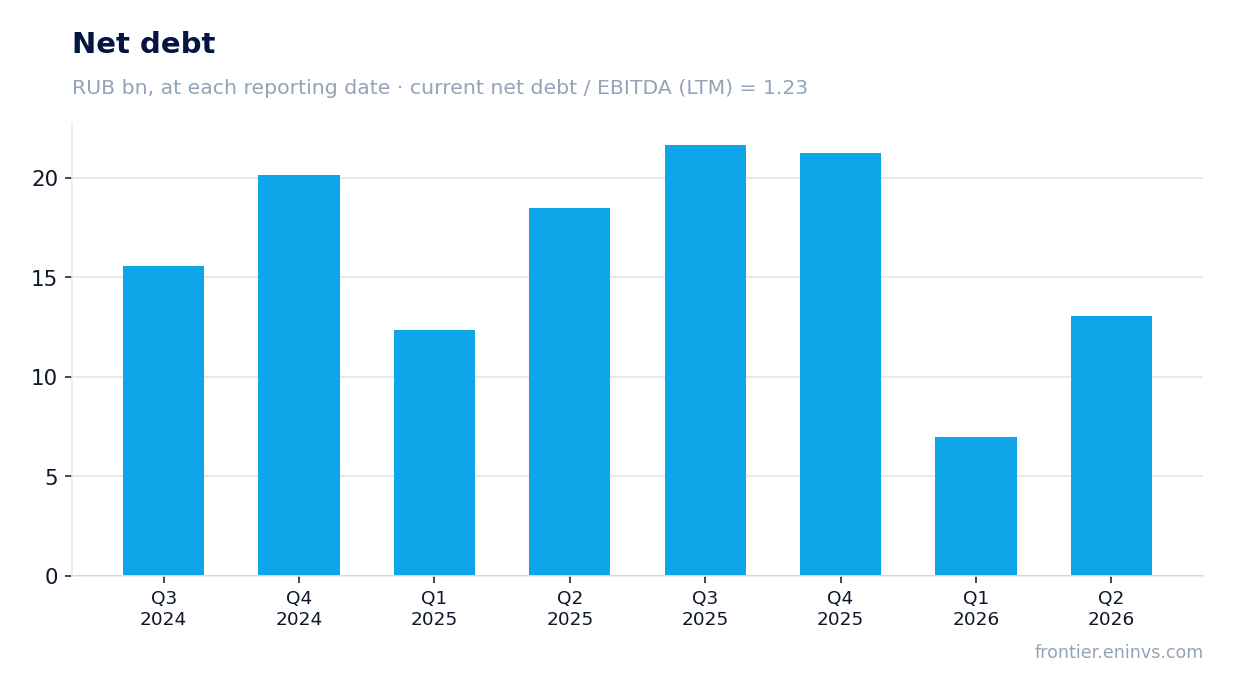
Net debt rose from RUB 7.0 bn on 31 March to RUB 13.1 bn on 30 June
Net debt at 30 June 2026 was RUB 13.1 bn, up from RUB 7.0 bn on 31 March 2026, a change of RUB 6.1 bn. Over twelve months net debt declined: from RUB 18.5 bn on 30 June 2025 to RUB 13.1 bn on 30 June 2026, a change of RUB 5.4 bn.
The net debt to EBITDA LTM ratio is 0.76. This is a moderate level, but it cannot be compared with a previous value: no earlier value of this ratio is in the facts. Total debt at 30 June 2026 was RUB 19,829.2 mn, cash and equivalents RUB 7,333.7 mn.
Interest expense for the quarter was RUB 415.8 mn, comparable to operating profit of RUB 144.4 mn. High debt remains the main constraint on net profit, despite the rate cut: the central bank key rate is 14.0%.
No dividends were paid over the last 12 months, and none are pencilled in for this year
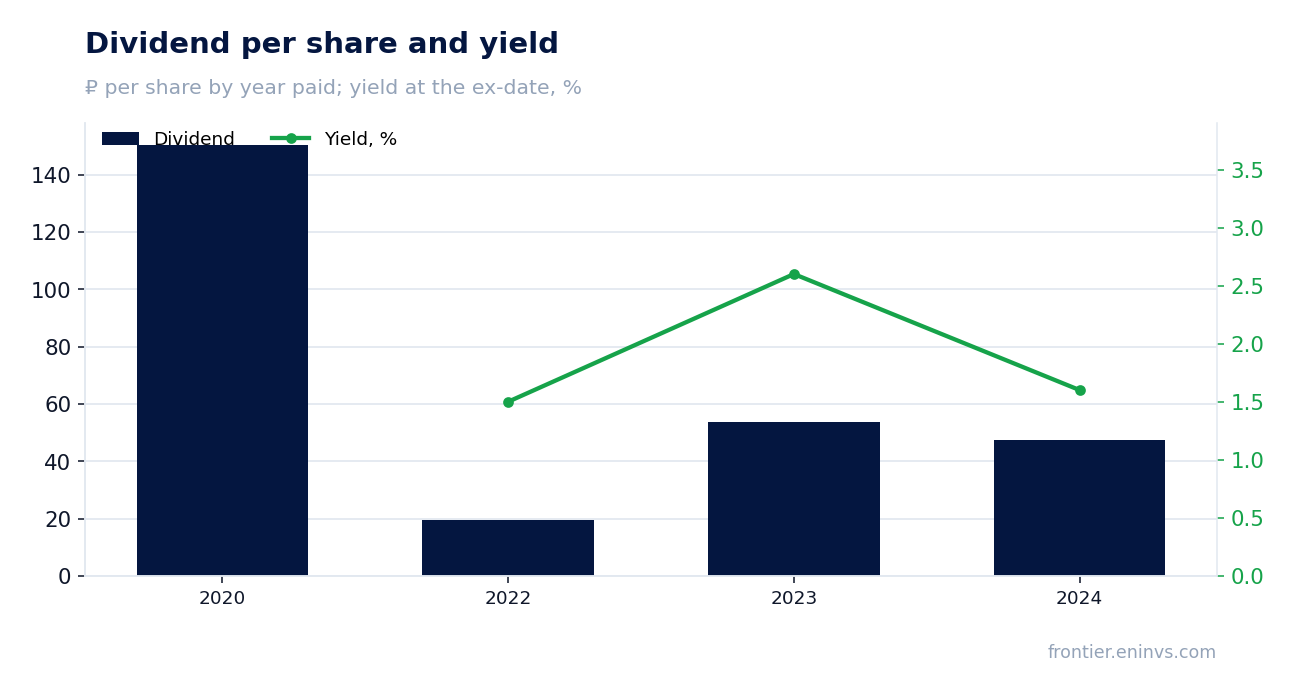
No dividends were paid over the last 12 months. There were also no payments in the current calendar year, and no further payouts are planned. Historically, payments were: RUB 47.3 per share in 2024, RUB 53.67 in 2023, RUB 19.56 in 2022, and RUB 150.44 in 2020.
Our estimate of a fair yield for this name is 7.0%. At the current price and LTM profit, the implied payout ratio is 0.64 of profit. However, the company directs significant funds to capitalised development and debt servicing, which limits the dividend base.
The central bank key rate is 14.0%, and with no dividends the stock offers no current income. A resumption of payouts is possible with sustainable net profit growth and lower debt, but there are no such signals yet.
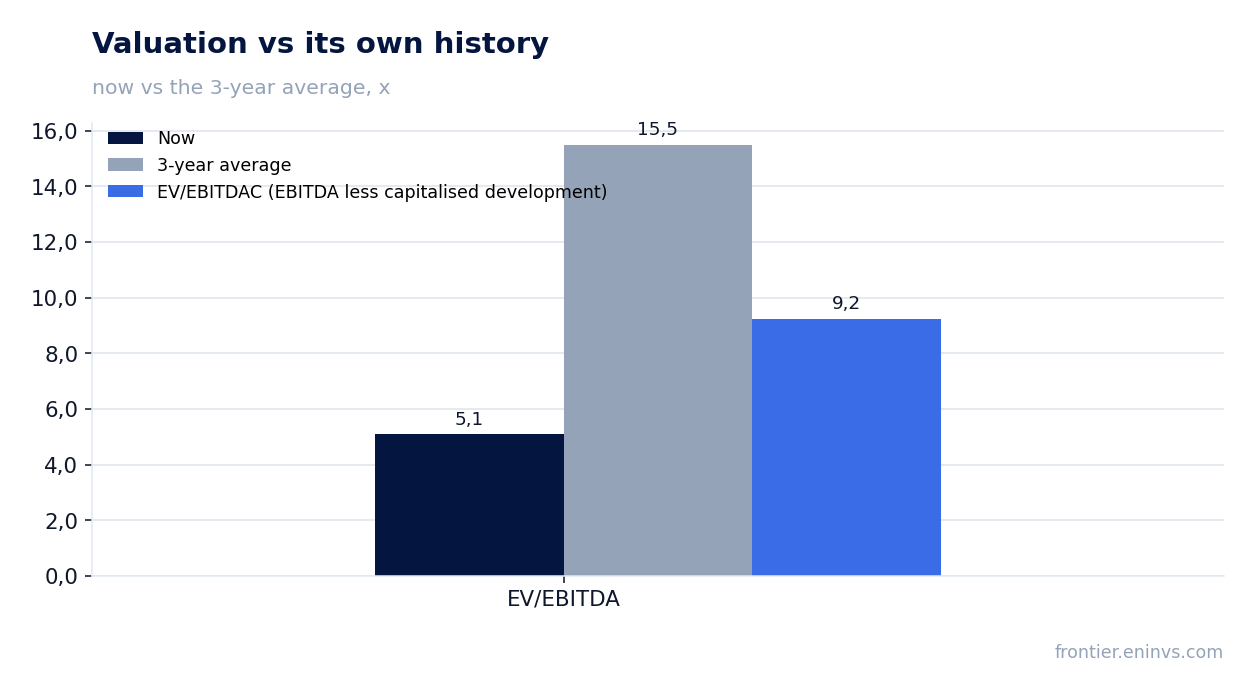
On EV/EBITDAC the stock trades at 10.1 against a three-year EV/EBITDA average of 15.5
EV/EBITDAC LTM is 10.1. This is an important metric for a company that capitalises development: EBITDA without accounting for capitalised costs flatters the margin. For comparison, EV/EBITDA LTM is 5.6, and the three-year average EV/EBITDA is 15.5. Thus, on EV/EBITDA the stock trades well below its history, but on EV/EBITDAC the gap is smaller.
P/E LTM is 6.78, also below historical levels, but LTM profit includes one-off factors from the fourth quarter of 2025, when quarterly net profit was RUB 13,034.1 mn. Without that quarter, profit would be significantly lower.
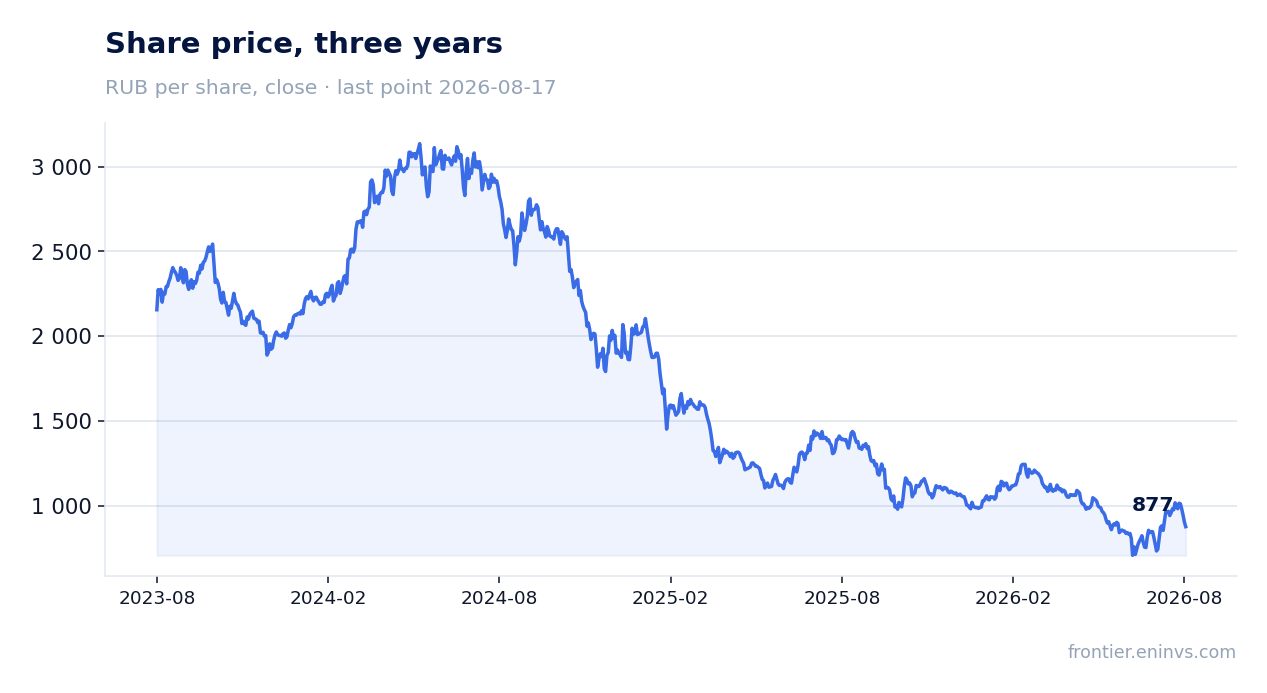
On the portal's model, the upside to fair value is +44%. This is our own estimate based on EBITDA growth and a target multiple, not a market consensus. Market capitalisation is RUB 74,076.8 mn.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 74.1 bn ₽ |
| P/E (LTM) | 6.8 |
| EV/EBITDA (LTM) | 5.6 |
| EV/EBITDAC (EBITDA less capitalised development) | 10.1 |
| P/B | 3.04 |
| Net debt / EBITDA (LTM) | 0.76 |
| Operating cash flow (LTM) | 7.79 bn |
| ROE | 0.5% |
| EV/EBITDA, 3-year average | 15.5 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2020 | 150.44 | — |
| 2022 | 19.56 | 1.5% |
| 2023 | 53.67 | 2.6% |
| 2024 | 47.30 | 1.6% |
Bottom line
Positive Group delivered strong revenue growth of 38.9% and returned to positive EBITDA, but net profit remains symbolic due to interest expense and amortisation. Operating cash flow was negative in the second quarter, and net debt rose to RUB 13.1 bn. The stock trades below its three-year history on EV/EBITDA, but the discount is smaller on EV/EBITDAC. At the current price the share looks rather attractive than not, but confirmation requires sustainable profit growth and improved cash flow.
Open the company's financial profile POSI →
See also: market overview · valuation map · stock screeners