Promomed: Revenue and EBITDA up 76%, but operating cash flow turned negative at RUB 1.8bn
31 августа Промомед раскрыл результаты за первое полугодие 2026 года: выручка выросла на 75,7% до 22,8 млрд руб., EBITDA – на 86,4% до 7,7 млрд руб., чистая прибыль – на 83,4% до 2,6 млрд руб. При этом операционный денежный поток составил минус 1,8 млрд руб. против минус 0,7 млрд руб. годом ранее. На текущей цене акция выглядит привлекательно: мультипликаторы заметно ниже собственной трёхлетней истории, а модель портала показывает потенциал роста на 62%.
Key takeaways
— Promomed's revenue for the half-year grew 76% to RUB 22.8bn – more than five times faster than the market
— EBITDA increased 86% to RUB 7.7bn, with margin expanding 2 p.p. to 33.8%
— Net profit rose 83% to RUB 2.6bn, but operating cash flow turned negative at RUB 1.8bn
— Leverage: net debt / EBITDA LTM stood at 0.94x – below the three-year average
— Dividend yield of 2.1% – modest, but the company has just started paying
— The portal's model estimates the share's upside at 62% from the current price
— The company confirmed its 2026 guidance: 60% revenue growth with 45% EBITDA margin
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 13.0 | 22.8 | +75.7% |
| EBITDA | 4.13 | 7.70 | +86.4% |
| Operating profit | 3.48 | — | — |
| Net profit | 1.42 | 2.60 | +83.4% |
| Operating cash flow | -0.74 | -1.80 | — |
| Capex | 1.39 | 1.50 | +7.7% |
| EBITDA margin | 31.8% | 33.8% | +2.0 pp |
| Net margin | 10.9% | 11.4% | +0.5 pp |
Promomed's revenue for the half-year grew 76% to RUB 22.8bn – more than five times faster than the market
In the first half of 2026, Promomed's revenue reached RUB 22.8bn, up 75.7% year-on-year. Growth outpaced the pharmaceutical market by more than five times, as the market grew 14.5% according to IQDATA. The company took first place among drug manufacturers in the Russian commercial market with a 4.83% share.
The main driver was the Endocrinology segment, where sales surged 243% to RUB 16.3bn, accounting for 71% of revenue. The flagship drug Tirzetta® became the best-selling product in Russian pharmacies. The Oncology segment declined 39% to RUB 2.6bn due to the shift of key tenders to the second half, while Other Drugs remained flat at RUB 4.0bn.
EBITDA increased 86% to RUB 7.7bn, with margin expanding 2 p.p. to 33.8%
EBITDA for the first half of 2026 grew 86.4% to RUB 7.7bn, with EBITDA margin at 33.8% versus 31.8% a year earlier. Margin expansion was driven by gross profit growth of 91% to RUB 15.2bn, with gross margin up from 61% to 67% thanks to a shift toward higher-margin innovative drugs.
Commercial and administrative expenses grew slower than revenue: the share of general and administrative costs fell 0.5 p.p. to 13.1%. The company confirmed its 2026 guidance: 60% revenue growth with 45% EBITDA margin, implying further margin improvement in the second half.
Net profit rose 83% to RUB 2.6bn, but operating cash flow turned negative at RUB 1.8bn
Net profit for the first half of 2026 stood at RUB 2.6bn, up 83.4% year-on-year. Net margin rose from 10.9% to 11.4%. Growth was driven by a significant increase in operating profit amid strong sales of key drugs.
However, operating cash flow was negative at minus RUB 1.8bn versus minus RUB 0.7bn a year earlier. The reason is the growth in net working capital to RUB 29.7bn from RUB 21.4bn at end-June 2025: the company was building inventories and receivables in a phase of active growth. Free cash flow was also negative at minus RUB 4.5bn (minus RUB 2.1bn a year earlier).
Leverage: net debt / EBITDA LTM stood at 0.94x – below the three-year average
As of end-June 2026, Promomed's net debt stood at RUB 16,804.5m, with net debt / EBITDA for the last twelve months at 0.94x. This level is notably below the three-year average, though comparable figures for earlier periods are not in the facts, so we do not assess the trend.
Absolute net debt increased by RUB 1.7bn from the previous reporting date and by RUB 5.5bn over the last 12 months. The company raised financing for strategic investments: in March it placed bonds worth RUB 6.8bn, using proceeds for refinancing and corporate purposes. The debt level remains moderate and does not threaten the guidance.
Dividend yield of 2.1% – modest, but the company has just started paying
Over the last 12 months, Promomed paid RUB 8.0 per share, providing a dividend yield of 2.1% at the current price. These are the first dividends in the company's history – during the period it updated its dividend policy and launched a liquidity support programme.
For a fast-growing pharma company, such a yield is not a key investment argument, but it signals readiness to share profits with shareholders. Combined with the free-float increase from 6.7% to 8.5%, this is a step toward greater attractiveness for institutional investors.
The portal's model estimates the share's upside at 62% from the current price
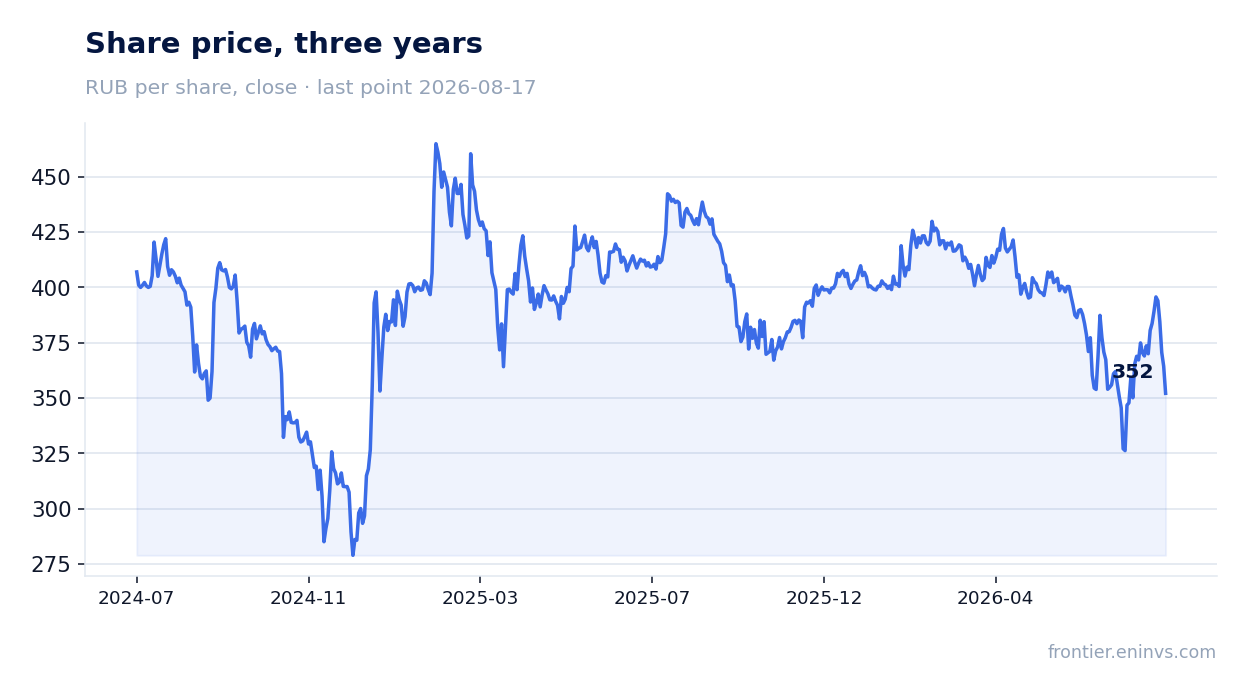
According to the portal's model, based on EBITDA growth and a target multiple, the upside potential of Promomed's share is +62% from the current price. This is our own model's calculation, not a market consensus or a target price.
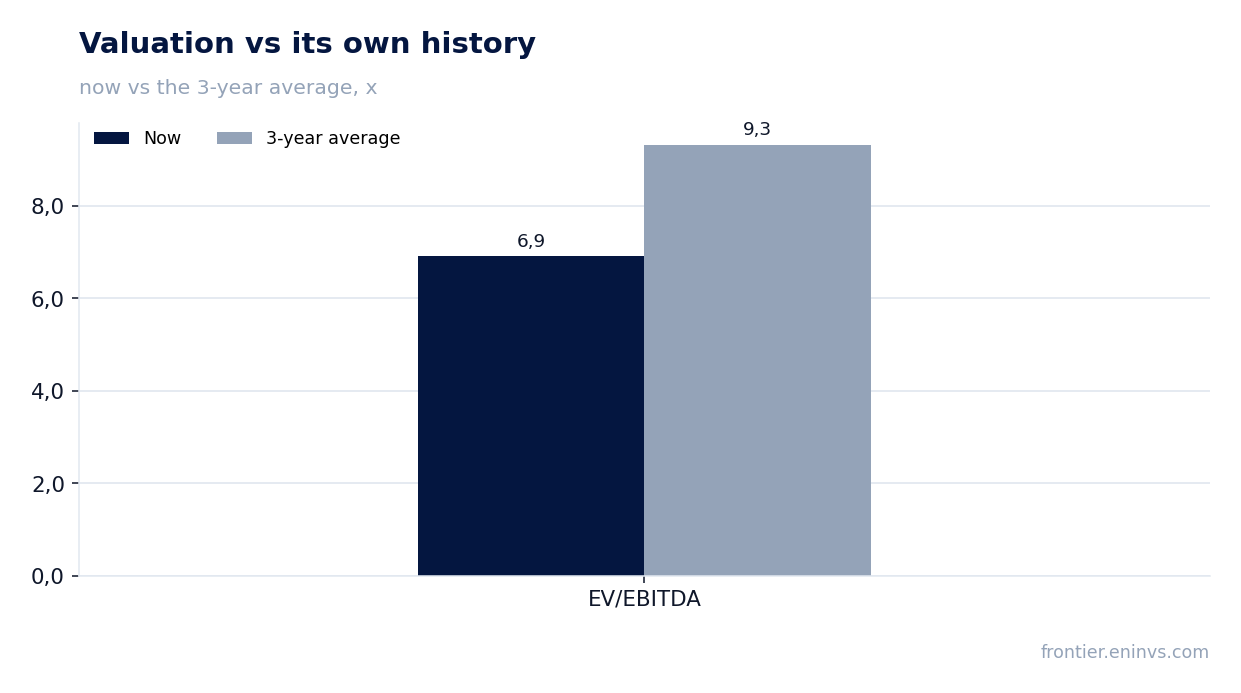
The share trades at P/E LTM of 9.78x and EV/EBITDA LTM of 5.53x, significantly below the three-year average EV/EBITDA of 9.32x. Even accounting for a slowdown in growth in the second half, the current valuation looks attractive.
The company confirmed its 2026 guidance: 60% revenue growth with 45% EBITDA margin
Promomed confirmed its 2026 financial guidance: 60% revenue growth with 45% EBITDA margin. In the first half, revenue grew 75.7%, in line with the trajectory, while EBITDA margin of 33.8% lags the annual target, but the company expects acceleration in the second half due to the concentration of oncology tenders and new launches.
In the second half, the company plans new product launches, including treatments for prostate cancer and HIV infection, which should support sales in the budget segment. Management also expects working capital optimisation, which could improve operating cash flow.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 81.7 bn ₽ |
| P/E (LTM) | 9.8 |
| EV/EBITDA (LTM) | 5.5 |
| P/B | 4.16 |
| Net debt / EBITDA (LTM) | 0.94 |
| Operating cash flow (LTM) | -0.79 bn |
| ROE | 43.1% |
| Dividend yield (12m) | 2.0% |
| EV/EBITDA, 3-year average | 9.3 |
Bottom line
Promomed reported a strong first half: revenue and EBITDA grew over 75%, margins expanded, and leverage remains moderate. However, behind the profit lies negative operating cash flow – the company is actively building inventories and receivables, requiring financing. The share trades at a discount to its own three-year history, and the portal's model shows 62% upside, making the stock attractive at the current price. The key question for holders is whether the company can convert profit growth into cash flow in the second half and confirm its 45% margin guidance.
Open the company's financial profile PRMD →
See also: market overview · valuation map · stock screeners